

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cab Mounts Market Set to Grow at a 5.0% CAGR, Signaling Strategic Opportunities for OEMs

Worldwide Cab Mounts Market — Strategic Outlook and Decision Playbook for 2026
As PW Consulting’s lead industry analyst, I present a forward-looking synthesis of our newest market research on the Worldwide Cab Mounts market. This briefing highlights the strategic value of the full 2026–2032 forecast study for corporate leaders, product teams, supply-chain heads and M&A strategists preparing decisions in 2026. The analysis below signals where value creation will accrue, what competitive moves will matter, and how to prioritize investments — while preserving the granular datasets and proprietary segmentation that make the full report essential for execution.
Worldwide Cab Mounts Market
Executive snapshot: resilient growth, clear catalysts
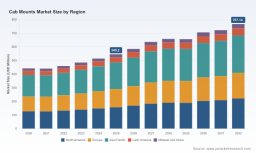
The cab mounts market has displayed steady recovery and growth through the recent cycle. After navigating pandemic disruptions and supply-chain pressures, the industry reached an estimated market size of USD 545.2 Million in 2025 (base year), and our modelling points to an expected USD 584.97 Million in 2026. Under the scenarios embedded in the report, the market grows at a compound annual growth rate (CAGR) of 5.0% over the 2026–2032 forecast horizon, with a projected market value near USD 767.14 Million by 2032.
Worldwide Cab Mounts Market
This steady mid-single-digit growth is driven by converging forces: rising adoption of advanced vibration-damping technologies in off‑highway equipment, heightened regulatory and occupational-safety expectations, and OEMs’ renewed focus on operator comfort as a differentiator in equipment procurement.
Worldwide Cab Mounts Market
Why this matters for 2026 decision-makers
- Investment prioritization: A clear, multi-year growth runway enables manufacturers and suppliers to justify targeted investments in R&D (viscous and fluid-damped mounts, hybrid materials), capacity expansions, and regional service footprints — but only where market dynamics and unit economics align.
- Product strategy: Evolving operator-comfort expectations and whole‑body-vibration mandates are shifting product requirements from basic rubber-to-metal solutions to more complex hybrid systems. Product roadmaps that integrate material science, NVH (noise-vibration-harshness) modelling, and modular designs will capture premium segments.
- Supply-chain resilience: Raw material composition — primarily elastomers bonded to metal substrates — exposes manufacturers to volatility in elastomer feedstocks and metal prices. Strategic procurement, dual-sourcing, and long-term supplier agreements are now hygiene factors for margin protection.
- M&A and partnership screening: Given a moderately concentrated supplier base with differentiated capabilities, 2026 is a pivotal year to pursue tuck-ins that add material expertise, fluid-damping technologies, or regional OEM relationships. Our full report provides candidate scoring against technical fit, commercial synergies and integration risk.
Market dynamics driving the 2026 strategic agenda
- Technology shift toward hybrid damping: Viscous and fluid‑elastic solutions—combining elastomers and internal damping fluids—are gaining traction where NVH performance and lifecycle durability are mission critical. Adoption patterns are especially pronounced in off‑highway rigs where operator hours are long and exposure to whole-body vibration is regulated or tightly monitored.
- Operator safety and regulation: Cab mounts play a material role in compliance with ROPS and related safety standards. Buyers increasingly evaluate mounts not just on cost and life, but on documented compliance and test performance under standardized rollover and vibration protocols.
- Raw-material & manufacturing considerations: The industry’s core components remain rubber-to-metal bonded assemblies using natural or synthetic elastomers mated to steel or similar substrates. This underpins both product performance and cost structure: material selections and bonding processes determine fatigue life, environmental resistance and manufacturability.
- Commercial channel evolution: OEMs continue to consolidate procurement, but aftermarket and retrofit channels remain vital, especially in ag and construction equipment where fleet operators prioritize lifecycle comfort and uptime. Serviceability and rapid replacement logistics are becoming differentiators.
Competitive landscape — who matters and why
The market is characterized by several established engineering-first suppliers and specialist manufacturers offering differentiated technologies. The competitive positions we profile in the report demonstrate a mix of deep engineering capability, broad product portfolios, and channel strength that will determine winners in 2026 and beyond:
- Trelleborg AB (Trelleborg, Sweden): A leader in high‑performance anti‑vibration solutions with a comprehensive industrial catalogue. Its portfolio and recent catalogue updates underscore a product-led strategy aimed at off‑highway vehicle segments.
- Link Manufacturing (Sioux Center, Iowa, USA): Globally recognized for cab suspensions and complete air-suspension systems, Link’s focus on air-based systems for heavy trucks and specialty vehicles positions it strongly where ride quality and retrofitability are prioritized.
- GMT Rubber-Metal-Technic Ltd (UK): Known for cone mounts and progressive-stiffness designs, GMT’s engineered rubber-metal systems address high-shock load applications typical in heavy machinery.
- AMC-MECANOCAUCHO (Spain): Specialist in rubber-bonded metal mounts with tailored hardnesses and load ratings; their ROPS-focused testing capability is a competitive advantage for safety-first OEMs.
- Parker LORD (formerly LORD Corporation, USA): A technology pioneer in viscous and Fluidlastic mounts, combining elastomeric and fluid damping — solution sets that capture premium NVH performance requirements.
- Hutchinson SA (France) & SumiRiko (Japan): Both suppliers bring global manufacturing scale and product breadth, serving both on‑highway and off‑highway equipment segments with standard and custom isolation solutions.
Notably, competitive advantage is created through product breadth, engineering services (testing, ROPS support), and aftermarket distribution. The industry is neither fragmented nor monopolized — leading firms hold meaningful scale but non‑dominant market shares, leaving room for targeted entrants and consolidation plays. The full report contains a quantified competitive map and a ranked capability matrix to help you shortlist partners and acquisition targets.
Practical actions for 2026
- Prioritize product investment by measurable ROI: Use NVH performance thresholds and regulatory testing outcomes to create tiered product roadmaps — basic rubber mounts for cost-sensitive fleets, and hybrid viscous designs for premium and regulated applications.
- Hedge raw-material exposure: Lock in elastomer supply contracts, qualify second-source metal suppliers, and investigate alternative compound formulations that offer comparable performance with improved cost or sustainability characteristics.
- Optimize aftermarket and services: Deploy predictive-fitment catalogs, accelerated logistics hubs near major equipment clusters, and value-added services such as installation training and warranty analytics to increase lifetime revenue per unit.
- Screen M&A by capability gaps: Target targets that close gaps in fluid-damping tech, high-load elastomer formulations, or that add durable relationships with OEMs in growth geographies. Use the report’s M&A heatmaps and synergy models to accelerate diligence.
- Embed testing and certification as commercial tools: Make ROPS validation and documented NVH improvements a part of the sales narrative; buyers will pay a premium for validated performance and reduced operator fatigue liability.
What the full PW Consulting report delivers
The public summary above is a strategic preview. The complete Worldwide Cab Mounts Market report (base year 2025, forecast 2026–2032) equips decision‑makers with:
- Historical market tracking (2020–2025) and scenario-based forecasts through 2032, expressed in USD Million and incorporating granular sensitivity testing.
- Proprietary demand-models calibrated to equipment OEM build rates, fleet replacement cycles and regulatory adoption curves.
- High-resolution competitive benchmarking: product portfolios, technological differentiation, channel reach and a ranked target list for M&A or partnership consideration.
- Supply-chain risk maps focusing on elastomer and metal feedstocks, with mitigation playbooks and cost-impact scenarios.
- Actionable go‑to‑market templates for OEM, aftermarket and retrofit channels — including pricing strategies and service-pack options designed to accelerate uptake.
- Primary-sourced interviews and product-spec validations from leading suppliers and OEM engineering teams to substantiate technical assumptions.
Recent industry signals to watch in 2026
- Catalog and portfolio refreshes: Premium suppliers have recently updated product catalogues and engineering guides — a sign they are consolidating technical leadership and preparing commercial push strategies that will influence OEM procurement cycles.
- Technology diffusion: Expect increasing cross-adoption of viscous and hybrid-damping approaches in niches previously dominated by rubber-only solutions; performance demands and operator-safety metrics are the accelerants.
- Procurement sophistication: Buyers are requesting validated lifecycle cost analyses, shifting supplier selection from price-first to value-first evaluations.
How to use this report in 90 days
- Day 0–30: Align leadership on prioritized use cases (OEM, aftermarket, retrofits) and run the report’s profitability stress-tests on current product lines.
- Day 30–60: Execute supplier audits for elastomer and metal exposures, and begin technical trials for any new compound or fluid-damping components identified as high-value.
- Day 60–90: Complete a shortlist of M&A or partnership targets using the report’s capability matrix and initiate preliminary outreach supported by our commercial-case templates.
Concluding observation
The cab mounts market presents a compelling, mid-single-digit growth opportunity underpinned by technological substitution, regulatory reinforcement and buyer willingness to pay for demonstrable comfort and safety benefits. For 2026, leaders who combine material science investment, robust supply-chain hedging and a service-led aftermarket strategy will be best positioned to convert projected market growth into sustainable margin expansion.
PW Consulting’s full study contains the detailed segmentation, regional and application-level analytics, and proprietary company benchmarking necessary to operationalize the strategies outlined here. To access the granular datasets, candidate acquisition targets, and the complete implementation playbook, please consult the full Worldwide Cab Mounts Market report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide Cab Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com