

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Soundproof Ventilator Market Poised for a 6.18% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Soundproof Ventilator Market — Strategic Imperatives for 2026
As governments, building owners and specifiers raise the bar on occupant comfort, energy performance and acoustic protection, the global market for soundproof ventilators is entering a decisive growth phase. PW Consulting’s latest market study establishes the industry’s baseline in 2025 and models forward to 2032, highlighting a stable expansion pathway: a mid-single-digit compound annual growth rate (CAGR) of 6.18% across the 2026–2032 forecast window and a market that grows from a 2025 baseline into a materially larger opportunity by 2032. For executives planning product roadmaps, capital allocation or M&A activity in 2026, the report delivers concise, actionable evidence to prioritize investments and de-risk strategic choices.
Worldwide Soundproof Ventilator Market
Why soundproof ventilation becomes a board-level issue in 2026
-
Regulatory convergence: Major jurisdictions are tightening rules that couple ventilation, energy efficiency and noise limits. Notable examples include noise guidance embedded in UK's Approved Document F and evolving building energy codes in jurisdictions such as California with standards that take effect for permits from 2026. These regulatory vectors force product specifications to meet both thermal and acoustic thresholds simultaneously.
Worldwide Soundproof Ventilator Market -
Occupant-centric building economics: Employers, multifamily owners and healthcare operators increasingly view acoustic performance as a measurable contributor to productivity, rental yield and clinical outcomes. This elevates acoustically-optimized ventilation systems from niche upgrade items into strategic retrofit and new-build specifications.
Worldwide Soundproof Ventilator Market -
Technology and materials momentum: Advances in passive and hybrid architectures, acoustic louvers, melamine and composite absorbers, and compact heat-recovery integration are enabling higher performance without proportional energy penalties—opening specification windows in noise-polluted urban cores and in energy-constrained retrofit programs.
-
Channel and solution convergence: Decentralized ventilation, window-integrated slots and dedicated acoustic inlets are now converging with building controls, IAQ sensors and filtration—creating bundled revenue and service models that change procurement economics for installers and specifiers.
What our report delivers — operational, decision-grade assets
-
Validated market sizing and a transparent forecast model: We provide an audited 2020–2025 historical series and scenario-driven projections through 2032 that underpin strategic planning and business-case sensitivity testing for 2026 budgets.
-
Regulatory and standards map: A compliance playbook that translates regional regulation (noise limits, ventilation rates, energy codes) into product requirements and certification paths for product development and market entry.
-
Competitive supplier intelligence: Scorecards synthesizing product portfolios, acoustic certifications, distribution footprints, and recent commercial moves for the key incumbents and emerging players—benchmarks you can use to identify capability gaps or acquisition targets.
-
Go-to-market blueprints: Channel strategies, specification targeting, installer enablement and value-based pricing tactics for both OEMs and distributors seeking fast penetration in retrofit and new-build segments.
-
Technical decision tools: Acoustic performance benchmarking templates (dB metrics under defined flow conditions), lifecycle cost calculators, and materials cost sensitivity models that link raw-material trends to unit economics.
-
M&A and partnership playbooks: Deal-screen criteria, valuation sensitivity tests and integration checklists tailored for roll-up strategies in a market characterized by moderate concentration.
Market structure and competitive implications
The market remains moderately fragmented: the three largest suppliers account for roughly a third of market sales while the five largest capture less than half. This structure creates a dual dynamic in 2026—there is enough scale among incumbents to set technical norms and distribution practices, but substantial whitespace remains for focused challengers, regional champions and vertically integrated OEMs. For strategy teams this means both organic growth and bolt-on consolidation are viable pathways depending on capital availability and execution speed.
Profile-led competitive analysis (strategic takeaways)
-
LUNOS Lüftungstechnik GmbH (Berlin): Deep expertise in decentralized systems and high-insulation product lines positions LUNOS as a leader in residential new-builds and acoustic retrofits where decentralized heat recovery is required. Their product depth makes them a natural partner for window and façade integrators.
-
SIEGENIA GROUP (Germany): With dedicated sound-absorbing wall and window solutions, SIEGENIA’s emphasis on whisper-quiet operation and integrated controls targets projects where specification-level acoustic performance is a procurement criterion.
-
Ventomaxx GmbH (Landshut): Strong positioning around DIN 4109 compliance and hybrid decentralized concepts makes Ventomaxx a prime supplier for noise-sensitive German and Central European markets and for consultants specifying to strict national standards.
-
Titon Holdings plc (UK) / R.W. Simon Ltd (UK): These UK specialists in acoustic trickle vents and humidity-controlled units combine niche product capability with distribution access into the UK retrofit channel—advantageous where compliance with Approved Document F and bedroom noise limits is a procurement trigger.
-
FläktGroup / TROX / Greenheck: Global ventilation platforms with acoustical accessories and silencers. Their scale and systems-level capabilities make them preferred suppliers for large commercial and industrial projects where integration with HVAC plant is required.
-
Wuxi Sinceriend (China): Material and cost-competitive acoustic vent producer well positioned to serve OEMs seeking component-level sourcing or volume-driven replacement programs in emerging markets.
Recent moves that alter the 2026 competitive map
-
LUNOS’s trade show presence in early 2026 underscores continued investment in channel visibility and specification-level engagement—an important signal for firms seeking OEM or distribution partnerships in Europe.
-
Product innovations such as the QuietFlow Acoustic Louvers system (announced in mid‑2025) highlight the role of advanced absorptive materials—e.g., fire-rated melamine foams—and modular silencer architecture in expanding applicability into energy infrastructure and cooling applications beyond traditional building ventilation.
-
Raw material dynamics—galvanized steel, aluminum and acoustic foams—continue to drive cost and design tradeoffs. Monitoring supplier lead-times and life-cycle impacts is essential for 2026 procurement planning.
Five strategic moves executives should consider in 2026
-
Prioritize acoustic performance in product roadmaps: Integrate validated acoustic ratings (lab Dn,e,w and in-situ results) into minimum viable product specs. Performance differentiation will increasingly drive premium positioning and specification wins.
-
Pursue compliance-first market entry: Align product certification pathways with key target markets up front (e.g., UK noise guidance, German DIN compliance, and updated US state energy/ventilation codes) to avoid costly rework in certification-heavy geographies.
-
Target channel partnerships for retrofit scale: Work with glazing, façade and mechanical contractors to create bundled retrofit propositions—pilot projects demonstrating measurable indoor-noise reduction will accelerate broader adoption.
-
Use bolt-on M&A selectively: Given the moderate market concentration, acquisitive moves that add acoustical IP, fabrication scale or channel access can be highly accretive—focus diligence on acoustic test data, product certification completeness and installer training assets.
-
Lock in materials and test for durability: Secure supply agreements for high-performance absorptive materials and validate long-term performance under moisture, fire and particulate-loading conditions to reduce warranty risk and specification resistance.
How PW Consulting’s deliverables accelerate 90‑day decisions
-
Immediate: Use our regulatory mapping and specification checklists to update product requirements and RFP templates; run a one-page ROI test for any pilot retrofit opportunity.
-
30–60 days: Execute a supplier due-diligence sprint using our vendor scorecards to short-list two acquisition or partnership targets and launch product certification streams aligned with priority geographies.
-
60–90 days: Deploy a pilot with one installer partner in a noise-sensitive asset class (multi-family or student housing) using our acoustic benchmark protocols and capture field data for scaling the sales playbook.
Concluding perspective
By 2032 the market we model grows meaningfully from its 2025 base under a 6.18% CAGR, reflecting sustained demand for solutions that reconcile ventilation needs with acoustic protection. For strategy teams, the question in 2026 is not whether the market will grow, but how to capture a defensible share—through validated acoustic performance, thoughtful certification strategies, channel economics that prioritize retrofit scale, and selective consolidation. PW Consulting’s Worldwide Soundproof Ventilator Market report gives you the data, the compliance translation and the tactical playbooks to make those choices with confidence.
For access to full segment-level tables, granular regional and application splits, supplier scorecards and downloadable modelling files, the report and supporting datasets are available on our website. These contained assets provide the detailed inputs you will need to finalize 2026 budgets and execute the first pilots that convert acoustic performance into commercial advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Soundproof Ventilator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Soft Shackle Market to Hit USD 545.43 Million by 2032, Growing at a 7.21% CAGR
By pmarketresearch, 2026-07-15
Worldwide Soft Shackle Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market study on the worldwide soft shackle market (base year 2025; historical period 2020–2025; forecast 2026–2032) provides a concise, decision-grade view of an evolving specialty-ropes sector. The market has expanded materially over the last half-decade — rising from USD 236.42 Million in 2020 to USD 335.25 Million in 2025 — and is projected to continue a steady trajectory, reaching an estimated USD 380.64 Million in 2026 and USD 545.43 Million by 2032. This implies a compound annual growth rate (CAGR) of approximately 7.21% across the forecast horizon. For executives preparing budgets, sourcing strategies, product roadmaps, or M&A pipelines in 2026, the report synthesizes actionable insight while preserving detailed segment-level tables for authorized subscribers.
Worldwide Soft Shackle Market
Why this market matters in 2026
- Material substitution is strategic: Ultra-high molecular weight polyethylene (UHMWPE, commonly branded as Dyneema or Plasma) and next-generation aramids are displacing metal shackles across multiple use cases due to superior strength-to-weight ratios, corrosion resistance and flotation. Procurement and product teams must internalize the technical and supply nuances of these fiber platforms.
- Multi-industry tailwinds: The convergence of off-road/automotive recovery, marine/sailing, industrial lifting and specialty military applications creates a diversified demand base that reduces single-market cyclicality but increases the need for tailored product standards and channel strategies.
- Certification becomes a market access lever: Military purchasing rules (e.g., Berry Amendment / Buy American Act compliance in certain programs) and the ability to certify products to recognized safety margins (including 5:1 safety factor tagging for overhead lifting upon request) are differentiators for suppliers targeting institutional buyers.
- Fragmented supplier landscape: Market concentration remains low — the top three players account for under one fifth of market revenue, and the top five account for roughly a quarter — signaling both acquisition opportunities for strategic consolidators and white-space for specialized incumbents to scale.
What the PW Consulting report delivers (practical, decision-ready content)
- Transparent market-sizing and growth drivers: full reconciliation of historical demand (2020–2025) and scenario-based forecasts (2026–2032), including base, accelerated-adoption and downside scenarios tied to raw material availability and macro trade dynamics.
- Supply-chain heat map: mapping of fiber producers, rope manufacturers, shackle assemblers and value-added coating/finishing providers; identification of single-source exposures and feasible hedges.
- Commercial playbooks: go-to-market strategies for B2B channels (distributors, OEMs, fleet operators) and B2C channels (aftermarket off-road and marine enthusiasts), with recommended pricing frameworks and bundling tactics for different use cases.
- Regulatory & certification checklist: concise guidance on military procurement qualifiers, recommended lab testing protocols, traceability and serialization practices, and how to cost these into bids and contracts.
- Product development scorecards: prioritized R&D themes (abrasion jackets, UV-stable coatings, threaded vs loop closure designs, and rope-on-rope connectors) with estimated time-to-market and ROI ranges.
- M&A and partnership templates: target-screening filters, valuation multiples observed in adjacent synthetic rope segments, and post-deal integration playbooks to capture synergies in manufacturing and channel access.
- Operational tools: supplier scorecards, a downloadable financial model for scenario planning, and a risk register template focused on raw material shortages, certification delays and key-customer concentration.
Competitive landscape — strategic implications from company profiles
The market is characterized by a mixture of early adopters, vertically integrated specialists, and precision-engineered suppliers. PW Consulting’s benchmarking highlights the following profiles and the strategic lessons they imply:
Worldwide Soft Shackle Market
- ASR Offroad (USA) — One of the earliest commercial manufacturers in the space, producing HMPE/Plasma soft shackles from a certified manufacturing environment. Strengths: brand recognition in off-road recovery, ISO 9001:2015-certified processes, and domestic sourcing. Implication: first-mover advantages can be sustained through quality certification and traceable domestic supply chains, particularly for customers prioritizing origin and quality.
- Factor 55 (USA) — Positions quality and repeatable lab-validated performance at the center of its offering, targeting both consumer and closed-system winching applications. Strengths: field- and lab-tested minimum breaking strengths and protective treatments. Implication: meeting quantifiable performance claims backed by testing is an effective route to premium pricing and OEM partnerships.
- Bubba Rope (USA) — Emphasizes marine/towing and rugged industrial use, promoting synthetic shackles as superior-to-steel alternatives in hostile environments. Implication: vertical differentiation by application (marine vs. automotive) creates defensible niches.
- Safe-Xtract (USA) — Military-focused supplier with Berry Amendment and Buy American Act compliance, serialized traceability and factory load-testing. Implication: compliance and traceability unlock high-value institutional contracts, but require sustained investments in documentation and audit readiness.
- Cortland Company (USA) — Developing engineered connectors and rope-on-rope alternatives for lifting/rigging applications with rigorous fatigue and break-strength testing. Implication: advanced connector designs can expand soft shackle use into lifting segments if paired with recognized standards and certified testing regimes.
- Erickson Manufacturing, Robship, Wichard, Fulcrum Lifting, Dynamica Ropes — A set of specialist suppliers focused on marine, industrial lifting and rigging, with capabilities ranging from in-house rope manufacture and machine stretching to regionally strong brand equity. Implication: regional specialists will remain critical channel partners for OEMs and fleet operators; partnering or acquiring these assets accelerates market access.
Supply-side risks and technological inflection points
- Raw material concentration: The industry’s reliance on UHMWPE and advanced aramids creates sensitivity to feedstock availability, fiber capacity expansions and commodity pricing. Firms that secure fiber contracts or integrate upstream will reduce volatility risk.
- Coatings and coverings: Abrasion and UV resistance are decisive in determining real-world longevity. Proprietary coatings and braided protective jackets are differentiators that justify premium pricing and lower total cost of ownership for end users.
- Standards and testing: Ability to certify designs to overhead lifting safety margins or military specifications is an enabler for higher-value segments; conversely, failure to maintain robust test documentation can preclude access to institutional contracts.
- Manufacturing quality systems: ISO 9001:2015 and serialized traceability are table stakes for premium channels; investments here reduce warranty backlash and support higher ASPs.
Recommended strategic moves for 2026
- Prioritize channel-specific productization: Deliver differentiated SKUs for marine, off-road and industrial lifting with tailored warranty and certification packages rather than a one-size-fits-all range.
- Lock in critical fibers: Negotiate medium-term supply agreements or explore toll-manufacturing partnerships with rope makers to secure capacity and control quality drift.
- Invest in certs and testing: If targeting lifting or institutional buyers, build in lab testing, serialized traceability and compliance documentation from product inception — it shortens sales cycles and elevates deal size.
- Explore bolt-on acquisitions: Prioritize targets that provide channel access (marine distributors, off-road specialists), proprietary coating technologies, or in-house rope manufacture to capture margin and shorten lead times.
- Offer risk-sharing commercial models: Consider performance guarantees, buy-back programs, or bundled service-and-repair agreements for fleet customers to reduce buying friction and demonstrate total-cost advantage over metal alternatives.
How to use this report in 2026 planning
For commercial leaders, the report provides the market sizing and scenario sensitivity needed to set FY26 revenue targets and to stress-test pricing under variable fiber-cost assumptions. For procurement teams, the supply-chain heat map and supplier scorecards are templates for renegotiation and dual-sourcing playbooks. For product and engineering leaders, the R&D scorecards and testing benchmarks translate directly into prioritized roadmaps and CAPEX plans.
Worldwide Soft Shackle Market
Trailer — what is intentionally withheld
This public preview communicates strategic direction, supplier positioning and the high-level numbers that matter for resource allocation. To maintain the integrity of our commercial model and to protect client value, detailed segment-by-region and application-level revenue breakdowns, granular pricing matrices, and company-level market share tables are provided exclusively in the full PW Consulting report and downloadable data workbook. These detailed tables are the tools you will use to size investment cases, build M&A scorecards and run procurement RFQs.
Next steps — where to get the full intelligence
PW Consulting has prepared a suite of deliverables to accelerate your 2026 execution: the full market report (with downloadable segment matrices and financial models), custom workshops for portfolio prioritization, and bespoke target-screening for M&A pursuits in the soft shackle and synthetic rope adjacent markets. Contact PW Consulting to request the complete report package and to schedule a tailored briefing that maps these insights directly to your 2026 strategy.
PW Consulting — Strategic insight for material substitution markets and specialty rope systems.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Shackle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Agricultural Nanotechnology Market Set to Expand at a 14.03% CAGR, Driving Transformative Growth Through 2032
By pmarketresearch, 2026-07-15
Worldwide Agricultural Nanotechnology Market — Strategic Imperatives for 2026
PW Consulting’s latest market research, "Worldwide Agricultural Nanotechnology Market," provides an evidence-based playbook for executives, investors, and policy teams preparing to act in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes commercial, technical, and regulatory intelligence into a set of actionable recommendations. The market is on a multi-year expansion trajectory—growing from an assessed global value in 2020 to an estimated USD 325.5 Million (base year 2025), and projected to exceed USD 800 Million by 2032—reflecting a compound annual growth rate of 14.03% across the forecast period. This growth profile elevates agricultural nanotechnology from a niche research theme to a strategic growth vector for agri-inputs, precision farming, and seed and soil services businesses.
Worldwide Agricultural Nanotechnology Market
Why this matters for 2026 decision cycles
- Market timing and scale: The trajectory through 2026 signals that early movers who translate laboratory advantages to field-validated products stand to capture disproportionate value. The market’s expansion is broad-based—driven by technological maturation, farmer demand for efficiency, and rising regulatory and retailer pressure on sustainability metrics.
- Portfolio repositioning: Established agribusinesses and input manufacturers must decide in 2026 whether to treat nanotechnology as a core platform (integrated into fertilizer, crop protection and digital offerings) or as a complement to existing lines (licensed formulations, co-branded pilots).
- Innovation-to-commercialization cadence: The gap between R&D and scalable manufacturing remains the rate-limiting step. Decisions on capital allocation for pilot plants, contract manufacturing partners, and field trials will determine commercial viability by late-deployment windows (2027–2029).
What the report delivers — practical, decision-grade content
- Quantitative market sizing and validated growth scenarios for 2026–2032, presented with sensitivity analyses and upside/downside cases tied to regulatory outcomes and raw material availability.
- Go-to-market frameworks for product classes (from fertilizer and pesticide formulations to biosensors and soil amendments), including channel strategies, farmer adoption levers, and margin modeling.
- Supply chain diagnostics that map critical inputs, potential bottlenecks, and low-cost feedstock pathways—including opportunities to convert agricultural waste biomass into nanomaterials.
- Regulatory and safety roadmaps with recommended engagement strategies for 2026: tiered testing protocols, environmental monitoring frameworks, and stakeholder communication templates to mitigate toxicity and soil-ecosystem concerns.
- M&A and partnership playbooks: target archetypes, valuation pruning principles, and integration checklists for acquiring IP, scaling manufacturing, or accessing distribution networks.
- Commercial pilot blueprints and KPIs—how to structure replicated field trials, what yield and input-efficiency metrics to collect, and the economics that will convince commercial partners and farmers.
Market dynamics and structural drivers
The convergence of several macro drivers underpins the market’s 14.03% CAGR through the forecast: continued pressure to reduce input volumes while sustaining yields; advances in nano-enabled formulations that improve active ingredient delivery and retention; and the integration of nanotechnology with precision agriculture platforms for real-time soil and crop feedback. That said, industry adoption is uneven. Cost differentials versus conventional inputs remain material in early commercialization, and environmental safety questions—especially around nanoparticle fate in soil ecosystems—create regulatory uncertainty that influences time-to-market.
Worldwide Agricultural Nanotechnology Market
Competition and strategic positioning — who to watch
Competitive structure is moderately concentrated: the top three suppliers do not dominate the market, and the top five account for roughly 43% of identifiable revenue—leaving meaningful space for innovative challengers and regional specialists. The competitive landscape is diverse: multinational chemical and seed companies are accelerating portfolio integration, established agri-input specialists and niche technology providers are commercializing focused solutions, and R&D-centric firms are pushing novel material science breakthroughs.
Worldwide Agricultural Nanotechnology Market
- Aqua-Yield Operations, LLC (Nano-Yield) — U.S.-based Nano-Yield has emerged as a notable commercial example of nano-fertilizer deployment. Its trajectory demonstrates how focused product-market fit and measurable agronomic benefits (nutrient use efficiency gains, lower application rates) can translate into rapid private-company growth and visibility among enterprise buyers.
- Indogulf BioAg LLC — Operating across U.S. and India markets, Indogulf is an example of hybrid commercialization: combining locally-relevant formulations with international distribution know-how to accelerate adoption in diverse cropping systems.
- Major multinationals (e.g., BASF SE, Syngenta AG) — These incumbents are accelerating development and expanding portfolios to include nano-enabled crop protection and seed treatment formulations. Their initiatives reduce commercial risk for the sector by investing in industrial-scale R&D, but they also raise competitive stakes for mid-sized specialists.
- India-based innovators and material suppliers — Several regionally focused players and research centers are advancing low-cost production routes and localized formulations—key to achieving price parity and farmer acceptability in high-volume commodity cropping systems.
- Materials and nanotechnology specialists — Suppliers of core nanomaterials and molecular-scale technologies are important upstream partners. Their IP and production capacities are strategic levers for both incumbents and new entrants.
Recent industry developments underscore these dynamics: incumbent chemical firms have accelerated nano-enabled product pipelines, high-growth private firms are gaining market recognition, and independent testing bodies have spotlighted certain nanoparticle types for next-generation biostimulant work. For competitive strategists, the takeaway is clear: access to dependable production, field-validated agronomy, and regulatory-compliant safety data are competitive differentiators in 2026.
Risk matrix: regulatory, environmental, and commercial
- Regulatory uncertainty: Concerns around nanoparticle toxicity and long-term soil impacts remain central. Companies should assume staggered regulatory trajectories across markets and plan for rigorous ecotoxicology programs.
- Raw material and cost risk: Production often starts with higher unit costs versus conventional chemistries. However, feedstock innovations—such as transforming agricultural waste biomass into nanomaterials—offer a pathway to lower-cost, lower-GHG production that also strengthens circular-economy credentials.
- Adoption risk: Farmer willingness to pay small premiums depends on clear, replicable yield and input-efficiency evidence. Pilots must demonstrate short payback windows and reduced operational complexity.
- Reputational risk: Poorly-communicated safety data or insufficient environmental monitoring can delay commercialization and invite restrictive policy responses.
2026 playbook — what market leaders will do this year
- De-risk field performance with layered trials: Combine controlled-environment studies, multi-site pilots, and independent third-party validations to accelerate farm-level trust. Build data dashboards to quantify inputs displaced, yield delta, and lifecycle GHG impacts.
- Secure manufacturing optionality: Invest in modular pilot plants or secure CMO arrangements to preserve capital and allow capacity scaling as demand crystallizes. Prioritize flexible lines that can process multiple nano-formulations.
- Lock in feedstock innovation: Explore partnerships with biomass processing firms and waste-management operators to develop low-cost nanomaterial feedstocks. This both reduces unit costs and supports sustainability claims.
- Invest in regulatory evidence early: Fund tiered environmental and toxicity studies in parallel with agronomic pilots to compress approval timelines. Proactively engage with regulators and standard setters to shape practicable frameworks.
- Embed digital assurance: Integrate nano-formulations with precision ag platforms and nano-sensor telemetry to create verifiable performance stories. Data-enabled offerings accelerate value capture through service bundles (e.g., subscription-based input + monitoring).
- Consider M&A and alliance pathways: Use bolt-on acquisitions to acquire manufacturing know-how or regional distribution; pursue co-development with incumbents to access scale and trusted market channels while retaining nimble innovation approaches.
How PW Consulting’s report supports your 2026 decisions
Our research distills empirical market sizing, supplier benchmarking, risk-adjusted scenario planning, and executable commercialization templates into a single deliverable designed for corporate strategy teams, R&D portfolio managers, and investment committees. The report provides the diagnostic and prescriptive layers required to set budgets, prioritize projects, or structure deals in 2026 without exposing the granular subsegment tables you’ll need to validate partner negotiations and M&A valuations. For clients, we also offer customized workshops to translate insights into board-ready investment plans and regulatory engagement calendars.
Conclusion — a narrow window to shape market outcomes
The agricultural nanotechnology sector stands at an inflection point. The market’s projected multi-year growth and the recent acceleration in product development by both nimble specialists and large incumbents create a narrow window in 2026 for strategic moves that capture long-term value. Executives who pair rigorous field evidence, manufacturing flexibility, regulatory foresight, and digital value capture will convert scientific promise into commercial scale. PW Consulting’s full report contains the granular segmentation, regional forecasts, and company-level scorecards needed to operationalize these recommendations.
For the complete dataset, proprietary subsegment analysis, and a tailored advisory session to align these insights with your 2026 objectives, please visit our report page and request an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Nanotechnology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Deicing Salt Market to Expand at 3.55% CAGR, New Report Finds
By pmarketresearch, 2026-07-15
Worldwide Deicing Salt Market: Strategic Intelligence for 2026 — Executive Preview
By PW Consulting — Senior Strategic Advisory & Industry Analysis
As winter-weather preparedness and infrastructure resilience climb higher on national agendas, deicing salt has re-emerged as a mission-critical commodity for public agencies, commercial operators, and industrial facilities. PW Consulting’s new market study — anchored on a 2025 base year and a detailed historical review from 2020–2025 — delivers the actionable intelligence executives and procurement leaders will need to shape strategy in 2026 and beyond.
Worldwide Deicing Salt Market
Market snapshot — what executives must know now
-
Market scale and trajectory: Our analysis places the global deicing salt market at roughly USD 2.7 billion in 2025 (base year). The market exhibited steady expansion over the 2020–2025 interval and, under our central forecast scenario, is expected to grow at a compound annual growth rate (CAGR) of approximately 3.55% through 2032, reaching just under USD 3.45 billion by the end of the forecast horizon.
Worldwide Deicing Salt Market -
Structure and concentration: The sector remains moderately fragmented — with the largest three suppliers accounting for a low double-digit share and the top five capturing slightly more — a structural feature that preserves competitive maneuvering room for both large incumbents and agile challengers.
Worldwide Deicing Salt Market -
Margin dynamics: Input-cost pressure from mining and evaporation operations, combined with localized regulatory constraints and logistics frictions, is compressing gross margins for commodity-grade salt while opening margin expansion opportunities for treated products and blended formulations.
Why this report matters for 2026 decisions
-
Procurement & contract strategy — From fixed-price procurement to indexed contracts tied to energy and freight benchmarks, the report provides frameworks to reduce exposure to raw-material and logistics volatility. The guidance is designed to help public agencies and large commercial buyers secure supply continuity while reducing total cost of ownership.
-
Supply assurance & resilience — We map practical levers for supply-path redundancy (mixing mine, evaporated and imported sources), buffer sizing, and strategic storage. Our scenarios quantify the trade-offs between inventory holding costs and service-level risk under seasonal demand spikes and production outages.
-
Product portfolio positioning — As regulators and end-users press for lower-corrosion and lower-environmental-impact alternatives, treated salts and chloride-reduction blends are becoming commercial imperatives. The report lays out go-to-market and R&D priorities for producers looking to differentiate beyond price.
-
Regulatory & sustainability alignment — With ongoing environmental constraints on chloride discharges and infrastructure corrosion, the regulatory landscape is both a risk and an innovation driver. Our compliance playbook helps companies prioritize investments in low-impact formulations and customer-facing sustainability credentials.
What’s inside the report — practical deliverables
-
Market sizing and forward-looking scenarios (base year 2025; forecast 2026–2032) with sensitivity testing against energy, freight, and weather variability.
-
Procurement playbook — contracting templates, escalation clauses, and inventory optimization models tailored for municipalities, airport operators, and large commercial fleets.
-
Supplier benchmarking — a framework to evaluate miners, evaporative producers, and formulators across operational capacity, logistical reach, environmental compliance, and product innovation.
-
Price-formation model — a transparent, auditable model linking input-cost drivers (energy, fuel, packaging, labor) to wholesale and street-level pricing under multiple scenarios.
-
Regulatory matrix — mapping critical jurisdictions, compliance triggers, and recommended mitigation measures for chloride-related environmental standards.
-
Investment and M&A screen — practical criteria for target selection, value-creation levers, and integration risks for players seeking to scale or diversify.
-
Executive decision dashboards — ready-to-use slide templates and a risk heatmap to brief boards and procurement committees.
Competitive landscape — implications for market players
-
Market incumbents and their strategic postures: Global producers with integrated mining and evaporation assets continue to shape supply fundamentals. Large vertically integrated firms retain advantages in logistics, scale, and multi-channel distribution, but the market’s fragmentation offers niches for high-value differentiated products.
-
Company profiles & strategic signals:
-
Cargill, Incorporated — A dominant industrial player with broad geographic reach. Recent capacity expansion announcements indicate an emphasis on supply reliability for key markets; potential acquirers or partners should factor Cargill’s scale when modelling competitive responses.
-
Morton Salt, Inc. — Traditional market leader in packaged and bulk road salts. Its entrenched relationships with municipal customers and private contractors make it a bellwether for pricing dynamics in North American urban corridors.
-
K+S Aktiengesellschaft — A European heavyweight with strong compliance and sustainability credentials; ISO 14001 updates underscore the premium placed on environmental governance in European supply chains.
-
Compass Minerals — Focused on product innovation in treated salts and corrosion-inhibited blends; recent launches demonstrate route-to-market potential for higher-margin formulations.
-
CNSIC (China National Salt Industry Corporation) — State-backed capacity that plays a role in Asian export dynamics and price pressure in coastal markets.
-
Ineos Enterprises, Cheetham Salt, Sudsalz and regional miners — These players sustain local supply, logistical optionality, and product variety that buyers rely on during peak demand.
-
-
Recent developments to watch: capacity expansions, product launches for corrosion-inhibited salts, and sustainability certifications are the primary competitive levers companies used in 2024–2025. Buyers and investors should treat these developments as signals of strategic priorities rather than isolated events.
Key dynamics shaping risk and opportunity
-
Input-cost pressure: Mining and evaporation costs rose materially in recent cycles due to energy inflation for underground operations and higher natural gas costs at evaporation sites. Those cost drivers are incorporated into our pricing model and are central to 2026 budgeting.
-
Regulatory pressure and product substitution: Environmental constraints on chloride discharges and recommendations from authorities to prefer magnesium chloride blends in certain applications are changing procurement specifications. This dynamic creates opportunities for suppliers with low-chloride or corrosion-inhibited products.
-
Packaging and logistics: Trade measures affecting steel and container costs have increased packaging and import costs in some markets. Our scenarios quantify the pass-through potential and provide contracting tactics to mitigate cost volatility.
-
Service-level risk from weather variability: More volatile winter patterns require flexible sourcing and dynamic inventory strategies — an area where the report’s seasonality models deliver immediate operational value.
Strategic plays for 2026 — prioritized actions
-
For producers: Accelerate product differentiation (treated salts, corrosion inhibitors, low-chloride blends), optimize asset utilization across mining and evaporation footprints, and pursue targeted M&A to secure logistic corridors and seasonal storage capacity.
-
For distributors and contractors: Lock in multi-year supply agreements with indexed pricing, invest in customer-facing sustainability credentials, and pilot blended formulations with municipal pilots to capture early-adopter premiums.
-
For public-sector buyers: Revisit specification frameworks to balance environmental mandates with operational effectiveness; deploy strategic reserves and use tiered procurement to combine competitive pricing with supply assurance.
-
For investors and private equity: Seek targets that combine stable cash generation with product innovation capability or logistics assets that enable seasonal margin capture.
Risk scenarios and contingency planning
-
Short spike scenario — severe winter season combined with port congestion: we model the impact on spot prices, recommend trigger points for releasing strategic reserves, and provide supplier prioritization matrices.
-
Regulatory shock scenario — accelerated restrictions on chloride use: the report outlines near-term mitigation (blends, alternative abrasives) and a medium-term R&D roadmap for substitution technologies.
-
Input-cost inflation scenario — sustained energy price rise: our price-formation model helps translate fuel and electricity cost shocks into contract clauses and hedging considerations.
How to use the full PW Consulting study
-
Operational teams will find immediately actionable procurement templates, inventory sizing calculators, and supplier scorecards.
-
Strategy and M&A teams can use the investment screen and scenario valuation models to prioritize targets and size integration synergies.
-
Regulatory and sustainability teams can adopt the compliance matrix and stakeholder-mapping to design credible transition plans for low-impact products.
PW Consulting’s Worldwide Deicing Salt Market report blends market-scale analytics (base year 2025, projected through 2032 at a ~3.55% CAGR), proprietary scenario tools, and hands-on operational playbooks. We deliberately provide depth in strategic guidance while reserving certain granular segment-level tables and the full modelling workbook for subscribers and report purchasers. That granular intelligence — including our region- and application-level demand models, supplier-by-supplier capacity overlays, and the complete price-formation spreadsheet — is available through the PW Consulting report portal.
For procurement directors, operations leaders, and investors preparing for 2026, this study is designed to be a decision-grade input: not a catalogue of numbers, but a toolkit for trade-offs, risk calibration, and execution. Contact PW Consulting or visit our report page to access the full dataset, interactive dashboards, and a tailored briefing from our deicing salt practice.
For detailed analysis of this topic, please visit the official page: Worldwide Deicing Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Charging Port Door Actuators Market to Grow at 16.5% CAGR, Reach USD 994.36 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Charging Port Door Actuators Market: Strategic Imperatives for 2026 — PW Consulting Insights
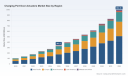
PW Consulting’s latest market study on Worldwide Charging Port Door Actuators (base year 2025, forecast 2026–2032) frames a decisive inflection point for OEMs, Tier‑1 suppliers, investors and procurement organizations. The segment has transitioned from a niche electromechanical accessory into a mission‑critical subsystem that couples vehicle safety, user experience and charging interoperability. Our bottom‑up model shows the market expanding at a 16.5% compound annual growth rate (CAGR) from 2026 onward, having grown from approximately USD 105.4 million in 2020 to USD 341.4 million in 2025, and projecting to nearly USD 1.0 billion by 2032. Those headline trajectories underscore why charging port door actuators must now be treated as strategic components in EV programs rather than commoditized items.
Worldwide Charging Port Door Actuators Market
Why this report matters for 2026 decision cycles
-
Timing and resource allocation — The 2026 product planning and supplier selection windows are when actuator choices become locked into vehicle platforms. Our report maps when technical specifications, qualification cycles and procurement milestones align across BEV and PHEV programs, enabling teams to prioritize investments that will deliver the highest risk‑adjusted returns.
Worldwide Charging Port Door Actuators Market -
Risk identification and mitigation — Rapid market growth and tighter regulatory expectations are increasing failure costs for poorly specified actuator systems. We quantify the primary failure modes, time‑to‑remediate scenarios and their commercial impact, allowing commercial and engineering leaders to weigh tradeoffs between upfront development expense and downstream warranty/liability exposure.
Worldwide Charging Port Door Actuators Market -
Partnering and M&A signal guidance — With a moderately concentrated supply base (our concentration analysis shows the top three suppliers control a significant share of addressable volume, and the top five an even larger portion), the report identifies the opportunistic zones for strategic alliances, minority investments and bolt‑on acquisitions to close capability gaps.
Market dynamics shaping 2026 strategies
-
Technology evolution — The product architecture is shifting from purely mechanical release mechanisms toward feature‑rich electromechanical actuators with embedded controls, vehicle network interfaces (LIN/CAN), and advanced HMI (gesture, capacitive touch, integrated lighting). This movement is driven as much by user experience and security requirements as by assembly and packaging advantages.
-
Regulatory pressure and safety standards — Mandates for standardized charging interfaces in major markets and stricter functional safety requirements (including ISO 26262 expectations for fault detection and redundancy) are accelerating demand and raising the bar for actuator validation. In some regions, standardization measures have correlated with double‑digit year‑over‑year sales growth for compliant subsystems.
-
Supply chain constraints — Specialized components such as rare‑earth magnets, high‑precision gearing and custom sensors have experienced intermittent shortages. Lead times for certain actuator models have extended to 12–16 weeks, making supply continuity and component strategy central topics for procurement teams.
-
Commercial shifts — Charging port door actuators are now part of broader electrification feature bundles (automatic flaps, locking, HMI, integrated sensing). Suppliers that can offer modular, platform‑agnostic modules with proven software stacks are capturing preferment in early program stages.
Competitive landscape: capabilities that matter
The competitive map is mixed: established global Tier‑1s and specialist mechatronics firms co‑exist with regional manufacturers. Leading companies distinguish themselves along three axes — system integration (actuator + flap + HMI), functional safety and serviceability, and platform scalability for high‑ and low‑volume programs.
-
Magna International (Aurora, Canada) — Offers a complete automated flap system with high‑torque actuators and integrated safety and convenience features. Their approach emphasizes turnkey integration for OEMs seeking to reduce systems‑level integration risk.
-
Motion Controls Inc (MCi, United States) — Focuses on high‑speed/high‑torque actuators with protective mechanical clutching and flexible control options (from simple to full LIN integration), leveraging patented motion control concepts for aero and charging applications.
-
NMB Technologies (MinebeaMitsumi, Japan) — Delivers smart BLDC actuator solutions with sophisticated sensor and communication features, suited to programs that require compact, programmable modules.
-
Regional specialists (China, India, Germany, etc.) — Manufacturers such as Haoyong, Padmini VNA, WITTE, Röchling, Marquardt, Johnson Electric and TE Connectivity provide a spectrum of solutions from robust mechanical modules to advanced locking actuators compatible with global charging standards. Their offerings vary by design focus: durability, cost efficiency, certification pedigree, or modularity.
Recent commercial moves underline consolidation and capability extension across the value chain: Bosch’s strategic collaboration on next‑generation actuators (March 2025), Valeo’s modular system launch (November 2024), and Continental’s contract wins on global EV programs (May 2024) signal heightened supplier competition around system reliability, sealing and platform speed to market.
What’s inside the PW Consulting report (practical deliverables)
-
Proprietary demand model — A scenario‑based market model covering 2026–2032 with sensitivity to vehicle production ramp rates, standardization events and material lead‑time shocks.
-
Commercially actionable supplier profiles — Deep‑dive assessments of leading suppliers’ technical roadmaps, qualification timelines, capacity constraints, and win/loss intelligence (kept at program level to preserve client confidentiality).
-
Technology matrix and validation playbook — Comparative evaluation of actuator topologies (electronic vs. mechanical approaches), interface options, and test protocols to meet ISO 26262 and environmental sealing expectations.
-
Procurement playbook — Sourcing strategies, contract structures, risk allocation templates, suggested lead‑time buffers and dual‑sourcing approaches to mitigate 12–16 week component lag risks.
-
Regulatory & standards tracker — A living register of charging interface standardization initiatives and functional safety updates that could materially affect specification windows.
-
Commercial impact scenarios — Quantified cost of non‑compliance, warranty exposure estimates and recommended contingency budgets for high‑risk platforms.
How to translate insights into 2026 actions: short checklist for executives
-
Lock technical baselines early — Define required actuator functions and safety margins at the concept freeze stage to minimize downstream rework and supplier change orders.
-
Prioritize modularity — Favor actuator architectures that support common mounting, shared electronics stacks and configurable HMI options to reduce platform engineering costs.
-
Secure component continuity — Negotiate staggered long‑term purchase agreements for critical subcomponents, and evaluate near‑shoring or strategic inventory positions for rare‑earth magnets and precision gears.
-
Invest in validation capacity — Allocate resources for rigorous environmental, functional safety and durability testing to shorten qualification cycles and reduce field recalls.
-
Engage in supplier co‑development — Consider early partnerships or minority investments with suppliers that offer differentiated software or mechatronic IP to accelerate feature rollout and protect time‑to‑market.
-
Monitor standards evolution — Embed a regulatory watcher in cross‑functional program teams to anticipate changes to charging interface mandates and adjust specifications before contract sign‑off.
Why PW Consulting’s report is uniquely useful
Our study combines a granular, bottom‑up demand model with supplier‑level intelligence and engineering validation practices. That blend is intended for leaders who must make capital allocation, sourcing and product roadmap choices in 2026 under uncertainty: the model quantifies upside/ downside scenarios, the supplier profiles expose capacity and capability constraints, and the playbooks translate those insights into executable procurement and engineering plans.
Next steps — a focused invitation
This release is a preview designed to inform initial strategy discussions. The full report contains the detailed segmentation tables, supplier scorecards, program‑level win/loss analysis and our complete downloadable demand model — all of which are intentionally gated to protect commercially sensitive sourcing and contract data and to enable tailored briefings. For teams preparing 2026 commitments, scheduling a briefing with our analysts will rapidly convert the macro view into program‑specific recommendations.
Contact PW Consulting to arrange a private briefing and obtain access to the complete Worldwide Charging Port Door Actuators Market report, including the interactive forecasting model and supplier heatmaps that will be indispensable for 2026 decision making.
For detailed analysis of this topic, please visit the official page: Worldwide Charging Port Door Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Turbocharger Bearing Market to Reach USD 3,075.9 Million by 2032 on a 5.25% CAGR, Led by Asia‑Pacific
By pmarketresearch, 2026-07-15
Worldwide Turbocharger Bearing Market — Strategic Preview for 2026 Decision-Making
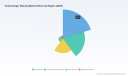
PW Consulting’s latest market research, Worldwide Turbocharger Bearing Market (Base Year: 2025; Historical: 2020–2025; Forecast: 2026–2032), provides an executive-grade roadmap for manufacturers, OEMs, suppliers, and investors preparing strategies for the pivotal year of 2026. With the global market projected to grow at a 5.25% CAGR through the forecast horizon, this briefing highlights the structural dynamics, competitive levers, and risk vectors that should shape boardroom decisions — while reserving the detailed segment-level matrices for subscribers of the full report.
Worldwide Turbocharger Bearing Market
Why 2026 is a Strategic Inflection Point
The turbocharger bearing market is moving beyond incremental volume growth to a phase defined by technology migration, regulatory acceleration, and concentrated supplier power. Our model — calibrated on historical performance through 2025 and projecting to 2032 — shows steady, compounding expansion of the overall market (reported in USD Million), underpinned by product innovation and tightening emissions regimes. For 2026 specifically, industry participants will face a unique conjunction of opportunities and constraints: increased demand for low-friction and high-temperature bearing solutions, volatile raw material inputs, and competitive responses from both legacy bearing giants and niche specialist players.
Worldwide Turbocharger Bearing Market
Macroeconomic and Regulatory Drivers
-
Regulatory push: Stringent emission standards in major markets (for example, new Euro 7 provisions and tightened heavy-duty NOx limits) are accelerating adoption of more efficient turbocharging systems. Bearings that enable higher rotational speeds, lower frictional losses, and longer thermal endurance will be central to compliance strategies and powertrain downsizing efforts.
Worldwide Turbocharger Bearing Market -
Powertrain transition: Electrified turbocharging concepts and 48V mild-hybrid architectures are increasing technical demands on bearing solutions — especially in terms of transient response and electrical compatibility — prompting OEMs to specify advanced foil and hybrid ceramic bearings.
-
Raw material pressure: Recent commodity movements — including higher alloy-steel prices and notable increases in copper content costs for bronze bearings — are compressing margins for producers reliant on traditional metallurgy, and are raising the importance of supply chain hedging and material substitution strategies.
-
Trade and geopolitics: Tariff regimes and trade frictions have altered sourcing economics and manufacturing footprints. Companies that can demonstrate resilient regional supply or localized value capture will be advantaged as OEMs seek to de-risk procurement.
Market Size and Growth Trajectory (Overview)
Our topline market model — expressed in USD Million — documents the sector’s progression through 2025 and projects steady growth throughout the 2026–2032 forecast window at a 5.25% CAGR. The trajectory reflects both organic replacement demand and incremental uptake in advanced bearing technologies required by next-generation turbocharger platforms. This macro view is indispensable for sizing investment cases, capital expenditure schedules, and break-even analyses for new product lines.
Competitive Landscape — Key Players and Strategic Positioning
The turbocharger bearing market exhibits a balanced mix of diversified global incumbents and specialized technology firms. Market concentration metrics indicate that leading firms collectively account for a significant share of industry revenue, creating conditions where scale, technology IP, and OEM relationships matter. These market concentration dynamics are important inputs when evaluating strategic moves such as capacity expansion, pricing strategies, or targeted M&A.
-
Schaeffler Group (Herzogenaurach, Germany) — A leading supplier with deep capabilities in journal bearings and foil air bearings for automotive and commercial turbochargers. Schaeffler’s strong OEM ties and recent showcases of next-generation foil bearings position it as a pace-setter for electrically assisted turbo solutions.
-
SKF AB (Gothenburg, Sweden) — Focused on hybrid ceramic and air-foil technologies optimized for high-speed operation. SKF’s investments into extended-durability turbocharger bearings aim to capture growth in heavy-duty and high-performance passenger applications.
-
NTN Corporation (Nara, Japan) — A broad-based bearing manufacturer producing roller and ball bearings engineered for both passenger car and heavy-duty turbocharger requirements. NTN’s product breadth enables flexible quoting across OEM programs.
-
NSK Ltd. (Tokyo, Japan) — Known for high-temperature angular contact ball bearings designed for demanding turbocharger environments; NSK’s focus on materials and lubrication developments underpins performance claims for elevated thermal cycles.
-
The Timken Company (North Canton, Ohio, USA) — Offers tapered roller and super-precision bearings largely aimed at industrial and heavy-duty turbo applications, with an emphasis on durability in power generation and marine segments.
-
RBC Bearings Incorporated (Plainview, New York, USA) — A specialist in foil air and thrust bearings with cross‑sector relevance, including aerospace — a differentiator for customers demanding extreme performance and longevity.
-
JTEKT Corporation (Osaka, Japan) — Produces Koyo-brand needle roller and ball bearings adapted to turbocharger constraints; JTEKT’s global manufacturing footprint supports competitive lead times for major OEMs.
-
Waukesha Bearings Corporation (Waukesha, Wisconsin, USA) — Supplier of hydrodynamic journal and tilt-pad bearings for power generation and marine turbochargers, complementing industrial OEM supply chains.
Recent industry moves — product launches, trade-show reveals, and targeted exhibitions — underscore both incremental innovation and strategic signaling. Examples include advanced foil-bearing prototypes showcased at major mobility shows and hybrid-bearing product introductions for heavy-duty engines. These events provide insight into near-term commercialization timetables and customer validation cycles.
Structural Implications for 2026 Strategy
-
R&D Priorities: With regulatory windows compressing and performance expectations rising, R&D must prioritize low-friction surfaces, high-temperature ceramics, and lubrication systems tuned for transient turbocharger regimes. Firms should allocate resources to modular bearing platforms that can be adapted across powertrain variants.
-
Supply Chain & Sourcing: Given recent material cost shocks and geopolitically driven tariff risks, companies must re-evaluate sourcing strategies. Options include multi-sourcing critical alloys, strategic long-term contracts, and material-substitution pilots. Near‑shoring or regional manufacturing can be a defensive move to preserve OEM access.
-
Commercial & Pricing: Margin pressure from raw material inflation will necessitate more sophisticated price escalation clauses, value-based pricing for premium bearing technologies, and bundled value propositions (e.g., warranties, predictive maintenance offerings) to protect margins.
-
Partnerships & Open Innovation: Fast followers and smaller innovators (e.g., foil-bearing specialists) are attractive partners for joint development or licensing. OEM co-development agreements can accelerate adoption while sharing technical risk.
-
M&A & Capacity Rationalization: Market concentration trends create opportunities for bolt-on acquisitions that provide technology differentiation or regional scale. Conversely, incumbents should evaluate capacity reconfiguration to prioritize high-margin advanced bearing families over commodity lines.
-
Aftermarket & Service Models: As turbocharger systems become more sophisticated, aftermarket service and predictive maintenance will gain strategic importance. Businesses that combine bearings with sensing, analytics, and lifecycle services will unlock recurring revenue streams.
Risk Assessment — What to Monitor in 2026
-
Commodity volatility: Continued upward pressure on steel and copper pricing can erode margins; hedging and alloy innovation are defensive priorities.
-
Regulatory timing: Delays or acceleration in regional emissions rollouts can materially affect adoption timelines for premium bearing technologies.
-
Competitive responses: Rapid product introductions by market leaders can shorten window-of-opportunity for late entrants; a fast-to-market strategy combined with clear OEM proof points is critical.
-
Supply chain disruptions: Logistics shocks and trade policy shifts remain systemic risks; contingency planning and supplier auditing will reduce exposure.
What the Full Report Delivers (Practical Toolkit)
PW Consulting’s full report contains the practical tools executives need to operationalize the insights summarized here, including:
-
Proprietary market model with annual revenue estimates (USD Million) through 2032 and scenario-based sensitivity analysis for commodity and regulatory shocks.
-
Demand-driver matrices linking regulatory milestones, vehicle powertrain mix, and bearing technology uptake timelines.
-
Supplier heatmaps and capability scorecards that assess technology, scale, quality, and OEM access across the major competitive players.
-
Commercial playbooks for pricing, contracting, and service offers suitable for OEM and aftermarket channels.
-
Acquisition screening templates and synergy calculators for inorganic growth planning.
To preserve the strategic value of the report for clients, this preview intentionally omits the detailed segment-level splits and discrete revenue-by-region/application tables. Subscribers receive the full segmentation, granular unit economics, and raw-data workbooks required for capital allocation and program-level negotiations.
Recommended Next Steps for 2026 Planning
-
Initiate cross-functional workshops (R&D, procurement, commercial) to stress-test product roadmaps against the regulatory timelines embedded in our forecast.
-
Secure multi-year material contracts or strategic alliances to mitigate input-cost volatility without sacrificing flexibility for material innovation.
-
Prioritize pilot programs with OEMs for advanced bearing technologies (foil, hybrid ceramic) to earn design wins that will crystallize volume post-2026.
-
Evaluate targeted M&A opportunities that fill capability gaps or create regional supply resilience, using our acquisition screening templates as a starting point.
-
Develop aftermarket service offers that leverage sensorization and predictive analytics to create recurring revenue streams and deepen OEM/customer relationships.
Closing Perspective
As turbocharger systems evolve, the bearing sub-market will shift from a largely engineered commodity to a strategic differentiator in powertrain development. PW Consulting’s Worldwide Turbocharger Bearing Market report equips leaders with the quantitative backbone and qualitative context necessary to make disciplined 2026 decisions — from R&D prioritization and supply-chain restructuring to pricing and M&A. For executives who need the full dataset, segment-level forecasts, and executable templates, the complete report and interactive model are available on our website.
Contact PW Consulting to request the full report and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Military Off‑road Vehicles Market Reaches USD 18,450 Million in 2025, Poised for 5.12% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Military Off-road Vehicles Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence, Worldwide Military Off-road Vehicles Market (Base year: 2025; Forecast: 2026–2032), synthesizes operational, procurement and industrial insights that defense program managers, prime contractors, investors and sovereign acquisition authorities need to shape 2026 strategies. This briefing highlights the report’s strategic value without disclosing the granular segmentation that underpins our proprietary models — a preview designed to demonstrate analytical depth while directing readers to the source for full datasets and tactical recommendations.
Worldwide Military Off-road Vehicles Market
Market snapshot: The macro frame that should guide 2026 choices
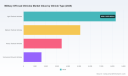
After steady expansion through the early 2020s, the global military off-road vehicles market reached USD 18,450 Million in 2025. Our forecast shows continued expansion over the coming decade at a compound annual growth rate (CAGR) of 5.12%, taking the global market to roughly USD 26.17 Billion by 2032. Market concentration is moderate: the top three players account for about 42.2% of revenue, and the top five account for roughly 58.4%, leaving meaningful space for mid-tier suppliers and new entrants with differentiated propositions.
Worldwide Military Off-road Vehicles Market
For executives planning 2026 budgets, these numbers do three things: they validate sustained demand for platform modernization and fleet sustainment; they quantify scale sufficient to justify investments in autonomous and hybrid powertrain prototypes; and they clarify that differentiated innovation — rather than pure scale alone — will unlock share gains.
Worldwide Military Off-road Vehicles Market
Why this report matters in 2026: five decision-use cases
-
Procurement prioritization: Our scenario-based demand modeling translates macro growth into prioritized capability gaps that defense acquisition offices will face in 2026 — enabling smarter RFP timing, lot-sizing and risk hedging for long-lead subsystems.
-
Platform roadmaps: For primes and Tier‑1 suppliers, the analysis illuminates where investments in modularity, protection packages, and powertrain electrification (including hybrid demonstrators) will produce the highest return over a seven-year horizon.
-
Supply-chain resilience: Given recent raw-material volatility and component fragility, the report provides supplier risk heat maps and alternative sourcing strategies to protect production timelines and margins.
-
M&A and partnership screening: With market concentration at current levels, the report’s competitive benchmarking and technology-pairing matrices help investors and acquirers identify bolt-on targets that materially improve capability or geographic access without triggering anti-trust diseconomies.
-
Operational adoption of autonomy and electrification: We map maturity, cost trajectories and deployment windows so program offices can schedule prototyping, integration trials and logistics preparations in 2026–2028 with realistic risk buffers.
Key growth drivers and structural headwinds
-
Operational doctrine and force modernization: Increased emphasis on dispersed operations and expeditionary logistics drives demand for agile, high-mobility platforms and modular variants that can be adapted in the field.
-
Technology adoption curves: Autonomous navigation and hybrid-electric powertrains are moving from demonstrator to early operational tests. DARPA’s recent RACER autonomous platform trials (January 2026) and service-level prototype selections indicate a narrowing gap between lab validation and tactical deployment.
-
Raw-material and component volatility: Armor steel and power-electronics supply fragility, combined with a documented 17% increase in armor fabrication costs between 2022 and 2023, are reshaping supplier selection criteria. Buyers will prioritize visibility into long-lead inputs and contractual protections for commodity swings.
-
Regulatory posture: Military tactical off-road trucks continue to benefit from exemptions that decouple them from civilian emissions regimes, enabling platform optimization for mobility and fuel compatibility (e.g., JP-8). While this reduces near-term compliance cost, it also delays emissions-driven powertrain transitions and creates divergence between military and commercial supply bases.
-
Funding variability and geopolitical shocks: Procurement rhythms are sensitive to defense budget cycles and crisis-driven accelerations. Forecasts therefore incorporate scenario branches that reflect surge buys and extended sustainment spending.
Competitive landscape — what the report reveals (and what it withholds)
Our benchmarking examines capability portfolios, industrial capacity, R&D trajectories, and most-recent program outcomes across established OEMs and rising suppliers. Several strategic observations emerge:
-
Market leaders leverage integrated value propositions. Firms with strong positions in tactical wheeled vehicles and armored platforms combine mobility innovations (advanced suspensions, modular drivetrains) with tested protection suites — enabling them to capture higher-margin systems and longer-term sustainment work.
-
Mid-tier players are exploiting niche specialization. Companies focused on logistics trucks, MRAP variants, or hybrid demonstrators are successfully targeting sovereign requirements and aftermarket modernization work where primes are less nimble.
-
Autonomy and electrification are the strategic differentiators for 2026. Firms demonstrating credible integration pathways — from demonstrators to fielded prototypes — will be favored in new procurement waves. Recent field demonstrations and contract awards are tangible signals: for example, teams led by major OEMs have been publicly showcasing light vehicle lineups in theatrical demonstrations, while defense relationships are generating prototype integrations for infantry mobility systems.
-
Industrial risk remains a gating factor. Even top suppliers face production schedule risks due to component supply constraints and steel-price volatility; program managers should weigh supplier financial resilience and multi-sourcing strategies in RFP evaluations.
For readers who track specific vendors, our full report includes side-by-side capability maps, supplier attractiveness scores and a wins/losses dossier for recent procurements. The preview deliberately omits the granular scoring and segment revenue splits to preserve the actionable value that subscribers and clients receive.
Representative company positioning (high level)
-
Oshkosh Defense — Strengths: Proven mobility systems and fielded combat platforms. Strategic posture: leveraging TAK-4i and established MRAP/JLTV lineage to defend and expand program wins.
-
AM General — Strengths: Heritage in light tactical mobility and global fleet sustainment. Strategic posture: emphasizing modular tactical kits and high-mobility derivatives to stay relevant in upgrade markets.
-
General Dynamics Land Systems — Strengths: Integrated armored systems and demonstrators in hybrid propulsion. Strategic posture: combining survivability and systems integration to compete in high-end segments.
-
BAE Systems and Rheinmetall — Strengths: Deep armored vehicle portfolios and large-scale program experience. Strategic posture: pursuing modularity and scalable protection suites for multi-role demands.
-
GM Defense, Navistar, Iveco, Mack Defense, Arquus, Tata Motors, Hanwha — Strengths: niche capabilities, regional presence, and logistics/utility focus. Strategic posture: targeting sovereign production, logistics modernization programs and emerging autonomy trials.
Recent events underline these dynamics: high-profile demonstrations and trials (e.g., late-2025 light-vehicle demos and DARPA autonomous navigation tests in early 2026) are accelerating the transition from concept to prototype. Simultaneously, service-level procurements to integrate autonomous mobility into infantry vehicles are creating short-term demand spikes that favor agile integrators.
What’s inside the full PW Consulting report (actionable deliverables)
-
Executive decision playbook: procurement timing, lot-sizing heuristics and contractual levers for managing commodity risk.
-
Risk-adjusted demand model: scenarios tied to geopolitical stressors and budget slippage, with sensitivity to raw-material price shocks.
-
Technology adoption roadmap: tested timelines for autonomy, hybridization, and materials innovation, including integration costs and maintenance implications.
-
Supply-chain remediation templates: dual-sourcing playbooks, long-lead component visibility frameworks, and mitigation contracts for armor steel and power electronics.
-
Competitive benchmarking and M&A candidate shortlists: quantified attractiveness scores, capability gaps and go/no-go acquisition thresholds.
-
Commercials and pricing playbook: TCO models for life-cycle cost comparisons, aftermarket revenue capture and sustainment contracting strategies.
Practical strategic recommendations for 2026
-
Prioritize modularity to future-proof procurement. Contracts should require open architectures and upgrade rails to permit rapid insertion of autonomy, sensors and electronic protection suites.
-
Lock in long-lead components now. Given supply fragility for armor steel and power electronics, secure forward contracts and validate secondary suppliers to reduce schedule risk.
-
Invest selectively in autonomy pilots. Allocate program dollars to realistic tech-readiness demonstrations aligned with fielded operational use cases rather than technology vanity projects.
-
Use hybrid contracting models. Balance fixed-price lots for proven platforms with incentive-based awards for innovation to accelerate adoption while containing program risk.
-
Monitor regulatory signals but don’t overaccelerate decarbonization solely on civilian standards. Military exemptions currently permit fuel and engine configurations optimized for mobility; transition planning should be deliberate and mission-driven.
Next steps — how to use this briefing
This preview demonstrates the strategic framing and analytical rigor in PW Consulting’s full Worldwide Military Off-road Vehicles Market report. If you are a program director, prime contractor, investor, or sovereign purchaser preparing decisions in 2026, the full report will provide the granular scenario outputs, supplier scorecards and procurement playbooks you need to execute with confidence.
To access the complete market model, segmentation breakdowns, company dossiers and actionable templates — including downloadable spreadsheets and a short advisory engagement option — please visit the PW Consulting report page. Our subscription and bespoke advisory offerings can be tailored to align the intelligence in this report with your procurement calendars, R&D roadmaps and M&A timelines.
PW Consulting — translating market complexity into decisive strategy for defense leaders.
For detailed analysis of this topic, please visit the official page: Worldwide Military Off-road Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Alternate Light Sources Market Forecast to Expand at a 5.72% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Alternate Light Sources Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As organizations recalibrate forensic, medical diagnostics, and industrial inspection capabilities for the mid‑2020s, Alternate Light Sources (ALS) have moved from niche tools to mission‑critical instruments. PW Consulting’s forthcoming Worldwide Alternate Light Sources Market report — base year 2025, historical coverage 2020–2025, and forecast horizon 2026–2032 — frames the market’s transition in operational, regulatory, and procurement terms. This preview summarizes the report’s strategic value for executives, procurement leads, and product teams preparing 2026 strategies while intentionally omitting granular segmentation tables; detailed breakdowns and vendor scorecards are available in the full report.
Worldwide Alternate Light Sources Market
Market Trajectory and What It Means for 2026 Decisions
The ALS market has demonstrated consistent expansion through the first half of the decade, rising from the low hundreds of millions of USD in 2020 to an estimated USD 470.83 Million in 2025 (revenue unit: Million USD). Our consolidated forecast projects the market to exceed USD 507 Million in 2026 and to continue growing at a compound annual growth rate (CAGR) of approximately 5.72% through 2032, reaching just under USD 695 Million by the end of the forecast horizon.
Worldwide Alternate Light Sources Market
For decision‑makers, three immediate implications follow:
Worldwide Alternate Light Sources Market
- Strategic procurement should prioritize lifecycle value over purchase price. With the market growing steadily, vendors are differentiating via warranties, modular optics, field serviceability, and data integration rather than purely on unit cost.
- R&D and product managers must orient roadmaps to interoperability and safety compliance (e.g., wavelength-specific eye protection and SWGDE photography practices). Early investment in these features reduces total cost of ownership and shortens procurement cycles for law enforcement and clinical buyers.
- Channel and aftermarket strategies will be decisive. As unit volumes grow, service contracts, consumables (filters, batteries), and training will drive a growing share of lifetime revenue — an opportunity often overlooked in initial procurement evaluations.
Competitive Structure and Supplier Dynamics
The ALS landscape displays moderate concentration: the top three vendors collectively capture a meaningful share of the market while the top five extend that reach further. This concentration suggests a market where established brands exert pricing and specification influence, but where mid‑market and specialized players continue to find niche opportunities.
Key vendor archetypes identified in our analysis include:
- Heritage forensic specialists who focus on laboratory‑grade multi‑wavelength systems and evidence screening workflows.
- Ruggedized field suppliers offering cordless, durable kits optimized for crime scene deployment.
- Cost‑effective handheld manufacturers that emphasize simplicity and ergonomics for rapid field adoption.
Representative companies profiled in the report include:
- Foster + Freeman (United Kingdom) — Known for high‑intensity LED forensic light sources, multi‑wavelength single‑unit systems, and next‑generation lab screening units designed to integrate into forensic workflows. ( https://fosterfreeman.com)
- Labino AB (Vallentuna, Sweden) — Focused on waterproof, field‑ready LED ALS kits that prioritize straightforward operation and durability; recently refreshed product literature to support procurement cycles. ( https://labino.com)
- Sirchie (United States) — Supplies a broad portfolio for law enforcement, including shortwave UV systems and tactical ALS kits, with clear safety guidance for hazardous wavelengths. ( https://www.sirchie.com)
- HORIBA Scientific (SPEX Forensics) (United States) — Offers laboratory and field LED systems aimed at latent print and body fluid visualization, with a strong emphasis on imaging compatibility. ( https://www.horiba.com)
- FoxFury (United States) — Specializes in rugged cordless forensic lighting and ALS lasers optimized for first responders and outdoor scenes. ( https://www.foxfury.com)
- Lynn Peavey Company and UltraLite ALS (United States) — Distributors and specialized portable providers emphasizing turnkey kits for crime scene processing and evidence documentation. ( https://lynnpeavey.com)
In the full report we publish a comparative vendor scorecard that evaluates product portfolios across technical depth, field reliability, serviceability, pricing strategy, and channel reach. The scorecard empowers buyers to move beyond marketing claims to procurement‑ready shortlists.
Regulatory and Standards Context — Non‑Negotiable in 2026
Standards and regulation shape both demand and product design. Our Dynamics section synthesizes guidance from authoritative sources and its practical implications for buyers and vendors alike:
- NIST’s formal definitions clarify ALS scope and underpin procurement specifications used by public agencies.
- The U.S. Department of Homeland Security’s Authorized Equipment List (AEL) includes portable forensic light kits under a specific category, influencing eligibility for federal grants and state procurement programs.
- SWGDE guidelines set procedural requirements for luminescence documentation in low‑light crime scene photography — affecting tripod compatibility, exposure modes, and wavelength‑specific eye protection included with vendor offerings.
- Operational safety guidance, including manufacturer directives on shortwave UV exposure, are essential for compliance; failure to adhere increases organizational risk and liability.
For vendors, alignment with these standards is not optional — it materially impacts market access and the sales cycle length for public sector buyers. For buyers, specifying standards alignment in RFIs and RFPs removes ambiguity and shortens evaluation cycles.
Technological and Application Trends Shaping 2026
Several technology and use‑case trends are converging to reshape buying criteria:
- LED platform dominance: LED architectures continue to lead in energy efficiency and lifespan, prompting vendors to build modular optics rather than replace entire units.
- Integration of multispectral imaging with ALS: Buyers increasingly demand compatibility between light sources and imaging systems for documentation and AI‑assisted evidence analysis.
- Ruggedness and portability: Field deployments by first responders demand compact, waterproof, and battery‑resilient solutions, fueling growth in cordless ALS designs.
- Service and training as revenue levers: Vendors that couple product sales with certified training and rapid field service capture greater wallet share across the equipment lifecycle.
Our report explores each trend in depth and quantifies the operational impact on different buyer personas — from municipal forensic departments to private industrial inspection teams.
What the Report Contains — Practical Deliverables for 2026 Planning
The full PW Consulting report is built for direct application in strategy and procurement processes. Core deliverables include:
- Market model and forecasts (2026–2032) with scenario analysis and sensitivity tests tied to adoption rates and regulatory shifts.
- Go‑to‑market playbooks for vendors targeting public safety, clinical diagnostics, and industrial inspection channels.
- Procurement templates and RFP language mapped to standards (NIST, DHS AEL, SWGDE) to shorten buying cycles and reduce supplier ambiguity.
- Vendor scorecards and quadrant placements based on capability, reliability, service, and pricing architecture.
- Channel economics models and aftermarket income projections to support pricing and bundling strategies.
- Risk register and mitigation blueprint covering safety exposures (e.g., shortwave UV), supply chain dependencies, and intellectual property considerations.
- Buyers’ ROI calculator and TCO checklist tailored to field vs. laboratory deployments.
These practical assets are designed to be plug‑and‑play for capital planning, competitive benchmarking, and vendor selection in 2026.
Recent Market Signals and What They Imply
Company‑level activity signals continued investment around product refresh and field readiness. Notable examples include a January 2025 product catalog refresh from a prominent Swedish kit maker and an April 2025 launch/refresh of next‑generation evidence screening units by a leading UK forensic supplier. These moves confirm vendor focus on modular LED technologies, improved ergonomics, and clearer specification documentation — all responses to buyer demand for simplicity, durability, and standards‑aligned features.
Additionally, the market hosts more than a dozen manufacturers and a wide pricing spectrum, indicating room for both premium innovation and low‑cost penetration strategies. More than 50 product SKUs across handheld, laboratory, and ruggedized form factors create choice complexity that often slows procurement unless buyers adopt structured evaluation frameworks.
How to Use This Preview
If you are a procurement head, use this preview to reframe 2026 budgets toward total cost of ownership, compliance alignment, and modularity. If you are a product leader or investor, map R&D near‑term roadmaps to imaging interoperability and serviceability. For vendors navigating competitive dynamics, prioritize channel enablement and certified training to capture aftermarket value.
To maintain the “trailer” principle: this article intentionally highlights strategic takeaways and high‑level market metrics while withholding detailed regional, type, and application splits. PW Consulting’s full report contains comprehensive segment tables, primary research attachments, vendor financials, and downloadable datasets to support your procurement specifications and strategic planning.
Next Steps
- Access the full report for segmented market analytics, downloadable models, and the vendor scorecard that operational teams use to build 2026 RFPs.
- Request a briefing or custom workshop with PW Consulting to translate report findings into a six‑month procurement roadmap or a product roadmap sprint.
- Subscribe to our executive summary newsletter for fortnightly updates on ALS technology, standards developments, and vendor movements.
PW Consulting’s Worldwide Alternate Light Sources Market report provides the quantitative backbone and the operational playbooks that organizations need to make high‑confidence decisions in 2026. For the full dataset, vendor scorecards, and actionable procurement templates, visit our report page or contact our industry advisory desk.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com