

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Agricultural Nanotechnology Market Set to Expand at a 14.03% CAGR, Driving Transformative Growth Through 2032

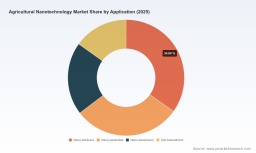
Worldwide Agricultural Nanotechnology Market — Strategic Imperatives for 2026
PW Consulting’s latest market research, "Worldwide Agricultural Nanotechnology Market," provides an evidence-based playbook for executives, investors, and policy teams preparing to act in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report synthesizes commercial, technical, and regulatory intelligence into a set of actionable recommendations. The market is on a multi-year expansion trajectory—growing from an assessed global value in 2020 to an estimated USD 325.5 Million (base year 2025), and projected to exceed USD 800 Million by 2032—reflecting a compound annual growth rate of 14.03% across the forecast period. This growth profile elevates agricultural nanotechnology from a niche research theme to a strategic growth vector for agri-inputs, precision farming, and seed and soil services businesses.
Worldwide Agricultural Nanotechnology Market
Why this matters for 2026 decision cycles
- Market timing and scale: The trajectory through 2026 signals that early movers who translate laboratory advantages to field-validated products stand to capture disproportionate value. The market’s expansion is broad-based—driven by technological maturation, farmer demand for efficiency, and rising regulatory and retailer pressure on sustainability metrics.
- Portfolio repositioning: Established agribusinesses and input manufacturers must decide in 2026 whether to treat nanotechnology as a core platform (integrated into fertilizer, crop protection and digital offerings) or as a complement to existing lines (licensed formulations, co-branded pilots).
- Innovation-to-commercialization cadence: The gap between R&D and scalable manufacturing remains the rate-limiting step. Decisions on capital allocation for pilot plants, contract manufacturing partners, and field trials will determine commercial viability by late-deployment windows (2027–2029).
What the report delivers — practical, decision-grade content
- Quantitative market sizing and validated growth scenarios for 2026–2032, presented with sensitivity analyses and upside/downside cases tied to regulatory outcomes and raw material availability.
- Go-to-market frameworks for product classes (from fertilizer and pesticide formulations to biosensors and soil amendments), including channel strategies, farmer adoption levers, and margin modeling.
- Supply chain diagnostics that map critical inputs, potential bottlenecks, and low-cost feedstock pathways—including opportunities to convert agricultural waste biomass into nanomaterials.
- Regulatory and safety roadmaps with recommended engagement strategies for 2026: tiered testing protocols, environmental monitoring frameworks, and stakeholder communication templates to mitigate toxicity and soil-ecosystem concerns.
- M&A and partnership playbooks: target archetypes, valuation pruning principles, and integration checklists for acquiring IP, scaling manufacturing, or accessing distribution networks.
- Commercial pilot blueprints and KPIs—how to structure replicated field trials, what yield and input-efficiency metrics to collect, and the economics that will convince commercial partners and farmers.
Market dynamics and structural drivers
The convergence of several macro drivers underpins the market’s 14.03% CAGR through the forecast: continued pressure to reduce input volumes while sustaining yields; advances in nano-enabled formulations that improve active ingredient delivery and retention; and the integration of nanotechnology with precision agriculture platforms for real-time soil and crop feedback. That said, industry adoption is uneven. Cost differentials versus conventional inputs remain material in early commercialization, and environmental safety questions—especially around nanoparticle fate in soil ecosystems—create regulatory uncertainty that influences time-to-market.
Worldwide Agricultural Nanotechnology Market
Competition and strategic positioning — who to watch
Competitive structure is moderately concentrated: the top three suppliers do not dominate the market, and the top five account for roughly 43% of identifiable revenue—leaving meaningful space for innovative challengers and regional specialists. The competitive landscape is diverse: multinational chemical and seed companies are accelerating portfolio integration, established agri-input specialists and niche technology providers are commercializing focused solutions, and R&D-centric firms are pushing novel material science breakthroughs.
Worldwide Agricultural Nanotechnology Market
- Aqua-Yield Operations, LLC (Nano-Yield) — U.S.-based Nano-Yield has emerged as a notable commercial example of nano-fertilizer deployment. Its trajectory demonstrates how focused product-market fit and measurable agronomic benefits (nutrient use efficiency gains, lower application rates) can translate into rapid private-company growth and visibility among enterprise buyers.
- Indogulf BioAg LLC — Operating across U.S. and India markets, Indogulf is an example of hybrid commercialization: combining locally-relevant formulations with international distribution know-how to accelerate adoption in diverse cropping systems.
- Major multinationals (e.g., BASF SE, Syngenta AG) — These incumbents are accelerating development and expanding portfolios to include nano-enabled crop protection and seed treatment formulations. Their initiatives reduce commercial risk for the sector by investing in industrial-scale R&D, but they also raise competitive stakes for mid-sized specialists.
- India-based innovators and material suppliers — Several regionally focused players and research centers are advancing low-cost production routes and localized formulations—key to achieving price parity and farmer acceptability in high-volume commodity cropping systems.
- Materials and nanotechnology specialists — Suppliers of core nanomaterials and molecular-scale technologies are important upstream partners. Their IP and production capacities are strategic levers for both incumbents and new entrants.
Recent industry developments underscore these dynamics: incumbent chemical firms have accelerated nano-enabled product pipelines, high-growth private firms are gaining market recognition, and independent testing bodies have spotlighted certain nanoparticle types for next-generation biostimulant work. For competitive strategists, the takeaway is clear: access to dependable production, field-validated agronomy, and regulatory-compliant safety data are competitive differentiators in 2026.
Risk matrix: regulatory, environmental, and commercial
- Regulatory uncertainty: Concerns around nanoparticle toxicity and long-term soil impacts remain central. Companies should assume staggered regulatory trajectories across markets and plan for rigorous ecotoxicology programs.
- Raw material and cost risk: Production often starts with higher unit costs versus conventional chemistries. However, feedstock innovations—such as transforming agricultural waste biomass into nanomaterials—offer a pathway to lower-cost, lower-GHG production that also strengthens circular-economy credentials.
- Adoption risk: Farmer willingness to pay small premiums depends on clear, replicable yield and input-efficiency evidence. Pilots must demonstrate short payback windows and reduced operational complexity.
- Reputational risk: Poorly-communicated safety data or insufficient environmental monitoring can delay commercialization and invite restrictive policy responses.
2026 playbook — what market leaders will do this year
- De-risk field performance with layered trials: Combine controlled-environment studies, multi-site pilots, and independent third-party validations to accelerate farm-level trust. Build data dashboards to quantify inputs displaced, yield delta, and lifecycle GHG impacts.
- Secure manufacturing optionality: Invest in modular pilot plants or secure CMO arrangements to preserve capital and allow capacity scaling as demand crystallizes. Prioritize flexible lines that can process multiple nano-formulations.
- Lock in feedstock innovation: Explore partnerships with biomass processing firms and waste-management operators to develop low-cost nanomaterial feedstocks. This both reduces unit costs and supports sustainability claims.
- Invest in regulatory evidence early: Fund tiered environmental and toxicity studies in parallel with agronomic pilots to compress approval timelines. Proactively engage with regulators and standard setters to shape practicable frameworks.
- Embed digital assurance: Integrate nano-formulations with precision ag platforms and nano-sensor telemetry to create verifiable performance stories. Data-enabled offerings accelerate value capture through service bundles (e.g., subscription-based input + monitoring).
- Consider M&A and alliance pathways: Use bolt-on acquisitions to acquire manufacturing know-how or regional distribution; pursue co-development with incumbents to access scale and trusted market channels while retaining nimble innovation approaches.
How PW Consulting’s report supports your 2026 decisions
Our research distills empirical market sizing, supplier benchmarking, risk-adjusted scenario planning, and executable commercialization templates into a single deliverable designed for corporate strategy teams, R&D portfolio managers, and investment committees. The report provides the diagnostic and prescriptive layers required to set budgets, prioritize projects, or structure deals in 2026 without exposing the granular subsegment tables you’ll need to validate partner negotiations and M&A valuations. For clients, we also offer customized workshops to translate insights into board-ready investment plans and regulatory engagement calendars.
Conclusion — a narrow window to shape market outcomes
The agricultural nanotechnology sector stands at an inflection point. The market’s projected multi-year growth and the recent acceleration in product development by both nimble specialists and large incumbents create a narrow window in 2026 for strategic moves that capture long-term value. Executives who pair rigorous field evidence, manufacturing flexibility, regulatory foresight, and digital value capture will convert scientific promise into commercial scale. PW Consulting’s full report contains the granular segmentation, regional forecasts, and company-level scorecards needed to operationalize these recommendations.
For the complete dataset, proprietary subsegment analysis, and a tailored advisory session to align these insights with your 2026 objectives, please visit our report page and request an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Nanotechnology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com