

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Military Off‑road Vehicles Market Reaches USD 18,450 Million in 2025, Poised for 5.12% CAGR During 2026–2032

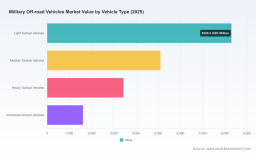
Worldwide Military Off-road Vehicles Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence, Worldwide Military Off-road Vehicles Market (Base year: 2025; Forecast: 2026–2032), synthesizes operational, procurement and industrial insights that defense program managers, prime contractors, investors and sovereign acquisition authorities need to shape 2026 strategies. This briefing highlights the report’s strategic value without disclosing the granular segmentation that underpins our proprietary models — a preview designed to demonstrate analytical depth while directing readers to the source for full datasets and tactical recommendations.
Worldwide Military Off-road Vehicles Market
Market snapshot: The macro frame that should guide 2026 choices
After steady expansion through the early 2020s, the global military off-road vehicles market reached USD 18,450 Million in 2025. Our forecast shows continued expansion over the coming decade at a compound annual growth rate (CAGR) of 5.12%, taking the global market to roughly USD 26.17 Billion by 2032. Market concentration is moderate: the top three players account for about 42.2% of revenue, and the top five account for roughly 58.4%, leaving meaningful space for mid-tier suppliers and new entrants with differentiated propositions.
Worldwide Military Off-road Vehicles Market
For executives planning 2026 budgets, these numbers do three things: they validate sustained demand for platform modernization and fleet sustainment; they quantify scale sufficient to justify investments in autonomous and hybrid powertrain prototypes; and they clarify that differentiated innovation — rather than pure scale alone — will unlock share gains.
Worldwide Military Off-road Vehicles Market
Why this report matters in 2026: five decision-use cases
-
Procurement prioritization: Our scenario-based demand modeling translates macro growth into prioritized capability gaps that defense acquisition offices will face in 2026 — enabling smarter RFP timing, lot-sizing and risk hedging for long-lead subsystems.
-
Platform roadmaps: For primes and Tier‑1 suppliers, the analysis illuminates where investments in modularity, protection packages, and powertrain electrification (including hybrid demonstrators) will produce the highest return over a seven-year horizon.
-
Supply-chain resilience: Given recent raw-material volatility and component fragility, the report provides supplier risk heat maps and alternative sourcing strategies to protect production timelines and margins.
-
M&A and partnership screening: With market concentration at current levels, the report’s competitive benchmarking and technology-pairing matrices help investors and acquirers identify bolt-on targets that materially improve capability or geographic access without triggering anti-trust diseconomies.
-
Operational adoption of autonomy and electrification: We map maturity, cost trajectories and deployment windows so program offices can schedule prototyping, integration trials and logistics preparations in 2026–2028 with realistic risk buffers.
Key growth drivers and structural headwinds
-
Operational doctrine and force modernization: Increased emphasis on dispersed operations and expeditionary logistics drives demand for agile, high-mobility platforms and modular variants that can be adapted in the field.
-
Technology adoption curves: Autonomous navigation and hybrid-electric powertrains are moving from demonstrator to early operational tests. DARPA’s recent RACER autonomous platform trials (January 2026) and service-level prototype selections indicate a narrowing gap between lab validation and tactical deployment.
-
Raw-material and component volatility: Armor steel and power-electronics supply fragility, combined with a documented 17% increase in armor fabrication costs between 2022 and 2023, are reshaping supplier selection criteria. Buyers will prioritize visibility into long-lead inputs and contractual protections for commodity swings.
-
Regulatory posture: Military tactical off-road trucks continue to benefit from exemptions that decouple them from civilian emissions regimes, enabling platform optimization for mobility and fuel compatibility (e.g., JP-8). While this reduces near-term compliance cost, it also delays emissions-driven powertrain transitions and creates divergence between military and commercial supply bases.
-
Funding variability and geopolitical shocks: Procurement rhythms are sensitive to defense budget cycles and crisis-driven accelerations. Forecasts therefore incorporate scenario branches that reflect surge buys and extended sustainment spending.
Competitive landscape — what the report reveals (and what it withholds)
Our benchmarking examines capability portfolios, industrial capacity, R&D trajectories, and most-recent program outcomes across established OEMs and rising suppliers. Several strategic observations emerge:
-
Market leaders leverage integrated value propositions. Firms with strong positions in tactical wheeled vehicles and armored platforms combine mobility innovations (advanced suspensions, modular drivetrains) with tested protection suites — enabling them to capture higher-margin systems and longer-term sustainment work.
-
Mid-tier players are exploiting niche specialization. Companies focused on logistics trucks, MRAP variants, or hybrid demonstrators are successfully targeting sovereign requirements and aftermarket modernization work where primes are less nimble.
-
Autonomy and electrification are the strategic differentiators for 2026. Firms demonstrating credible integration pathways — from demonstrators to fielded prototypes — will be favored in new procurement waves. Recent field demonstrations and contract awards are tangible signals: for example, teams led by major OEMs have been publicly showcasing light vehicle lineups in theatrical demonstrations, while defense relationships are generating prototype integrations for infantry mobility systems.
-
Industrial risk remains a gating factor. Even top suppliers face production schedule risks due to component supply constraints and steel-price volatility; program managers should weigh supplier financial resilience and multi-sourcing strategies in RFP evaluations.
For readers who track specific vendors, our full report includes side-by-side capability maps, supplier attractiveness scores and a wins/losses dossier for recent procurements. The preview deliberately omits the granular scoring and segment revenue splits to preserve the actionable value that subscribers and clients receive.
Representative company positioning (high level)
-
Oshkosh Defense — Strengths: Proven mobility systems and fielded combat platforms. Strategic posture: leveraging TAK-4i and established MRAP/JLTV lineage to defend and expand program wins.
-
AM General — Strengths: Heritage in light tactical mobility and global fleet sustainment. Strategic posture: emphasizing modular tactical kits and high-mobility derivatives to stay relevant in upgrade markets.
-
General Dynamics Land Systems — Strengths: Integrated armored systems and demonstrators in hybrid propulsion. Strategic posture: combining survivability and systems integration to compete in high-end segments.
-
BAE Systems and Rheinmetall — Strengths: Deep armored vehicle portfolios and large-scale program experience. Strategic posture: pursuing modularity and scalable protection suites for multi-role demands.
-
GM Defense, Navistar, Iveco, Mack Defense, Arquus, Tata Motors, Hanwha — Strengths: niche capabilities, regional presence, and logistics/utility focus. Strategic posture: targeting sovereign production, logistics modernization programs and emerging autonomy trials.
Recent events underline these dynamics: high-profile demonstrations and trials (e.g., late-2025 light-vehicle demos and DARPA autonomous navigation tests in early 2026) are accelerating the transition from concept to prototype. Simultaneously, service-level procurements to integrate autonomous mobility into infantry vehicles are creating short-term demand spikes that favor agile integrators.
What’s inside the full PW Consulting report (actionable deliverables)
-
Executive decision playbook: procurement timing, lot-sizing heuristics and contractual levers for managing commodity risk.
-
Risk-adjusted demand model: scenarios tied to geopolitical stressors and budget slippage, with sensitivity to raw-material price shocks.
-
Technology adoption roadmap: tested timelines for autonomy, hybridization, and materials innovation, including integration costs and maintenance implications.
-
Supply-chain remediation templates: dual-sourcing playbooks, long-lead component visibility frameworks, and mitigation contracts for armor steel and power electronics.
-
Competitive benchmarking and M&A candidate shortlists: quantified attractiveness scores, capability gaps and go/no-go acquisition thresholds.
-
Commercials and pricing playbook: TCO models for life-cycle cost comparisons, aftermarket revenue capture and sustainment contracting strategies.
Practical strategic recommendations for 2026
-
Prioritize modularity to future-proof procurement. Contracts should require open architectures and upgrade rails to permit rapid insertion of autonomy, sensors and electronic protection suites.
-
Lock in long-lead components now. Given supply fragility for armor steel and power electronics, secure forward contracts and validate secondary suppliers to reduce schedule risk.
-
Invest selectively in autonomy pilots. Allocate program dollars to realistic tech-readiness demonstrations aligned with fielded operational use cases rather than technology vanity projects.
-
Use hybrid contracting models. Balance fixed-price lots for proven platforms with incentive-based awards for innovation to accelerate adoption while containing program risk.
-
Monitor regulatory signals but don’t overaccelerate decarbonization solely on civilian standards. Military exemptions currently permit fuel and engine configurations optimized for mobility; transition planning should be deliberate and mission-driven.
Next steps — how to use this briefing
This preview demonstrates the strategic framing and analytical rigor in PW Consulting’s full Worldwide Military Off-road Vehicles Market report. If you are a program director, prime contractor, investor, or sovereign purchaser preparing decisions in 2026, the full report will provide the granular scenario outputs, supplier scorecards and procurement playbooks you need to execute with confidence.
To access the complete market model, segmentation breakdowns, company dossiers and actionable templates — including downloadable spreadsheets and a short advisory engagement option — please visit the PW Consulting report page. Our subscription and bespoke advisory offerings can be tailored to align the intelligence in this report with your procurement calendars, R&D roadmaps and M&A timelines.
PW Consulting — translating market complexity into decisive strategy for defense leaders.
For detailed analysis of this topic, please visit the official page: Worldwide Military Off-road Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com