

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Charging Port Door Actuators Market to Grow at 16.5% CAGR, Reach USD 994.36 Million by 2032

Worldwide Charging Port Door Actuators Market: Strategic Imperatives for 2026 — PW Consulting Insights
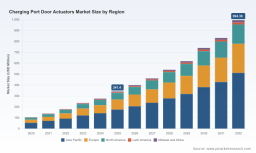
PW Consulting’s latest market study on Worldwide Charging Port Door Actuators (base year 2025, forecast 2026–2032) frames a decisive inflection point for OEMs, Tier‑1 suppliers, investors and procurement organizations. The segment has transitioned from a niche electromechanical accessory into a mission‑critical subsystem that couples vehicle safety, user experience and charging interoperability. Our bottom‑up model shows the market expanding at a 16.5% compound annual growth rate (CAGR) from 2026 onward, having grown from approximately USD 105.4 million in 2020 to USD 341.4 million in 2025, and projecting to nearly USD 1.0 billion by 2032. Those headline trajectories underscore why charging port door actuators must now be treated as strategic components in EV programs rather than commoditized items.
Worldwide Charging Port Door Actuators Market
Why this report matters for 2026 decision cycles
-
Timing and resource allocation — The 2026 product planning and supplier selection windows are when actuator choices become locked into vehicle platforms. Our report maps when technical specifications, qualification cycles and procurement milestones align across BEV and PHEV programs, enabling teams to prioritize investments that will deliver the highest risk‑adjusted returns.
Worldwide Charging Port Door Actuators Market -
Risk identification and mitigation — Rapid market growth and tighter regulatory expectations are increasing failure costs for poorly specified actuator systems. We quantify the primary failure modes, time‑to‑remediate scenarios and their commercial impact, allowing commercial and engineering leaders to weigh tradeoffs between upfront development expense and downstream warranty/liability exposure.
Worldwide Charging Port Door Actuators Market -
Partnering and M&A signal guidance — With a moderately concentrated supply base (our concentration analysis shows the top three suppliers control a significant share of addressable volume, and the top five an even larger portion), the report identifies the opportunistic zones for strategic alliances, minority investments and bolt‑on acquisitions to close capability gaps.
Market dynamics shaping 2026 strategies
-
Technology evolution — The product architecture is shifting from purely mechanical release mechanisms toward feature‑rich electromechanical actuators with embedded controls, vehicle network interfaces (LIN/CAN), and advanced HMI (gesture, capacitive touch, integrated lighting). This movement is driven as much by user experience and security requirements as by assembly and packaging advantages.
-
Regulatory pressure and safety standards — Mandates for standardized charging interfaces in major markets and stricter functional safety requirements (including ISO 26262 expectations for fault detection and redundancy) are accelerating demand and raising the bar for actuator validation. In some regions, standardization measures have correlated with double‑digit year‑over‑year sales growth for compliant subsystems.
-
Supply chain constraints — Specialized components such as rare‑earth magnets, high‑precision gearing and custom sensors have experienced intermittent shortages. Lead times for certain actuator models have extended to 12–16 weeks, making supply continuity and component strategy central topics for procurement teams.
-
Commercial shifts — Charging port door actuators are now part of broader electrification feature bundles (automatic flaps, locking, HMI, integrated sensing). Suppliers that can offer modular, platform‑agnostic modules with proven software stacks are capturing preferment in early program stages.
Competitive landscape: capabilities that matter
The competitive map is mixed: established global Tier‑1s and specialist mechatronics firms co‑exist with regional manufacturers. Leading companies distinguish themselves along three axes — system integration (actuator + flap + HMI), functional safety and serviceability, and platform scalability for high‑ and low‑volume programs.
-
Magna International (Aurora, Canada) — Offers a complete automated flap system with high‑torque actuators and integrated safety and convenience features. Their approach emphasizes turnkey integration for OEMs seeking to reduce systems‑level integration risk.
-
Motion Controls Inc (MCi, United States) — Focuses on high‑speed/high‑torque actuators with protective mechanical clutching and flexible control options (from simple to full LIN integration), leveraging patented motion control concepts for aero and charging applications.
-
NMB Technologies (MinebeaMitsumi, Japan) — Delivers smart BLDC actuator solutions with sophisticated sensor and communication features, suited to programs that require compact, programmable modules.
-
Regional specialists (China, India, Germany, etc.) — Manufacturers such as Haoyong, Padmini VNA, WITTE, Röchling, Marquardt, Johnson Electric and TE Connectivity provide a spectrum of solutions from robust mechanical modules to advanced locking actuators compatible with global charging standards. Their offerings vary by design focus: durability, cost efficiency, certification pedigree, or modularity.
Recent commercial moves underline consolidation and capability extension across the value chain: Bosch’s strategic collaboration on next‑generation actuators (March 2025), Valeo’s modular system launch (November 2024), and Continental’s contract wins on global EV programs (May 2024) signal heightened supplier competition around system reliability, sealing and platform speed to market.
What’s inside the PW Consulting report (practical deliverables)
-
Proprietary demand model — A scenario‑based market model covering 2026–2032 with sensitivity to vehicle production ramp rates, standardization events and material lead‑time shocks.
-
Commercially actionable supplier profiles — Deep‑dive assessments of leading suppliers’ technical roadmaps, qualification timelines, capacity constraints, and win/loss intelligence (kept at program level to preserve client confidentiality).
-
Technology matrix and validation playbook — Comparative evaluation of actuator topologies (electronic vs. mechanical approaches), interface options, and test protocols to meet ISO 26262 and environmental sealing expectations.
-
Procurement playbook — Sourcing strategies, contract structures, risk allocation templates, suggested lead‑time buffers and dual‑sourcing approaches to mitigate 12–16 week component lag risks.
-
Regulatory & standards tracker — A living register of charging interface standardization initiatives and functional safety updates that could materially affect specification windows.
-
Commercial impact scenarios — Quantified cost of non‑compliance, warranty exposure estimates and recommended contingency budgets for high‑risk platforms.
How to translate insights into 2026 actions: short checklist for executives
-
Lock technical baselines early — Define required actuator functions and safety margins at the concept freeze stage to minimize downstream rework and supplier change orders.
-
Prioritize modularity — Favor actuator architectures that support common mounting, shared electronics stacks and configurable HMI options to reduce platform engineering costs.
-
Secure component continuity — Negotiate staggered long‑term purchase agreements for critical subcomponents, and evaluate near‑shoring or strategic inventory positions for rare‑earth magnets and precision gears.
-
Invest in validation capacity — Allocate resources for rigorous environmental, functional safety and durability testing to shorten qualification cycles and reduce field recalls.
-
Engage in supplier co‑development — Consider early partnerships or minority investments with suppliers that offer differentiated software or mechatronic IP to accelerate feature rollout and protect time‑to‑market.
-
Monitor standards evolution — Embed a regulatory watcher in cross‑functional program teams to anticipate changes to charging interface mandates and adjust specifications before contract sign‑off.
Why PW Consulting’s report is uniquely useful
Our study combines a granular, bottom‑up demand model with supplier‑level intelligence and engineering validation practices. That blend is intended for leaders who must make capital allocation, sourcing and product roadmap choices in 2026 under uncertainty: the model quantifies upside/ downside scenarios, the supplier profiles expose capacity and capability constraints, and the playbooks translate those insights into executable procurement and engineering plans.
Next steps — a focused invitation
This release is a preview designed to inform initial strategy discussions. The full report contains the detailed segmentation tables, supplier scorecards, program‑level win/loss analysis and our complete downloadable demand model — all of which are intentionally gated to protect commercially sensitive sourcing and contract data and to enable tailored briefings. For teams preparing 2026 commitments, scheduling a briefing with our analysts will rapidly convert the macro view into program‑specific recommendations.
Contact PW Consulting to arrange a private briefing and obtain access to the complete Worldwide Charging Port Door Actuators Market report, including the interactive forecasting model and supplier heatmaps that will be indispensable for 2026 decision making.
For detailed analysis of this topic, please visit the official page: Worldwide Charging Port Door Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com