

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Alternate Light Sources Market Forecast to Expand at a 5.72% CAGR During 2026–2032

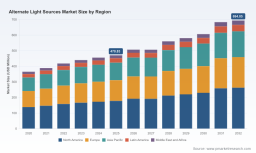
Worldwide Alternate Light Sources Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As organizations recalibrate forensic, medical diagnostics, and industrial inspection capabilities for the mid‑2020s, Alternate Light Sources (ALS) have moved from niche tools to mission‑critical instruments. PW Consulting’s forthcoming Worldwide Alternate Light Sources Market report — base year 2025, historical coverage 2020–2025, and forecast horizon 2026–2032 — frames the market’s transition in operational, regulatory, and procurement terms. This preview summarizes the report’s strategic value for executives, procurement leads, and product teams preparing 2026 strategies while intentionally omitting granular segmentation tables; detailed breakdowns and vendor scorecards are available in the full report.
Worldwide Alternate Light Sources Market
Market Trajectory and What It Means for 2026 Decisions
The ALS market has demonstrated consistent expansion through the first half of the decade, rising from the low hundreds of millions of USD in 2020 to an estimated USD 470.83 Million in 2025 (revenue unit: Million USD). Our consolidated forecast projects the market to exceed USD 507 Million in 2026 and to continue growing at a compound annual growth rate (CAGR) of approximately 5.72% through 2032, reaching just under USD 695 Million by the end of the forecast horizon.
Worldwide Alternate Light Sources Market
For decision‑makers, three immediate implications follow:
Worldwide Alternate Light Sources Market
- Strategic procurement should prioritize lifecycle value over purchase price. With the market growing steadily, vendors are differentiating via warranties, modular optics, field serviceability, and data integration rather than purely on unit cost.
- R&D and product managers must orient roadmaps to interoperability and safety compliance (e.g., wavelength-specific eye protection and SWGDE photography practices). Early investment in these features reduces total cost of ownership and shortens procurement cycles for law enforcement and clinical buyers.
- Channel and aftermarket strategies will be decisive. As unit volumes grow, service contracts, consumables (filters, batteries), and training will drive a growing share of lifetime revenue — an opportunity often overlooked in initial procurement evaluations.
Competitive Structure and Supplier Dynamics
The ALS landscape displays moderate concentration: the top three vendors collectively capture a meaningful share of the market while the top five extend that reach further. This concentration suggests a market where established brands exert pricing and specification influence, but where mid‑market and specialized players continue to find niche opportunities.
Key vendor archetypes identified in our analysis include:
- Heritage forensic specialists who focus on laboratory‑grade multi‑wavelength systems and evidence screening workflows.
- Ruggedized field suppliers offering cordless, durable kits optimized for crime scene deployment.
- Cost‑effective handheld manufacturers that emphasize simplicity and ergonomics for rapid field adoption.
Representative companies profiled in the report include:
- Foster + Freeman (United Kingdom) — Known for high‑intensity LED forensic light sources, multi‑wavelength single‑unit systems, and next‑generation lab screening units designed to integrate into forensic workflows. ( https://fosterfreeman.com)
- Labino AB (Vallentuna, Sweden) — Focused on waterproof, field‑ready LED ALS kits that prioritize straightforward operation and durability; recently refreshed product literature to support procurement cycles. ( https://labino.com)
- Sirchie (United States) — Supplies a broad portfolio for law enforcement, including shortwave UV systems and tactical ALS kits, with clear safety guidance for hazardous wavelengths. ( https://www.sirchie.com)
- HORIBA Scientific (SPEX Forensics) (United States) — Offers laboratory and field LED systems aimed at latent print and body fluid visualization, with a strong emphasis on imaging compatibility. ( https://www.horiba.com)
- FoxFury (United States) — Specializes in rugged cordless forensic lighting and ALS lasers optimized for first responders and outdoor scenes. ( https://www.foxfury.com)
- Lynn Peavey Company and UltraLite ALS (United States) — Distributors and specialized portable providers emphasizing turnkey kits for crime scene processing and evidence documentation. ( https://lynnpeavey.com)
In the full report we publish a comparative vendor scorecard that evaluates product portfolios across technical depth, field reliability, serviceability, pricing strategy, and channel reach. The scorecard empowers buyers to move beyond marketing claims to procurement‑ready shortlists.
Regulatory and Standards Context — Non‑Negotiable in 2026
Standards and regulation shape both demand and product design. Our Dynamics section synthesizes guidance from authoritative sources and its practical implications for buyers and vendors alike:
- NIST’s formal definitions clarify ALS scope and underpin procurement specifications used by public agencies.
- The U.S. Department of Homeland Security’s Authorized Equipment List (AEL) includes portable forensic light kits under a specific category, influencing eligibility for federal grants and state procurement programs.
- SWGDE guidelines set procedural requirements for luminescence documentation in low‑light crime scene photography — affecting tripod compatibility, exposure modes, and wavelength‑specific eye protection included with vendor offerings.
- Operational safety guidance, including manufacturer directives on shortwave UV exposure, are essential for compliance; failure to adhere increases organizational risk and liability.
For vendors, alignment with these standards is not optional — it materially impacts market access and the sales cycle length for public sector buyers. For buyers, specifying standards alignment in RFIs and RFPs removes ambiguity and shortens evaluation cycles.
Technological and Application Trends Shaping 2026
Several technology and use‑case trends are converging to reshape buying criteria:
- LED platform dominance: LED architectures continue to lead in energy efficiency and lifespan, prompting vendors to build modular optics rather than replace entire units.
- Integration of multispectral imaging with ALS: Buyers increasingly demand compatibility between light sources and imaging systems for documentation and AI‑assisted evidence analysis.
- Ruggedness and portability: Field deployments by first responders demand compact, waterproof, and battery‑resilient solutions, fueling growth in cordless ALS designs.
- Service and training as revenue levers: Vendors that couple product sales with certified training and rapid field service capture greater wallet share across the equipment lifecycle.
Our report explores each trend in depth and quantifies the operational impact on different buyer personas — from municipal forensic departments to private industrial inspection teams.
What the Report Contains — Practical Deliverables for 2026 Planning
The full PW Consulting report is built for direct application in strategy and procurement processes. Core deliverables include:
- Market model and forecasts (2026–2032) with scenario analysis and sensitivity tests tied to adoption rates and regulatory shifts.
- Go‑to‑market playbooks for vendors targeting public safety, clinical diagnostics, and industrial inspection channels.
- Procurement templates and RFP language mapped to standards (NIST, DHS AEL, SWGDE) to shorten buying cycles and reduce supplier ambiguity.
- Vendor scorecards and quadrant placements based on capability, reliability, service, and pricing architecture.
- Channel economics models and aftermarket income projections to support pricing and bundling strategies.
- Risk register and mitigation blueprint covering safety exposures (e.g., shortwave UV), supply chain dependencies, and intellectual property considerations.
- Buyers’ ROI calculator and TCO checklist tailored to field vs. laboratory deployments.
These practical assets are designed to be plug‑and‑play for capital planning, competitive benchmarking, and vendor selection in 2026.
Recent Market Signals and What They Imply
Company‑level activity signals continued investment around product refresh and field readiness. Notable examples include a January 2025 product catalog refresh from a prominent Swedish kit maker and an April 2025 launch/refresh of next‑generation evidence screening units by a leading UK forensic supplier. These moves confirm vendor focus on modular LED technologies, improved ergonomics, and clearer specification documentation — all responses to buyer demand for simplicity, durability, and standards‑aligned features.
Additionally, the market hosts more than a dozen manufacturers and a wide pricing spectrum, indicating room for both premium innovation and low‑cost penetration strategies. More than 50 product SKUs across handheld, laboratory, and ruggedized form factors create choice complexity that often slows procurement unless buyers adopt structured evaluation frameworks.
How to Use This Preview
If you are a procurement head, use this preview to reframe 2026 budgets toward total cost of ownership, compliance alignment, and modularity. If you are a product leader or investor, map R&D near‑term roadmaps to imaging interoperability and serviceability. For vendors navigating competitive dynamics, prioritize channel enablement and certified training to capture aftermarket value.
To maintain the “trailer” principle: this article intentionally highlights strategic takeaways and high‑level market metrics while withholding detailed regional, type, and application splits. PW Consulting’s full report contains comprehensive segment tables, primary research attachments, vendor financials, and downloadable datasets to support your procurement specifications and strategic planning.
Next Steps
- Access the full report for segmented market analytics, downloadable models, and the vendor scorecard that operational teams use to build 2026 RFPs.
- Request a briefing or custom workshop with PW Consulting to translate report findings into a six‑month procurement roadmap or a product roadmap sprint.
- Subscribe to our executive summary newsletter for fortnightly updates on ALS technology, standards developments, and vendor movements.
PW Consulting’s Worldwide Alternate Light Sources Market report provides the quantitative backbone and the operational playbooks that organizations need to make high‑confidence decisions in 2026. For the full dataset, vendor scorecards, and actionable procurement templates, visit our report page or contact our industry advisory desk.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com