

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Turbocharger Bearing Market to Reach USD 3,075.9 Million by 2032 on a 5.25% CAGR, Led by Asia‑Pacific

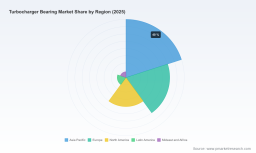
Worldwide Turbocharger Bearing Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market research, Worldwide Turbocharger Bearing Market (Base Year: 2025; Historical: 2020–2025; Forecast: 2026–2032), provides an executive-grade roadmap for manufacturers, OEMs, suppliers, and investors preparing strategies for the pivotal year of 2026. With the global market projected to grow at a 5.25% CAGR through the forecast horizon, this briefing highlights the structural dynamics, competitive levers, and risk vectors that should shape boardroom decisions — while reserving the detailed segment-level matrices for subscribers of the full report.
Worldwide Turbocharger Bearing Market
Why 2026 is a Strategic Inflection Point
The turbocharger bearing market is moving beyond incremental volume growth to a phase defined by technology migration, regulatory acceleration, and concentrated supplier power. Our model — calibrated on historical performance through 2025 and projecting to 2032 — shows steady, compounding expansion of the overall market (reported in USD Million), underpinned by product innovation and tightening emissions regimes. For 2026 specifically, industry participants will face a unique conjunction of opportunities and constraints: increased demand for low-friction and high-temperature bearing solutions, volatile raw material inputs, and competitive responses from both legacy bearing giants and niche specialist players.
Worldwide Turbocharger Bearing Market
Macroeconomic and Regulatory Drivers
-
Regulatory push: Stringent emission standards in major markets (for example, new Euro 7 provisions and tightened heavy-duty NOx limits) are accelerating adoption of more efficient turbocharging systems. Bearings that enable higher rotational speeds, lower frictional losses, and longer thermal endurance will be central to compliance strategies and powertrain downsizing efforts.
Worldwide Turbocharger Bearing Market -
Powertrain transition: Electrified turbocharging concepts and 48V mild-hybrid architectures are increasing technical demands on bearing solutions — especially in terms of transient response and electrical compatibility — prompting OEMs to specify advanced foil and hybrid ceramic bearings.
-
Raw material pressure: Recent commodity movements — including higher alloy-steel prices and notable increases in copper content costs for bronze bearings — are compressing margins for producers reliant on traditional metallurgy, and are raising the importance of supply chain hedging and material substitution strategies.
-
Trade and geopolitics: Tariff regimes and trade frictions have altered sourcing economics and manufacturing footprints. Companies that can demonstrate resilient regional supply or localized value capture will be advantaged as OEMs seek to de-risk procurement.
Market Size and Growth Trajectory (Overview)
Our topline market model — expressed in USD Million — documents the sector’s progression through 2025 and projects steady growth throughout the 2026–2032 forecast window at a 5.25% CAGR. The trajectory reflects both organic replacement demand and incremental uptake in advanced bearing technologies required by next-generation turbocharger platforms. This macro view is indispensable for sizing investment cases, capital expenditure schedules, and break-even analyses for new product lines.
Competitive Landscape — Key Players and Strategic Positioning
The turbocharger bearing market exhibits a balanced mix of diversified global incumbents and specialized technology firms. Market concentration metrics indicate that leading firms collectively account for a significant share of industry revenue, creating conditions where scale, technology IP, and OEM relationships matter. These market concentration dynamics are important inputs when evaluating strategic moves such as capacity expansion, pricing strategies, or targeted M&A.
-
Schaeffler Group (Herzogenaurach, Germany) — A leading supplier with deep capabilities in journal bearings and foil air bearings for automotive and commercial turbochargers. Schaeffler’s strong OEM ties and recent showcases of next-generation foil bearings position it as a pace-setter for electrically assisted turbo solutions.
-
SKF AB (Gothenburg, Sweden) — Focused on hybrid ceramic and air-foil technologies optimized for high-speed operation. SKF’s investments into extended-durability turbocharger bearings aim to capture growth in heavy-duty and high-performance passenger applications.
-
NTN Corporation (Nara, Japan) — A broad-based bearing manufacturer producing roller and ball bearings engineered for both passenger car and heavy-duty turbocharger requirements. NTN’s product breadth enables flexible quoting across OEM programs.
-
NSK Ltd. (Tokyo, Japan) — Known for high-temperature angular contact ball bearings designed for demanding turbocharger environments; NSK’s focus on materials and lubrication developments underpins performance claims for elevated thermal cycles.
-
The Timken Company (North Canton, Ohio, USA) — Offers tapered roller and super-precision bearings largely aimed at industrial and heavy-duty turbo applications, with an emphasis on durability in power generation and marine segments.
-
RBC Bearings Incorporated (Plainview, New York, USA) — A specialist in foil air and thrust bearings with cross‑sector relevance, including aerospace — a differentiator for customers demanding extreme performance and longevity.
-
JTEKT Corporation (Osaka, Japan) — Produces Koyo-brand needle roller and ball bearings adapted to turbocharger constraints; JTEKT’s global manufacturing footprint supports competitive lead times for major OEMs.
-
Waukesha Bearings Corporation (Waukesha, Wisconsin, USA) — Supplier of hydrodynamic journal and tilt-pad bearings for power generation and marine turbochargers, complementing industrial OEM supply chains.
Recent industry moves — product launches, trade-show reveals, and targeted exhibitions — underscore both incremental innovation and strategic signaling. Examples include advanced foil-bearing prototypes showcased at major mobility shows and hybrid-bearing product introductions for heavy-duty engines. These events provide insight into near-term commercialization timetables and customer validation cycles.
Structural Implications for 2026 Strategy
-
R&D Priorities: With regulatory windows compressing and performance expectations rising, R&D must prioritize low-friction surfaces, high-temperature ceramics, and lubrication systems tuned for transient turbocharger regimes. Firms should allocate resources to modular bearing platforms that can be adapted across powertrain variants.
-
Supply Chain & Sourcing: Given recent material cost shocks and geopolitically driven tariff risks, companies must re-evaluate sourcing strategies. Options include multi-sourcing critical alloys, strategic long-term contracts, and material-substitution pilots. Near‑shoring or regional manufacturing can be a defensive move to preserve OEM access.
-
Commercial & Pricing: Margin pressure from raw material inflation will necessitate more sophisticated price escalation clauses, value-based pricing for premium bearing technologies, and bundled value propositions (e.g., warranties, predictive maintenance offerings) to protect margins.
-
Partnerships & Open Innovation: Fast followers and smaller innovators (e.g., foil-bearing specialists) are attractive partners for joint development or licensing. OEM co-development agreements can accelerate adoption while sharing technical risk.
-
M&A & Capacity Rationalization: Market concentration trends create opportunities for bolt-on acquisitions that provide technology differentiation or regional scale. Conversely, incumbents should evaluate capacity reconfiguration to prioritize high-margin advanced bearing families over commodity lines.
-
Aftermarket & Service Models: As turbocharger systems become more sophisticated, aftermarket service and predictive maintenance will gain strategic importance. Businesses that combine bearings with sensing, analytics, and lifecycle services will unlock recurring revenue streams.
Risk Assessment — What to Monitor in 2026
-
Commodity volatility: Continued upward pressure on steel and copper pricing can erode margins; hedging and alloy innovation are defensive priorities.
-
Regulatory timing: Delays or acceleration in regional emissions rollouts can materially affect adoption timelines for premium bearing technologies.
-
Competitive responses: Rapid product introductions by market leaders can shorten window-of-opportunity for late entrants; a fast-to-market strategy combined with clear OEM proof points is critical.
-
Supply chain disruptions: Logistics shocks and trade policy shifts remain systemic risks; contingency planning and supplier auditing will reduce exposure.
What the Full Report Delivers (Practical Toolkit)
PW Consulting’s full report contains the practical tools executives need to operationalize the insights summarized here, including:
-
Proprietary market model with annual revenue estimates (USD Million) through 2032 and scenario-based sensitivity analysis for commodity and regulatory shocks.
-
Demand-driver matrices linking regulatory milestones, vehicle powertrain mix, and bearing technology uptake timelines.
-
Supplier heatmaps and capability scorecards that assess technology, scale, quality, and OEM access across the major competitive players.
-
Commercial playbooks for pricing, contracting, and service offers suitable for OEM and aftermarket channels.
-
Acquisition screening templates and synergy calculators for inorganic growth planning.
To preserve the strategic value of the report for clients, this preview intentionally omits the detailed segment-level splits and discrete revenue-by-region/application tables. Subscribers receive the full segmentation, granular unit economics, and raw-data workbooks required for capital allocation and program-level negotiations.
Recommended Next Steps for 2026 Planning
-
Initiate cross-functional workshops (R&D, procurement, commercial) to stress-test product roadmaps against the regulatory timelines embedded in our forecast.
-
Secure multi-year material contracts or strategic alliances to mitigate input-cost volatility without sacrificing flexibility for material innovation.
-
Prioritize pilot programs with OEMs for advanced bearing technologies (foil, hybrid ceramic) to earn design wins that will crystallize volume post-2026.
-
Evaluate targeted M&A opportunities that fill capability gaps or create regional supply resilience, using our acquisition screening templates as a starting point.
-
Develop aftermarket service offers that leverage sensorization and predictive analytics to create recurring revenue streams and deepen OEM/customer relationships.
Closing Perspective
As turbocharger systems evolve, the bearing sub-market will shift from a largely engineered commodity to a strategic differentiator in powertrain development. PW Consulting’s Worldwide Turbocharger Bearing Market report equips leaders with the quantitative backbone and qualitative context necessary to make disciplined 2026 decisions — from R&D prioritization and supply-chain restructuring to pricing and M&A. For executives who need the full dataset, segment-level forecasts, and executable templates, the complete report and interactive model are available on our website.
Contact PW Consulting to request the full report and a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com