

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide PEI Films Market Poised for Robust Expansion at a 7.12% CAGR, New Report Finds
By pmarketresearch, 2026-07-15
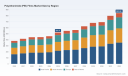
PW Consulting: Strategic Outlook — Worldwide Polyetherimide (PEI) Films Market Through 2032
As organizations position product roadmaps and capital allocation for 2026, the polyetherimide (PEI) films market is emerging as a quietly strategic arena. Our latest PW Consulting report — based on a rigorous five-year historical review and a seven-year forecast horizon — maps the market’s structure, supply-chain fault lines, regulatory inflection points, and competitor plays that will determine which manufacturers, converters, and end-users capture disproportionate value through the next business cycle.
Worldwide Polyetherimide (PEI) Films Market
Executive snapshot: scale, trajectory, and concentration
PEI films are now a mid-sized specialized polymer market with measurable scale and attractive growth fundamentals. Using 2025 as the base year, PW Consulting estimates the market value at approximately USD 521.5 Million (revenue, USD Million). Under the assumptions and scenarios modelled in this study, the market grows at a compound annual growth rate (CAGR) of 7.12% across the 2026–2032 forecast period, targeting a near-term seven-year market value that materially exceeds current run-rates.
Worldwide Polyetherimide (PEI) Films Market
Market concentration is meaningful: the top three players account for a majority share, and the top five approach near-complete control of the competitive landscape. This structure creates three practical realities for corporate strategists: (1) incumbents enjoy scale economies and technical validation advantages, (2) niche entrants can thrive with differentiated formulations or service models, and (3) M&A or strategic partnerships remain high-impact levers for gaining access to qualified material supply and application know-how.
Worldwide Polyetherimide (PEI) Films Market
Why PEI films matter to 2026 strategies
-
High-performance polymer positioning: PEI films combine heat resistance, dielectric properties, and thin-gauge form factors. These attributes make the material an enabler across demanding applications where qualification cycles are long and material change is non-trivial. For product teams planning 2026 rollouts, material selection decisions made today will lock in cost, performance, and qualification timelines for several product generations.
-
Value capture through application engineering: Firms that invest in application-specific grades and conversion capabilities can convert structural polymer demand into differentiated, higher-margin film solutions. Technical depth in film processing and tailored formulations creates defensible customer relationships, especially in industries with stringent fire, thermal, and outgassing requirements.
-
Supply-chain and input-cost volatility: Feedstock tightness and price inflation upstream have real-time implications. For instance, a key PEI monomer experienced double-digit price escalation in Asia in late 2024, a dynamic that reverberates through producer margins and conversion economics. Companies that proactively hedge, qualify alternate feedstock sources, or integrate upstream will be better positioned in 2026.
Regulatory and standards dynamics shaping product strategy
Regulatory compliance and sectoral standards are decisive variables in the PEI films market. Several contemporary developments are particularly relevant to 2026 decision-making:
-
Flammability and aerospace certification: Modern PEI films are capable of achieving stringent flammability ratings at thin gauges, enabling use in weight-sensitive aerospace and avionics architectures. For producers and Tier-1 suppliers, readiness to support aerospace qualification protocols is a commercial advantage.
-
Chemical migration and materials restrictions: Certain PEI grades comply with restrictive substance frameworks relevant to food contact and consumer safety. The convergence of end-market expectations and regulatory scrutiny requires robust compliance documentation and testing programs — an often-underestimated barrier to market entry for smaller converters.
Competitive landscape — what differentiates winners
Our report devotes extensive coverage to corporate strategy and capability mapping. Three archetypal players illustrate the competitive contours:
-
SABIC (Riyadh, Saudi Arabia): A global leader in technical PEI films, SABIC’s product portfolio and material validation footprint across aerospace, electronics, and medical sectors provide a high bar for scale and technical certification. Their thin-gauge offerings and thermal performance benchmarks underscore the premium positioning incumbents enjoy in certified markets.
-
Ensinger GmbH (Nufringen, Germany): Ensinger represents a technical-specialist model focused on tailored film and sheet products for demanding automotive, electronics, and medical applications. Close customer collaboration, custom thicknesses, and application engineering are the hallmarks of this approach.
-
RTP Company (Winona, Minnesota, USA): RTP embodies a differentiated-compounding play, offering custom-formulated PEI films for niche electrical insulation and flexible circuitry applications. Their competency in compounding and specialty grades highlights the role of formulation flexibility as an entry route into targeted high-value use cases.
The market’s competitive balance — with concentrated leaders and agile specialists — suggests a bifurcated strategy set for 2026: scale-driven incumbents will continue to defend specification-intensive segments, while nimble specialists can win through customization, fast qualification support, and co-development with OEMs.
Supply-chain risks and mitigation tactics
Two supply-side realities will shape corporate risk registers in 2026:
-
Upstream feedstock tightness and price pass-through: The market saw notable monomer price pressure in 2024. Material buyers should embed feedstock sensitivity analyses into sourcing strategies and consider long-term contracts, dual-sourcing, or backward integration where scale and regulatory feasibility permit.
-
Qualification lead times: End-market qualification windows — particularly in aerospace and medical segments — can be multi-year endeavors. Suppliers that provide comprehensive validation documentation, accelerated testing services, and pre-qualified material kits will shorten customer adoption cycles and capture premium share.
Strategic imperatives for decision-makers planning in 2026
Building on our quantitative forecasting and qualitative interviews across the value chain, PW Consulting recommends four high-impact moves for companies developing 2026 strategies:
-
Prioritize qualification-capability investments: Allocate budget to testing labs, flame- and toxicity-testing capacity, and accelerated ageing protocols. These assets shorten sales cycles in aerospace, defense, and medical segments where regulatory certainty drives procurement.
-
Hedge or diversify feedstock exposure: Given the recent monomer price volatility, establish a layered procurement strategy that combines strategic contracts, geographic diversification, and potential collaboration with monomer producers to secure competitive input costs.
-
Pursue targeted M&A or JV activity to accelerate market entry: For companies seeking volume or certification uplift, acquiring a converter with established aerospace or electronics approvals can shortcut multi-year organic efforts. Conversely, niche specialists should evaluate partnerships that expand go-to-market footprints without diluting technical focus.
-
Differentiate through services: Offer engineering consultancy, custom lamination, or integration services (e.g., flexible circuit lamination or EMI shielding assemblies). Value-added services convert material sales into longer-term contracts and higher lifetime customer value.
Report composition — what PW Consulting delivers
The full PW Consulting report translates these strategic implications into actionable tools for executives and investment committees. Highlights include:
-
Quantitative market model (USD Million) with historical reconciliation (2020–2025) and a detailed forecast through 2032, stress-tested across demand and price scenarios.
-
Competitive landscaping, capability maps, and profiled playbooks for leading producers and specialty converters — including go-to-market differentiation, validation credentials, and technology roadmaps.
-
Risk matrices covering supply-chain exposure, regulatory trajectories, and substitution threats, alongside mitigation playbooks tailored to strategic archetypes (incumbent manufacturer, specialty converter, and OEM-integrator).
-
Go-to-market implications for product managers, procurement teams, and corporate development groups — including a prioritized list of pilot use-cases and vendor selection criteria for 2026 engagements.
In keeping with the “trailer” approach, this release purposefully outlines strategic contours and market-scale metrics to inform executive decision-making, while detailed regional, type, and application-level splits remain available exclusively in the full report. These deeper breakdowns are essential for deal structuring, capex prioritization, and targeted go-to-market plans — and are therefore reserved for subscribers and report purchasers.
How to use this insight in 2026 planning cycles
For product leaders and corporate strategists preparing 2026 roadmaps, the PEI films sector presents a blend of steady growth and high entry barriers. Use the forecast as a gating input to strategic choices: whether to onboard PEI films in next-generation products, to invest in conversion capacity, or to pursue vertical scale through acquisition. Balance the revenue growth potential surfaced by the 7.12% CAGR against supply-side risk and certification timeframes to prioritize capital and hiring decisions.
PW Consulting is prepared to support customized scenario modelling, supplier due diligence, and target screening for M&A or JV opportunities. Our modular advisory scope includes rapid 90-day market-entry playbooks and longer-term integration planning for firms seeking to accelerate capability build-out.
Concluding perspective
The PEI films market is not a mass-market polymer opportunity; it is a high-value, specification-driven arena where technical capability, certification readiness, and supply resilience determine winners. The market’s trajectory from a solid 2025 base toward considerably larger volumes by 2032 creates strategic incentives for focused investment, but also demands disciplined risk management. For executives finalizing 2026 budgets, the choice is clear: treat PEI films as a strategic enabler within high-performance product lines — and plan with the precision that their qualification and procurement complexities require.
To access the full PW Consulting Worldwide Polyetherimide (PEI) Films Market report, including granular regional, type, and application breakdowns that support transactional and operational decision-making, contact our market intelligence team or visit the PW Consulting publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Polyetherimide (PEI) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Anti‑Nestin Antibody Market Poised to Surge at 6.64% CAGR, Reaching USD 74.53 Million by 2032
By pmarketresearch, 2026-07-15
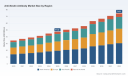
Worldwide Anti‑Nestin Antibody Market — Strategic Imperatives for 2026
PW Consulting today publishes a strategic briefing derived from our full market research report on the Worldwide Anti‑Nestin Antibody Market (base year: 2025; historical review: 2020–2025; forecast period: 2026–2032). The market has expanded steadily from the low‑30s (USD Million) in 2020 to just under USD 48 Million in 2025 and is forecast to reach the mid‑70s (USD Million) by 2032, reflecting a compound annual growth rate (CAGR) of 6.64% across the forecast period. This release is designed as an executive “trailer”: it synthesizes the research team’s most consequential insights and action points for 2026 decision‑makers while reserving granular regional, application and price tables for the full report.
Worldwide Anti-Nestin Antibody Market
Executive snapshot: what this means for 2026 strategy
- Growth momentum is durable but selective. Overall expansion is supported by sustained investment in basic and translational neuroscience, stem cell biology and oncology research; however, pockets of commercial intensity and competitive pressure vary by product format and validation claims.
- Market structure presents both concentration and opportunity. The market displays measurable concentration with the top three and top five suppliers commanding material portions of commercially available offerings—creating a commercial environment where scale and validation resources are differentiators.
- Regulatory and labeling realities shape near‑term addressable demand. Anti‑Nestin antibodies supplied by leading vendors remain Research Use Only (RUO), constraining direct diagnostic or therapeutic deployment and making rigorous, application‑specific validation a commercial differentiator rather than a compliance lever.
- Supply chain and manufacturing details matter. Production relies heavily on recombinant proteins and synthetic peptides as immunogens, with affinity purification and formulation choices (e.g., stabilizers such as BSA or sodium azide) materially affecting product stability, lot‑to‑lot consistency and buyer procurement preferences.
Why 2026 is a turning point
Two dynamics converge in 2026 to make strategic choices urgent. First, the research landscape is experiencing discrete increases in funding for neural stem cell and neuro‑oncology programs, driving demand for validated markers and conjugated formats that support flow cytometry, immunofluorescence and multiplex workflows. Second, suppliers face margin pressure as commoditization of basic antibody formats accelerates and customers increasingly demand validated, reproducible reagents with transparent manufacturing histories.
Worldwide Anti-Nestin Antibody Market
For suppliers, 2026 is a decision year: invest in depth (validation, conjugates, recombinant clones), protect margins through upstream control of immunogen and purification processes, or pursue scale via distribution agreements and portfolio breadth. For buyers and procurement leaders, 2026 is the inflection where certification of supply continuity and batch comparability becomes as important as unit price.
Worldwide Anti-Nestin Antibody Market
Competitive landscape — profiles and strategic positioning
- Thermo Fisher Scientific (Invitrogen) — Offers breadth: an extensive catalog of monoclonal, polyclonal and recombinant anti‑Nestin reagents validated across IHC, WB, ICC, FC and ELISA. Strategic advantage: scale and global validation data that appeal to academic and large‑scale industrial buyers.
- BD Biosciences — Focused presence in flow cytometry‑grade conjugated reagents and clone‑based solutions for intracellular staining. Strategic advantage: integration with established cytometry platforms and strong RUO positioning for developmental biology applications.
- Bio‑Rad Laboratories — Historically oriented toward research markets with polyclonal formulations targeted at neuroectodermal and tumor marker research. Strategic advantage: specialized formulations for histology and WB customer segments.
- STEMCELL Technologies — Differentiates via stem‑cell centric reagents and conjugate options, targeting embryonic neuroepithelial and glioblastoma research communities. Strategic advantage: deep domain alignment with stem‑cell researchers and associated protocols.
- R&D Systems (Bio‑Techne) — Emphasizes validated clones with publication citations; appeals to groups prioritizing reproducibility and citation lineage.
- Sino Biological — Competitive on recombinant and hybridoma‑derived formats with flexible formulations; strategic strength in cost‑competitive supply and upstream recombinant capability.
- Miltenyi Biotec — Positions reagents in the context of developmental neurobiology research and cell separation workflows.
- Abcam — Offers a diverse antibody catalog with options across host species and conjugations; strong digital searchability and technical resources.
- Sigma‑Aldrich (Merck KGaA) — Leverages legacy reagent brand recognition with multiple clone and polyclonal options suitable for basic research applications.
Collectively, the market’s concentration measures indicate a landscape in which leading suppliers maintain meaningful share advantages but do not fully preclude nimble challengers that combine targeted validation data, competitive pricing and close engagement with research communities.
What the full report delivers — operational intelligence for 2026
- Robust market sizing and forward forecasts (2026–2032) with scenario and sensitivity modeling tied to funding, regulatory, and adoption variables.
- Commercial diagnostic: pricing benchmarks, channel mixes, and distributor margins — actionable for commercial and procurement teams.
- Supplier scorecards and comparative technical matrices (clone provenance, host species, validated applications, conjugates, lot‑release testing protocols).
- Product development playbooks including recommended validation studies that shorten customer adoption cycles and improve SKU stickiness.
- Supply‑chain due diligence dossiers on key raw materials (recombinant immunogens, peptides, affinity resins, stabilizers) and identified single‑source risks.
- M&A and partnership screening: target lists and valuation yardsticks for buyers and PE investors seeking consolidation or strategic bolt‑ons.
- Regulatory & labeling FAQ tailored to RUO constraints and pathways for transitioning selected reagents toward clinical‑grade workflows.
- Regional and application demand heatmaps (note: detailed regional/application tables are available only in the licensed full report).
Actionable recommendations for decision‑makers in 2026
- Prioritize validation that maps to customer workflows. Invest in multi‑application validation packages (IHC, FC, ICC, WB) and publish reproducibility datasets; customers increasingly buy against demonstrated protocol fit rather than brand alone.
- Differentiate via conjugation and recombinant offerings. Conjugated clones and recombinant antibodies reduce variability and unlock premium pricing in flow and multiplex assays.
- Strengthen upstream control of immunogen and purification processes. Vertical integration or qualified long‑term supplier contracts for recombinant proteins/peptides can improve margin and reduce supply interruptions.
- Deploy tiered commercial models. Maintain a commodity tier for cost‑sensitive buyers while creating a premium validated tier with technical support, lot comparability documentation and co‑development options for translational projects.
- For biotechs pursuing translational/diagnostic paths: begin early engagement with regulatory counsel and design validation protocols that can be adapted from RUO to regulated contexts; the RUO status of current offerings is a constraint, not an immutable barrier.
- Consider targeted M&A or distribution partnerships to round out gaps in conjugate technologies, geographic coverage or publication‑grade validation data.
- Build transparent supply‑chain traceability. Provide end‑to‑end manufacturing information (immunogen sequence, purification methods, stabilizers) to reduce customer switching costs.
Scenario planning and financial contours
Our baseline forecast assumes the 6.64% CAGR across 2026–2032 and reflects current adoption trajectories in core research domains. The full report includes upside and downside scenarios that model: accelerated adoption driven by new multiplex assays and increased research funding; and downside outcomes from tighter RUO interpretations or significant supply chain disruptions. Each scenario is supplied with implied revenue curves, margin pressure analyses and recommended tactical responses so commercial teams can prioritize investments with a clear view of expected ROI horizons.
Regulation, manufacturing nuances and buyer FAQs
Key practical realities addressed in the report’s FAQ: major commercial anti‑Nestin reagents remain designated RUO and are not for diagnostic or therapeutic use; manufacturing typically employs recombinant proteins or synthetic peptides as immunogens with affinity purification workflows and stabilizers (e.g., bovine serum albumin or sodium azide) incorporated at formulation. These elements influence labeling, shipping, cold‑chain requirements and customer acceptance; the full FAQ includes recommended labeling language and suggested lot‑release test panels.
Next steps — how to use this intelligence
PW Consulting’s briefing is intended to catalyze decisive actions in 2026. Suppliers should use the competitive and supply‑chain analysis to define investment priorities in validation and upstream control. Buyers and procurement teams should incorporate the supplier scorecards and risk dashboards into contract renewal cycles. Investors should leverage the scenario models and supplier shortlists to evaluate consolidation targets and technology bets.
For access to the full dataset, detailed regional and application splits, supplier scorecards and the complete methodological appendix, please consult the licensed report on the PW Consulting website. The full report contains the granular tables and appendices referenced in this briefing that are essential for transaction‑level decisions and product development roadmaps.
PW Consulting — actionable market intelligence for leaders shaping the future of antibody reagents and research‑grade diagnostics.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Nestin Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Zero-point Clamping System Market Poised for 6.55% CAGR Through 2032
By pmarketresearch, 2026-07-15
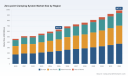
Worldwide Zero-point Clamping System Market — Strategic Briefing for 2026 Decision Makers
Executive summary
PW Consulting’s newest market research briefing on the Worldwide Zero-point Clamping System market synthesizes five years of historical observation (2020–2025) and a seven-year forecast window (2026–2032) into an actionable decision toolkit for manufacturing leaders, procurement officers, and corporate strategists. The market has expanded from roughly USD 462 million in 2020 to about USD 633 million in 2025, and our base-case forecast projects growth to nearly USD 1.0 billion by 2032 at a 6.55% compound annual growth rate (CAGR) for the forecast period. This trajectory reflects the combined impact of automation adoption, higher-mix/lower-volume production patterns, and ongoing performance improvements in workholding technology.
Worldwide Zero-point Clamping System Market
Why this report matters for 2026 strategy
-
Timing of capital allocation: With the market entering a sustained mid-single-digit CAGR phase, 2026 will be a pivotal year for committing CapEx to zero-point architectures as part of broader factory modernization and lights-out strategies.
Worldwide Zero-point Clamping System Market -
Supplier selection and risk mitigation: The market shows moderate concentration (CR3 ~42.8%, CR5 ~57.5%), indicating several influential incumbents alongside a diverse set of regional and niche players. This structure creates opportunity for leveraging competitive dynamics while requiring careful vendor qualification to avoid single-source exposure.
Worldwide Zero-point Clamping System Market -
Automation and integration: Zero-point systems are a pragmatic interface to Industry 4.0 goals — unlocking shorter setups, higher spindle utilization, and robotic handling compatibility. Decisions made in 2026 on standardizing interfaces and vendor platforms will materially shape throughput and flexibility for the next decade.
What PW Consulting’s report delivers — practical, transaction-ready content
-
Market-sizing and methodology: Transparent build-up from machine-level adoption assumptions to macro demand, reconciled to observed vendor footprints and trade-show intelligence. The report discloses base-year assumptions and sensitivity bounds to test investment theses.
-
Decision frameworks: Playbooks for procurement (TCO frameworks, warranty and service overlays, retrofit vs. greenfield cases), CapEx prioritization matrices, and ROI models calibrated for small-batch/high-mix operations as well as high-volume cellular environments.
-
Technical integration guidance: Interface checklists for mechanical, pneumatic, and hydraulic actuation types; automation-ready specifications; and thermal-management considerations for precision repeatability under production loads.
-
Vendor scorecards and RFP templates: Comparative assessment criteria covering precision, cycle-speed, sealing and cleaning readiness, integration with loading units, aftermarket support, and upgrade pathways — designed to accelerate vendor shortlists and procurement cycles.
-
M&A and partnership heatmaps: Strategic targets and capability clusters to consider for bolt-on acquisitions or distribution partnerships, including technology gaps and regional go-to-market considerations.
-
Scenario planning: Three demand scenarios (conservative, base, accelerated) with implications for inventory policies, supplier selection, and long-lead procurement decisions across a seven-year planning horizon.
Market dynamics shaping commercial choices in 2026
-
Operational economics: OEMs and job shops report setup-time reductions up to 90% with modern zero-point solutions; the knock-on effect is increased machine availability and reduced operator dependency. Our models quantify how incremental reductions in setup time translate into payback windows under different utilization profiles.
-
Materials and durability: System life depends on hardened alloy steel components treated for high surface hardness (approx. 57 HRC) to withstand cyclic loads and contamination — a non-negotiable design parameter for high-duty installations.
-
Precision and thermal behavior: Leading products deliver sub-3 μm repeatability and design for symmetrical thermal expansion to preserve datum integrity over temperature swings — criteria that should be explicit in technical procurement specs for precision-critical work.
-
Standards and automation: Vendors are converging on standardized, repeatable interfaces that facilitate integration into robotic loading, palletizers, and lights-out cells. Buyers should prioritize platforms that clearly map to their automation roadmap and allow future-proofing through modularity.
Competitive landscape — what the vendor field means for buyers and investors
The sector comprises established European innovators, global system integrators, and regional manufacturers offering differentiated approaches (mechanical, pneumatic, hydraulic, and integrated rotary-table solutions). Several vendors have shown active product development and trade-show presence in the past 18 months — activity that signals both continued incremental innovation and intensifying commercial outreach.
-
STARK Spannsysteme GmbH (ROEMHELD Group) — recognized for pioneering zero-point architectures and for emphasizing setup-time optimization across milling, turning, and automated lines. Their presence at major trade shows underlines a continued push into integrated factory solutions.
-
LANG Technik GmbH — known for modular grid systems and retrofitting capability, appealing to shops seeking to upgrade existing machines without large-stack modifications.
-
Zimmer Group — positions itself with application-specific modularity, supporting a range of processes from milling to EDM and grinding with focused error-reduction claims.
-
HAINBUCH GmbH — brings form-fit station systems that emphasize fast changeover for fixed-station, high-mix setups.
-
SMW-AUTOBLOK and EROWA AG — offer sealed, automation-optimized modules and palletized platforms respectively, targeting lights-out manufacturing and integration with automated loaders and EDM cells.
-
AMF Andreas Maier — demonstrates breadth across actuation types and has refreshed its catalog for 2025/2026 with modular offerings for cutting and non-cutting processes.
-
ZeroClamp, NIKKEN (Lyndex-Nikken), SCHUNK, Jergens, Gressel, and several Chinese manufacturers — represent either specialized high-precision options, integrated rotary-table strategies, or competitively priced alternatives for retrofit and domestic OEMs.
Recent product and trade-show activity (product module launches, EMO exhibitions, and catalog refreshes) confirms a market that is innovating incrementally and consolidating around automation-ready platforms. For organizations evaluating partners in 2026, due diligence should emphasize system compatibility with robotic handling, service networks, and the vendor’s roadmap for sealing, thermal management, and modular upgrades.
How to use this report to accelerate 2026 programs
-
Fast-track CapEx approvals: Use the report’s ROI matrices to build conservative and upside cases for immediate retrofit projects vs. phased greenfield investments; the workback from expected utilization gains will clarify acceptable payback thresholds.
-
Standardize interfaces now: Establish a plant-level mechanical and automation interface standard to reduce variation across installed systems and to enable multi-vendor sourcing without requalification costs.
-
Negotiate service-level agreements: With moderate market concentration, leverage competition to secure multi-year service contracts, spare-parts pooling, and rapid-response field service clauses that align with uptime targets.
-
Design supplier scorecards: Adopt the report’s vendor evaluation template to score vendors on repeatability, sealing, automation compatibility, retrofit complexity, and aftermarket support — then weight criteria to your production priorities.
-
Prepare integration pilots: Run two to three small-scale pilot integrations (different vendors or actuation types) in Q1–Q2 2026 to generate real-world data on cycle-time gains, fixturing flexibility and maintenance cadence before enterprise rollouts.
Risks, watchpoints, and red flags
-
Vendor lock-in and proprietary interfaces: Favor vendors that commit to open mechanical interfaces or provide adapter strategies to avoid future switching costs.
-
Underestimating thermal and contamination loads: Systems specified without adequate sealing or thermal-management provisions will degrade accuracy and life in heavy-duty environments.
-
Service-network gaps: Rapid adoption in new regions can outpace local service capabilities; ensure service and spare strategy is in place before scale-out.
-
Over-optimistic utilization assumptions: Payback models relying on unrealistic machine-utilization improvements can lead to stranded assets; stress-test assumptions across conservative scenarios.
Concluding recommendations
For 2026 decision cycles, zero-point clamping systems represent a high-leverage investment for companies pursuing increased machine capacity, faster changeovers, and deeper automation. Our market sizing and scenario work shows a market that has achieved meaningful scale and is forecast to expand steadily through 2032. Executives should treat zero-point selection as both a technical and strategic choice — one that will shape operational flexibility, supplier relationships, and automation outcomes for years to come.
PW Consulting’s full Worldwide Zero-point Clamping System Market report contains detailed vendor scorecards, the full segmentation model, RFP templates, and downloadable ROI tools designed to expedite procurement and integration. The report intentionally reserves certain granular segmentation and vendor-by-vendor numeric breakdowns to subscribers; this ensures the strategic exclusivity of commercially sensitive comparisons.
Next steps
-
Request a briefing with our industry team to align the report’s scenarios with your plant-level KPIs and CapEx calendar.
-
Commission a tailored procurement playbook using our RFP templates and vendor scorecards for immediate deployment in 2026 sourcing rounds.
-
Engage a pilot integration program to validate vendor claims on repeatability and cycle-time impact under your production conditions.
For access to the full dataset, downloadable tools, and the complete vendor assessments, please visit the PW Consulting report landing page or contact our lead analyst team to arrange a confidential walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Zero-point Clamping System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mosquito Repellent Water for Pregnant Women Market Poised for 7.5% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
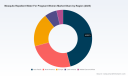
Worldwide Mosquito Repellent Water for Pregnant Women Market — Strategic Preview for 2026 Decisions
PW Consulting’s newest market study on Mosquito Repellent Water formulated for pregnant women distills multi-year market performance (2020–2025) and delivers a forward-looking forecast through 2032. The global market reached USD 275.0 Million in 2025 and—driven by a mix of public health concerns, product innovation, and channel evolution—is projected to exceed USD 303.6 Million in 2026, expanding at a compounded annual growth rate (CAGR) of 7.5% across the 2026–2032 forecast horizon to reach an estimated USD 456.2 Million by 2032. This release is intended as a strategic preview: it outlines high-value, decision-ready insights while directing commercial leaders to the full report for granular segmentation and actionable datasets.
Worldwide Mosquito Repellent Water For Pregnant Women Market
Why 2026 is a Strategic Inflection Point
-
Policy clarity and public-health signaling: Continued reiteration from leading public health authorities that EPA-registered actives—including DEET (at label concentrations), picaridin, IR3535 and recognized botanical actives—are considered safe and effective for pregnant women has tightened the margin for efficacy-driven products. This regulatory backdrop reduces asymmetric risk for manufacturers that prioritize labeled, evidence-based formulations.
Worldwide Mosquito Repellent Water For Pregnant Women Market -
Shifting consumer choice architecture: Expectant mothers are increasingly triaging product choices on evidence and skin compatibility, not just “natural” positioning. The market reward now accrues to formulations that deliver demonstrable protection and improved dermatological tolerability (e.g., combination with hydrating agents such as sodium hyaluronic acid), validated either through third-party efficacy claims or clinical/labeling support.
Worldwide Mosquito Repellent Water For Pregnant Women Market -
Channel acceleration and premiumization: Online discovery and pharmacy channels continue to outpace legacy mass channels for this sensitive-use category, enabling premium pricing for demonstrable safety claims and targeted communications to prenatal care communities.
-
Concentration and competitive dynamics: The category shows moderate concentration—the top three players account for a meaningful plurality and the top five approach half of market revenues—creating both challenges and openings for mid-sized innovators and private-label entrants seeking niche differentiation.
What PW Consulting’s Report Delivers — Practical, Transaction-Ready Modules
-
Executive dashboard: concise, board-level implications and scenario outputs tuned to 12–36 month planning windows.
-
Robust market sizing & forecast model: transparent methodology with historical reconciliation (2020–2025), base-year calibration (2025), and a probability-weighted forecast (2026–2032) with downloadable model inputs for client-level stress testing.
-
Regulatory and clinical risk matrix: side-by-side comparisons of active ingredients, label claims permitted under prevailing guidance, and an engagement roadmap for authorities and maternal-health stakeholders.
-
Go‑to‑market playbooks: channel prioritization matrices, promotional templates for pharmacy vs online, and messaging frameworks tailored to clinical gatekeepers (OB/GYNs, maternal health NGOs) and consumers.
-
Competitor playbooks and capability map: beyond logos—assessment of portfolio breadth, claims architecture, distribution strength, and white-space opportunities for product and geographic expansion.
-
Supply‑chain and input-cost scenarios: stress tests for raw-material volatility (actives and skin-conditioning excipients), supplier concentration, and recommended hedging strategies.
-
M&A and partnership candidates: prioritized shortlists and valuation sensitivities for bolt-on acquisitions, licensing, and co-development relationships across technology, clinical evidence, and channel scale.
Competitive Landscape — Profiles and Strategic Implications
-
PARA'KITO (France; US operations noted): A brand that has built affinity via family-oriented formats (sprays, roll-ons) and a lifestyle positioning. Their product narrative emphasizes broad family safety and convenience; for licensees and distributors, PARA'KITO’s multi-format approach presents a playbook for retail merchandising targeted at expectant mothers seeking non-intrusive daily-use options.
-
Sawyer Products (United States): Strong in evidence-backed chemistries, with offerings that include picaridin and DEET. Sawyer’s positioning demonstrates how a techno-clinical message—asserting specific actives and safety profiles—can successfully translate into trust within maternal health segments. Their clinical-oriented claims are a template for players aiming to convert clinician recommendation into retail uptake.
-
SC Johnson (OFF! brand, United States): An incumbent with scale and category trust. OFF! exemplifies how regulatory-compliant DEET-based products, when paired with aggressive trade and pharmacy channel strategies, maintain leadership in protective efficacy messaging. Their distribution muscle underscores the importance of channel relationships and SKU rationalization for new entrants.
-
Repel (Spectrum Brands, United States): Known for high-concentration DEET options and pregnancy-safety guidance, Repel’s portfolio strategies highlight occasions-of-use segmentation—offering both long-duration protection and formulations aimed at sensitive skin. Competitive pressure from such tiered portfolios raises the bar for entrants lacking clinical validation.
-
MURO (South Korea): An example of product differentiation through formulation finesse—integrating icaridin/picaridin with hydrating agents to address skin-sensitivity concerns in pregnant women and infants. MURO’s innovation trajectory signals the commercial value of combining efficacy with dermatological compatibility in markets that prioritize both.
Regulatory, Efficacy and Formulation Dynamics
-
Regulatory alignment is a market-making factor. Guidance from health authorities underscores the acceptability of several EPA-registered actives for use during pregnancy when applied per label; this reduces regulatory uncertainty for manufacturers that adopt evidence-based actives and labeling approaches.
-
DEET’s evidence base—when deployed at approved concentrations—continues to offer long-duration protection and substantial reassurance to clinicians and consumers. Meanwhile, picaridin and IR3535 broaden the product portfolio for formulators seeking DEET alternatives.
-
Formulation innovation is trending toward hybrid solutions: proven synthetics or validated actives paired with skin conditioners and humectants to improve tolerability. Products that can document both protection and dermatological safety will capture a premium within the pregnant-women segment.
Strategic Recommendations for 2026 Decision-Makers
-
Prioritize label-compliant, peer-supported actives: Invest in formulations that align with prevailing safety guidance. For new launches, secure independent efficacy verification and clinician endorsements before scaling promotion.
-
Invest in dermatological differentiation: Combine proven repellents with hydrating agents and emphasize skin-compatibility in claims to capture the expectant mother segment’s willingness to pay for tolerability and comfort.
-
Adopt a precision channel strategy: Use pharmacy and specialist channels to build clinical credibility; employ online platforms for education-led commerce that targets prenatal communities and subscription-based replenishment.
-
Hedge raw material exposure: Build dual-sourcing strategies for key actives and negotiate volume-based agreements for excipients critical to skin-friendly formulations.
-
Develop clinician engagement programs: Lightweight clinical studies, partnering with maternal health organizations, and clear point-of-care materials can convert clinician guidance into consumer demand.
-
Pursue focused M&A: Look for players with either differentiated formulation IP or direct-to-consumer traction in maternity communities to accelerate market entry without sacrificing clinical credibility.
-
Use scenario planning: Base-year 2025 calibration and the probabilistic forecast to stress-test portfolio decisions under disease-outbreak, raw-material shock, or regulatory-timing scenarios.
Why This Preview Matters — The Strategic Value of the Full Report
For senior strategy teams, the value of PW Consulting’s full study is procedural and tactical: it transforms headline growth figures into executable plans. The report couples a transparent market model (reconciling 2020–2025 history with a 2026 base) with granular demand drivers, trade-off analyses, and a competitive playbook that identifies where investment returns are highest. It also contains proprietary scorecards and a regulatory event tracker that enable companies to prioritize projects, allocate R&D budgets, and set commercialization timetables with confidence.
We intentionally limit the disclosure in this press release to preserve the full commercial utility of the segmentation matrices, SKU-level pricing curves, regional go-to-market prioritizations, and the detailed competitor scorecards contained in the paid report. Those granular outputs are designed to be operationalized directly into 2026 P&L planning and M&A diligence.
Next Steps
Leaders preparing their 2026 strategy for mosquito repellents aimed at pregnant women should use this preview as a tactical checklist: validate active-ingredient choices against current public-health guidance, upgrade formulations for skin compatibility, and push clinician and pharmacy engagement. For access to the full dataset, model files, and our prioritized playbooks, PW Consulting invites procurement and corporate-strategy teams to request the complete Worldwide Mosquito Repellent Water For Pregnant Women Market report and its annexes—equipped for immediate integration into 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Mosquito Repellent Water For Pregnant Women Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide LARC Market 2026 Preview: Strategic Imperatives from PW Consulting’s New Report
PW Consulting’s latest market study — Worldwide Long-Acting Reversible Contraception (LARC) Market — delivers an evidence-based roadmap for executives and investors preparing for the pivotal strategic choices of 2026. Anchored on a robust historical base (2020–2025) and forward-looking projections through 2032, the report quantifies the market’s size, momentum, and structural dynamics while translating those inputs into actionable options for product, commercial, regulatory, and supply-chain strategy.
Worldwide Long-Acting Reversible Contraception(LARC) Market
Macro snapshot that matters for 2026 planning
Key structural facts you can immediately act on: our market model estimates global LARC revenue at approximately USD 5.61 billion (Million USD unit basis) in the report’s base year (2025), following a steady rise from the early 2020s. The market is projected to expand at a compound annual growth rate (CAGR) of 6.4% over the forecast period (2026–2032), reaching an estimated USD 8.66 billion by 2032. The near-term projection for 2026 is consistent with this trajectory and signals a market that is growing fast enough to justify investment in scale, but mature enough to emphasize margin preservation and differentiation.
Worldwide Long-Acting Reversible Contraception(LARC) Market
Concentration metrics further shape competitive strategy: the market exhibits high incumbent strength at the top, with the three- and five-firm concentration ratios indicating that dominant manufacturers and established portfolios will continue to control a large share of revenues. This concentration creates both barriers and opportunities — a high entry bar for broad commercial rollouts, but a favorable environment for targeted innovation, partnerships, and niche players that can address unmet clinical, access, or cost gaps.
Worldwide Long-Acting Reversible Contraception(LARC) Market
Why 2026 is a decision-making inflection point
- Regulatory momentum and lifecycle extensions: Recent approvals that extend product life cycles (for example, implant duration extensions) materially change the unit economics and addressable patient-years per product. These shifts require immediate reassessment of forecasted utilization, replacement cycles, and warranty/service planning.
- IP and patent calendar: Key patent expirations are concentrated in the mid-2020s, creating an opening for generic entrants and alternative applicator or delivery innovations. Companies must reconcile near-term exclusivity benefits with medium-term commoditization risk when allocating R&D and commercial spend.
- Access and reimbursement environment: Strong health-economic evidence for LARC’s long-term cost-effectiveness continues to influence public procurement and private payer coverage. Organizations that proactively engage with reimbursement stakeholders and align pricing models to demonstrable lifetime cost savings will secure preferential placement in formularies and public tenders.
- Material and device innovation: Advances in non-hormonal copper device designs that reduce raw-material load while preserving efficacy, and improvements in insertion technology, are reshaping product differentiation and cost structures.
Competitive landscape — the playbook for incumbents and challengers
The market’s competitive picture is shaped by a mix of large multinational manufacturers, specialized women’s-health developers, and government-backed suppliers. Our report profiles each major participant, assessing portfolio depth, route-to-market, regulatory positioning, and recent strategic moves that bear on 2026 choices.
- Portfolio optimization is now table stakes: Global players with legacy hormonal intrauterine systems and implants remain the axis of competition, but the commercial calculus has shifted: duration extensions, device ergonomics, and delivery systems now contribute materially to lifetime value per patient. Firms must decide whether to compete on premium, differentiated offerings or expand lower-cost channels through licensing and partnerships.
- Licensing and M&A as de-risking tools: Recent high-profile licensing agreements demonstrate how firms can acquire rapid access to differentiated assets without full in-house development cost. Executives should view licensing not only as a revenue lever but as a strategic hedging instrument against accelerating technological shifts.
- Non-hormonal propositions are repositioning the field: The entry of next-generation copper IUDs with novel frames and reduced copper load introduces a clinically credible, potentially lower-cost alternative that will influence prescriber choice and public procurement policy. Suppliers in supply-constrained markets should re-evaluate raw-material sourcing and production footprints.
- Public-sector supply players remain critical partners: Government-owned and WHO-prequalified manufacturers will continue to be major fulfillers for public health programs. International manufacturers seeking public tenders must match price, quality, and supply reliability — and should be prepared to offer training and service packages to secure wide-scale adoption.
Regulatory and clinical dynamics to incorporate in 2026 roadmaps
- Regulatory approvals extending labeled duration of use for implants materially change demand cadence and replacement timing — this affects forecasting, warranty liability, and stock rotation strategies.
- Special regulatory controls, such as clinician training, certification, and REMS-like requirements for insertion and removal of specific implantable devices, raise the cost of adoption and create a role for manufacturers to provide certified training and support services.
- Evidence-based messaging about comparative efficacy (with LARC methods commonly exceeding 99% effectiveness in preventing pregnancy) underpins payer negotiation. Organizations should invest in real-world evidence generation and health-economic models for inclusion in tender bids and reimbursement dossiers.
Operational priorities — what to do in 2026
For management teams, the tactical implications of the report’s findings translate into a short list of high-priority initiatives that should be budgeted and launched in 2026:
- Reassess product life-cycle economics: Update unit demand models to incorporate extended labeled durations and potential shifts from repeat-procedures to longer single-device coverage.
- Execute a targeted licensing and partnering agenda: Identify candidate assets (device innovation, preloaded inserter systems, or low-copper designs) that can be licensed to accelerate time-to-market without full development risk.
- Strengthen market-access capabilities: Deploy health-economic dossiers that quantify lifetime cost offsets and align with public-payor procurement requirements; prepare modular pricing structures for low-resource vs. premium channels.
- Invest in clinician training and service infrastructure: For products with mandatory training or REMS-like requirements, supplier-provided training is a differentiator that reduces friction to adoption and supports premium positioning.
- Secure supply chains and raw-material strategies: Evaluate copper sourcing and alternative input strategies; ensure redundancy for critical components and consider vertical integration or strategic supplier contracts for high-volume scenarios.
- Plan for targeted geographic expansion, not blanket rollouts: Given concentration at the top and varying reimbursement landscapes, favor focused country-level launches where reimbursement and procurement pathways are favorable.
What PW Consulting’s report delivers — the practical content
The report is designed as a working toolkit for leadership teams. Highlights include:
- Comprehensive market-size model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario levers that allow finance and commercial teams to stress-test assumptions around duration extensions, price erosion, and public-procurement uptake.
- Competitive intelligence pack: detailed profiles of the major manufacturers, their regulatory status, patent timelines, and recent strategic transactions that materially affect competitive advantage.
- Regulatory and reimbursement tracker: a living inventory of label changes, REMS and training requirements, payer coverage trends, and public-health procurement guidelines across priority markets.
- Go-to-market playbooks: tailored routes for premium vs. access-focused launches, including tender submission templates, evidence-generation roadmaps, and clinician-training program outlines.
- Supply-chain and cost-to-serve maps: risk-graded supplier lists, raw-material sensitivity analysis, and manufacturing-scaling scenarios that quantify capital and operating impacts of volume growth.
- M&A and licensing framework: valuation heuristics, earn-out structures, and integration checklists to expedite deal execution while managing commercialization risk.
Case signals from recent industry developments
- Duration-extension approvals for certain implants directly improve lifetime revenue per patient and reduce replacement volumes. This is a critical input for 2026 financial planning
- New approvals and subsequent global licensing activity for next-generation non-hormonal IUDs have accelerated partner discussions; these moves demonstrate a pragmatic industry preference for licensing to fast-track differentiated, lower-cost options into broader markets.
- Patents related to legacy applicators and delivery systems create a narrow window for innovators to capture share before potential generic or alternative applicator strategies emerge — signaling an intensified M&A and licensing cadence in 2026.
- Manufacturers have begun to publish health-economic evidence supporting LARC’s long-term savings versus short-acting contraceptives; firms that do not build similar evidence stand to lose bargaining power in public tenders and payer negotiations.
How to use the report in your boardroom
Think of the PW Consulting LARC report as a decision accelerator: it converts market evolution into discrete choices and quantifies the trade-offs of each. For 2026 strategy cycles, use the report to:
- Reconcile product-portfolio choices with four-year rolling forecasts that incorporate regulatory and patent events;
- Prioritize funding to initiatives that protect margin (training, differentiated delivery) or reduce unit cost (manufacturing scale, raw-material strategy);
- Calibrate M&A and licensing appetite based on concentration dynamics and the cost of inaction as competitors pursue deals; and
- Design payer engagement plans built on defensible health-economic evidence rather than price-only competition.
Next steps and how to access the analysis
PW Consulting’s full report contains the granular segment-level and country-level datasets, scenario models, and executable templates that underlie the strategic recommendations summarized here. This release intentionally highlights the insights and directional conclusions that are most relevant to 2026 planning while reserving the detailed breakouts, financial tables, and country dashboards for the full report.
For access to the complete market model, competitive profiles, and go-to-market toolkits, please contact PW Consulting’s Life Sciences Practice or visit our report page to request the full Worldwide LARC Market study and the accompanying interactive forecast models.
For detailed analysis of this topic, please visit the official page: Worldwide Long-Acting Reversible Contraception(LARC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Food‑Grade Ammonium Chloride Market Poised to Grow at 4.12% CAGR from 2026–2032
By pmarketresearch, 2026-07-15
PW Consulting: Strategic Brief — Worldwide Food Grade Ammonium Chloride Market and Tactical Roadmap for 2026
PW Consulting today publishes a focused industry brief drawn from our full Worldwide Food Grade Ammonium Chloride Market report (base year 2025; historical 2020–2025; forecast 2026–2032). This briefing is intended as a strategic “preview trailer” for executives, investors and commercial leaders preparing for near-term decisions in 2026. We reveal high‑confidence macro trends, systemic risks and practical playbooks while intentionally reserving granular segmentation tables and proprietary scorecards for subscribers of the full study.
Worldwide Food Grade Ammonium Chloride Market
Macro snapshot: what the numbers tell senior teams
The market for food‑grade ammonium chloride has exhibited steady growth through the past business cycle and into the recovery phase. Our consolidated market sizing tracks from approximately USD 164.2 million in 2020 to USD 200.2 million in 2025, and our forecast extends to roughly USD 268.0 million by 2032. This trajectory reflects a compound annual growth rate (CAGR) of 4.12% across the 2026–2032 forecast window and underscores resilient demand from food applications, supported by pharmaceutical and speciality uses.
Worldwide Food Grade Ammonium Chloride Market
Concentration metrics indicate a moderately consolidated supply base: the top three producers capture under half of market revenues while the top five account for slightly more than half. For commercial strategists, this implies both predictable competitive behavior among incumbents and recurring opportunities for focused challengers that can deliver differentiated grade quality, regulatory credentials, or local logistics advantages.
Worldwide Food Grade Ammonium Chloride Market
Why this matters for 2026 decisions — five executive implications
- Commercial negotiation and pricing strategy: With growth steady but supply‑side sensitivities concentrated in feedstock inputs (notably ammonia and hydrochloric acid), procurement teams should adopt blended-sourcing strategies and renegotiation cadences that reflect regional price dispersion and pass‑through dynamics.
- Portfolio and grade prioritization: Food and pharma customers increasingly value certified high‑purity grades and anti‑caking formulations. R&D and product managers should prioritize grade certification roadmaps that align with buyer due‑diligence expectations in target markets.
- Capacity and CAPEX sequencing: Capacity additions must be staged against scenario stress tests for raw material shocks and trade friction. Capital allocation that favors modular, scalable lines will outperform monolithic expansions in an environment of feedstock volatility.
- Regulatory readiness and market access: Regulatory clarity—for example, recognition of ammonium chloride uses under US GRAS frameworks and extended EU authorizations for animal feed—reduces market access friction but raises compliance expectations. Compliance teams must lock in documentation and supply‑chain traceability ahead of customer audits.
- M&A and partnership screening: The market structure supports bolt‑on acquisitions for regional footprint and backward integration for feedstock security. Financial sponsors and corporate development teams should use scenario-based valuation models that incorporate feedstock price pass‑through and certification upgrade costs.
What the full report delivers — practical, actionable content
Our full report is designed as an operational toolset for 2026 planning, not just a desk reference. Key deliverables include:
- Dynamic market model (Excel) with historical time series (2020–2025) and a configurable forecast engine for 2026–2032 that allows users to stress test demand, price and margin assumptions.
- Price‑sensitivity and cost‑pass‑through templates linking ammonia/hydrochloric acid inputs to finished‑goods margins under alternative energy cost scenarios.
- Regulatory tracker and compliance matrix summarizing GRAS status, EU feed authorizations and regional documentation requirements—mapped to likely audit checklists used by major food manufacturers.
- Supply‑chain heatmap that identifies chokepoints (feedstock, logistics, packaging) and quantifies time‑to‑remedy for common mitigation measures (dual sourcing, buffer inventory, tolling arrangements).
- Competitive benchmarking pack with supplier scorecards, capability maps and a ranked shortlist for potential acquisition or JV targets based on technical competence, certification coverage and distribution strengths.
- Practical go‑to‑market playbooks for ingredient distributors and processors, including customer segmentation heuristics, margin models by sales channel, and sample commercial terms used by leading buyers.
- InvestorReady executive deck and slide bank to accelerate decision cycles for boards and PE sponsors pursuing consolidation or strategic growth investments.
These components were curated to convert analytics into executable decisions: renegotiated contracts, prioritized CAPEX, rapid certification programs, and live M&A screening—each backed by downloadable templates that reduce execution friction.
Competitive landscape — who matters and where strategic moves are happening
Industry participants range from diversified chemical majors to regional specialists. Our coverage highlights several players whose strategic moves and capabilities warrant close attention:
- BASF SE (Ludwigshafen, Germany): A global chemicals leader offering food and pharma‑grade ammonium chloride with applicable manufacturing and regulatory certificates. Recent capacity improvements in Ludwigshafen have increased output flexibility and improved grade quality—an important factor for buyers seeking scale and traceability.
- Jiangsu Khonor Chemicals (Jiangsu, China): A vertically integrated supplier with a broad grade portfolio across food, feed and pharma use cases. Their geographic cost advantage and certification reach make them a frequent contender in price‑sensitive contracts.
- Muby Chemicals (Mubychem Group, Mumbai, India): An established manufacturer of multiple pharmacopeial grades and anti‑caking variants; positioned as a preferred supplier when specialized formulations are required.
- Regional industrial producers and suppliers: Several Indian and European firms (including Tuticorin Alkali Chemicals, Tata Chemicals, Anmol Chemicals, CFL Chemische Fabrik Lehrte and Macco Organiques) play important roles for localized demand and specialized formulations. Their strengths lie in regulatory familiarity and proximity to FMCG and spice‑manufacturing clusters.
Notable recent developments that influenced our outlook include a product launch and certification by a large regional player in mid‑2025 aimed at updated international purity standards, and a prior capacity expansion by a major European operator that has altered regional competitive dynamics. These types of moves—capacity scaling and upgraded certification—are the primary vectors by which incumbent power shifts in this market.
Market dynamics, supply‑side risks and regulatory context
Strategic risk assessment requires careful attention to both physical supply chains and regulatory guardrails. On the supply side, ammonium chloride is primarily produced either by direct reaction of ammonia with hydrochloric acid or as a by‑product of certain soda ash processes. This production linkage creates second‑order exposure: price volatility in ammonia and hydrochloric acid—often tied to natural gas and global chemical cycles—transmits directly into finished‑goods economics.
Price dispersion across regions is material and persistent. For example, as of late 2025 there were significant per‑kilogram differences across major producing regions. These disparities create trade arbitrage opportunities but also invite regulatory scrutiny and potential trade remedies when supply imbalances persist.
On the regulatory front, important certainties reduce near‑term policy risk: in the United States, ammonium chloride is affirmed under GRAS uses for specific food functions (e.g., dough strengthening and leavening within current good manufacturing practice), and in the European Union authorization for certain ammonium chloride preparations in animal feed has been extended into the next decade. Nonetheless, companies must remain prepared for tightened documentation requests, chain‑of‑custody proofing and periodic re‑assessments of allowable use levels in target markets.
Recommended 90–180 day playbook for 2026
- 90 days: Run the report’s Excel stress tests against your current contracts; quantify exposure to upstream feedstock price swings and determine minimum margin thresholds for price pass‑through. Launch urgent supplier audits where documentation gaps exist.
- 180 days: Implement a prioritized CAPEX or contract strategy: (a) secure modular capacity expansions or tolling agreements where volume growth is clear; (b) pursue targeted supplier partnerships for certification upgrades; and (c) begin discrete M&A diligence on 2–3 regional specialists that close logistical or certification gaps.
Concluding view and how to obtain the full intelligence
For 2026, the food‑grade ammonium chloride market looks like a classic middle‑market chemical segment: predictable aggregate growth, meaningful regional price dispersion, and a competitive structure that rewards either scale or specialized differentiation. The decisive factor for commercial and investment success will be the combination of feedstock risk management, speed of certification and the ability to align commercial terms to evolving buyer due‑diligence standards.
PW Consulting’s full report contains the complete segmentation matrices, regional and application breakdowns, supplier scorecards, and the downloadable models referenced in this brief. Those granular tables and proprietary scenarios are intentionally withheld from this preview to preserve the operational utility of the full deliverable. For teams preparing strategic choices in 2026—whether contracting, investing, or integrating—access to the complete dataset and playbooks will materially shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Worldwide Food Grade Ammonium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.35% CAGR for Worldwide Dispute Advisory and International Arbitration Market Through 2032
By pmarketresearch, 2026-07-15
Worldwide Dispute Advisory and International Arbitration Market — Strategic Preview for 2026 Decision-Makers
Executive overview
In an era where cross-border commerce, geopolitics, and technology intersect with corporate strategy, dispute advisory and international arbitration have become board-level concerns. PW Consulting’s latest market study finds the worldwide dispute advisory and international arbitration market expanded to approximately USD 24.85 billion in 2025 and is forecast to grow to about USD 27.01 billion in 2026. With a compound annual growth rate (CAGR) of 6.35% across the 2026–2032 forecast period, the market is projected to approach the mid-USD 30 billions by the end of the decade. These headline metrics underscore a durable and expanding demand for high‑value advisory, expert evidence, and advocacy services.
Worldwide Dispute Advisory and International Arbitration Market
Why this report matters for 2026 strategic choices
For corporate legal teams, general counsel, risk officers, and external advisers, the 2026 planning cycle requires more than conventional inputs. Decisions on portfolio allocations, seat selection, dispute clause drafting, contingency budgeting, and operational resilience now hinge on integrated foresight across legal, regulatory, and technological vectors. Our report distills market-scale dynamics into actionable decision frames that align finance, operations, and compliance priorities. Key strategic value propositions include:
Worldwide Dispute Advisory and International Arbitration Market
- Evidence-based scenario planning calibrated to a market growing at a mid-single-digit CAGR, enabling realistic budgeting for dispute exposure and advisory spend.
- Decision matrices for choosing advisory mixes — forensic, technical, legal, and strategic — that optimize outcomes under different case profiles and enforcement risks.
- Practical playbooks for procurement and panel design that reconcile global reach with local expertise, while managing labour-cost drivers inherent in specialist arbitration staffing.
What the report contains: practical, transaction-ready tools
The study is not merely descriptive — it is operational. Designed for teams that must act, it delivers a suite of diagnostic and execution instruments, including:
Worldwide Dispute Advisory and International Arbitration Market
- Market sizing and trend narratives that translate macro indicators into likely fee pools and capacity constraints for 2026 planning.
- Scenario modelling modules to stress-test budgets and recovery expectations across contingency, insurance, and self-funded models.
- Vendor and counsel benchmarking templates that integrate capability, footprint, precedent strength, and user‑survey metrics to support panel selection and fee negotiation.
- Forensic and technical resourcing roadmaps — detailing staffing models, cost drivers, and evidence‑management touchpoints that control cycle time and costs without compromising outcome quality.
- Regulatory and data governance checklists tailored to arbitration contexts — covering cross-border data transfers, GDPR Article 32 considerations, and ICCA‑IBA guidance on electronic evidence.
- Emerging-issue playbooks addressing AI-assisted review, crypto-asset valuation, tariff-driven disputes, and ESG-related claims — each with tactical steps for preserving evidentiary integrity and enforceability.
- Actions lists for seat-selection and enforcement strategy that map seats, enforcement corridors, and sovereign-risk considerations into practical litigation-risk matrices.
Competitive landscape and strategic implications
The market retains a mix of global law firms, specialized boutiques, and multidisciplinary professional-services firms. Aggregate concentration remains modest: leading global players command meaningful franchise value but do not dominate the market. That fragmentation creates both competitive opportunity and client complexity — an environment where capability alignment, sector expertise, and integrated service models matter as much as brand.
Our comparative assessment profiles firms that will shape outcomes in 2026 and beyond:
- Freshfields Bruckhaus Deringer — recognized for its pre‑contentious strategic advice and deep capabilities in energy, infrastructure, and public international law. Corporates facing sovereign or treaty-linked disputes will find their strengths particularly relevant.
- White & Case — noted for comprehensive global arbitration coverage across commercial and investor-state matters and for thought leadership on user preferences. Their global casework supports complex cross-border coordination needs.
- Herbert Smith Freehills Kramer — strong Asia‑Pacific presence and a track record on high-value mandates, making them a natural choice where regional depth and seat‑specific experience are determinative.
- King & Spalding — frequently ranked highly for energy and infrastructure disputes, offering a balance of advocacy firepower and sectoral focus useful for project sponsors and lenders.
- Debevoise & Plimpton — a Band 1 practice for high-value commercial and investor-state arbitration, with particular strength in energy and public international law.
- Three Crowns LLP — a boutique that packs specialist public international law and arbitration expertise into lean, high-impact teams for high-stakes matters.
- Quinn Emanuel — noted for aggressive, litigation-first advocacy and recognized by recent awards for international arbitration excellence.
- Baker McKenzie and Squire Patton Boggs — global platforms offering end-to-end solutions across investor-state, post‑M&A, and commercial disputes, valuable where integrated regulatory and transactional advice is required.
- Cleary Gottlieb — notable for trend analysis and thought leadership on evolving issues (AI, tariffs, crypto) and for handling regulatory and securities-related cross-border conflicts.
- PwC — the leading multidisciplinary provider in dispute advisory services for forensic accounting, valuation, and expert evidence, often working in tandem with law‑firm counsel on complex technical questions.
For in-house teams, the strategic implication is clear: vendor selection must be multidimensional — combining sector credibility, arbitral-institution track records, forensic depth, and technological capability. Our vendor‑benchmarking framework maps these attributes to typical dispute archetypes so procurement leads can design fit‑for‑purpose panels that control cost and preserve optionality.
Recent market signals and regulatory context shaping 2026
Several industry developments in late 2025 and early 2026 sharpen the practical contours of the market:
- Institutional caseloads and jurisdictional diversity continue to grow, reinforcing the internationality of arbitrations and driving demand for cross-border advisory coordination.
- Recognition and ranking updates from leading directories continue to influence market access and referral patterns, affecting how clients shortlist counsel for complex mandates.
- Thought leadership by top firms highlights an uptick in commercial arbitrations, enforcement actions against sovereigns, and disputes driven by tariffs and supply‑chain realignments.
- Regulatory and data‑privacy guidance — notably the ICCA‑IBA and GDPR frameworks — are now central to evidence strategy and e‑discovery hygiene in arbitration contexts.
- Technological adoption: AI tools for case analysis and evidence review are becoming mainstream, but their integration raises procedural and admissibility questions that counsel must manage proactively.
Implications for budgeting, talent, and operational design
Two operational realities are shaping provider economics and client choices in 2026. First, specialized human labor — experienced arbitration counsel and expert witnesses — remains the primary cost driver. Second, firms that successfully combine global resourcing with scalable technology platforms gain measurable edges in cycle time and cost predictability.
For clients, this means three practical priorities:
- Adopt layered staffing models that mix senior strategic counsel with technically expert mid‑level teams and flexible pod-based forensic resources to manage fees without compromising quality.
- Invest in early-stage dispute triage and forensic workstreams to reduce downstream uncertainty and improve valuation realism for settlement vs. litigation decisions.
- Incorporate technology gates into procurement contracts — defining acceptable AI tools, data security protocols, and evidence-retention standards to avoid later admissibility risks.
How to use the report in your 2026 playbook
The report is designed as a living decision tool for the 2026 fiscal year and beyond. Use it to:
- Calibrate your dispute budget to market-scale forecasts and scenario outputs rather than historical spend alone.
- Rationalize panel design with our benchmarking outputs; align counsel selection to dispute archetypes and enforcement geographies.
- Operationalize AI and data-governance checklists within your external counsel mandates to protect confidentiality and evidentiary integrity.
- Run the included stress tests to evaluate contingency funding, insurance layering, and strategic settlement thresholds under multiple macro scenarios.
Next steps and access to full intelligence
This release follows the “trailer” principle: it demonstrates the analytical depth and operational focus of PW Consulting’s study while reserving the full granular breakouts, detailed regional and service-type splits, and model spreadsheets for the full report. Subscribers and clients receive the complete set of downloadable models, vendor scorecards, and bespoke advisory sessions to translate findings into executable plans.
For teams preparing 2026 budgets, restructuring dispute reserves, or selecting new counsel, the full report will be indispensable. PW Consulting stands ready to run tailored workshops that apply the study’s modules to your company’s dispute portfolio and growth plans.
Concluding perspective
Dispute advisory and international arbitration are no longer back-office contingencies — they are strategic levers. With market size expanding, increasing institutional caseloads, and accelerating technological and regulatory change, organizations that align legal strategy, procurement, and technology in 2026 will materially improve their outcomes and control costs. PW Consulting’s market study offers the forecasted scale, competitive mapping, and operational tools that in-house teams and advisers need to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Dispute Advisory and International Arbitration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Radiator Flushing Chemicals Market Reaches USD 225.5 Million in 2025, Poised for 5.48% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Radiator Flushing Chemicals Market — Strategic Outlook for 2026 Decisions
As companies plan resource allocation, M&A, and product launches for 2026, they need a concise, actionable view of the radiator flushing chemicals market that balances conviction with prudent uncertainty. PW Consulting’s latest market intelligence positions senior leaders to make those calls with confidence: the global market for radiator flushing chemicals reached approximately USD 225.5 Million in our base year (2025) and, guided by macro drivers and material-cost dynamics, is modeled to expand at a compound annual growth rate (CAGR) of 5.48% across our 2026–2032 forecast horizon, reaching roughly USD 327.6 Million by 2032. This briefing summarizes the strategic implications our full report unpacks in operational detail and highlights the specific decision levers enterprises should prioritize in 2026.
Worldwide Radiator Flushing Chemicals Market
Why this market matters to corporate strategy in 2026
At first glance radiator flushing chemicals sit at the intersection of automotive aftercare, heavy equipment maintenance, and industrial cooling-system reliability. But the market’s strategic relevance in 2026 flows from three forces coming into alignment:
Worldwide Radiator Flushing Chemicals Market
- Maintenance-as-differentiator: OEMs, fleet operators and aftermarket service chains are increasingly viewing maintenance programs (including coolant and radiator health) as channels for cost reduction, uptime improvement and customer retention.
- Input-cost and formulation pressure: Upstream feedstock volatility (notably ethylene glycol) and specialty chemical costs (including phosphoric acid) continue to shape margin dynamics and incentivize formulation innovation and supplier hedging.
- Regulatory and infrastructure shifts: New or strengthened regulation—ranging from U.S. federal refrigerant management rules now in force to building code updates that change EV-charging and ventilation dynamics—has indirect but material effects on service patterns, component lifecycles and parts-replacement cadences.
For executives, that combination means radiator-flush manufacturers, distributors and end-user fleets must translate market growth into concrete choices: where to invest in R&D, how to structure procurement, how to price value-added services, and whether to pursue consolidation or partnerships to protect margin and market access.
Worldwide Radiator Flushing Chemicals Market
Market structure and competitive implications
Our concentration analysis shows a market that is neither atomized nor locked: leading players capture a meaningful share, but sufficient space exists for regional specialists, private-label programs and technical innovators. The top three players account for a material, but not overwhelming, portion of sales, and the top five increase that concentration further—conditions that favor both targeted M&A and aggressive channel strategies.
Key competitive archetypes we profile in the full study:
- Large brand incumbents with broad aftermarket distribution and integrated service offerings. These firms leverage retail shelf presence, service-bay relationships and brand trust to maintain volume and premium pricing.
- Technical formulators and specialist suppliers focused on performance chemistry and OEM/industrial approvals—positioned to win fleet and OEM-specified programs where performance and compatibility are paramount.
- Regional formulators and private-label manufacturers with deep local procurement advantages and cost structures tailored to price-sensitive buyers.
Representative company profiles in the report span these archetypes and include legacy household names and technical specialists. Our competitive chapter examines their product positioning, go-to-market motions, channel economics and recent strategic moves—arming buyers and sellers with the context needed to evaluate partnership or M&A prospects in 2026.
Input-cost dynamics: what the numbers mean for margins and pricing
Raw-material trajectories are central to near-term margin risk. Ethylene glycol—an upstream feedstock influential for coolant-related formulations—experienced a period of elevated prices early in 2025 followed by a decline and a year-end rebound; our market-source consensus for 2026 anticipates initial weakness and then range-bound stability with typical levels around 4,000–4,400 RMB/ton amid ample supply. Separately, phosphoric acid pricing in early 2026 shows geographic variation (with prices reported at different levels across North America, Europe, Northeast Asia and Africa), underscoring regional input-cost differentials for manufacturers with geographically dispersed sourcing.
Operational takeaway for procurement and pricing teams: establish dual-track hedging and flexibility in supplier contracts now. Manufacturers with rigid single-source exposure risk margin erosion; distributors and private-label partners should prioritize formulations that tolerate modest raw-material price swings or allow rapid reformulation to protect gross margin.
Regulatory and infrastructure catalysts
Two regulatory developments merit explicit attention for 2026 planning. First, tighter federal handling rules for reclaimed refrigerants have implications across aftermarket service workflows and technician training budgets; compliance-driven service-protocol changes can alter the economics and cadence of maintenance visits. Second, building-code updates in leading jurisdictions (including expanded EV charging and ventilation rules) are shifting vehicle use patterns and service-site infrastructure—indirectly changing where and how thermal-management maintenance is performed. Our report translates these legal changes into practical checklists and scenario adjustments for product liability, service SOPs and technician certification investments.
Actionable plays for 2026 — prioritized
From our strategy work with manufacturers, distributors and fleets, PW Consulting recommends five prioritized plays to convert market growth into commercial advantage in 2026:
- Procurement resilience: renegotiate supply agreements with flexible volume bands, secure alternate feedstock sources, and institute a lightweight price-pass mechanism to protect margins during short-term feedstock volatility.
- Formulation stratification: maintain a core brand line for retail customers while accelerating development of higher-value, OEM-compliant formulations and service-bay concentrates that command premium margins and deeper customer lock-in.
- Service integration: build bundled maintenance offers (coolant chemistry + diagnostic + scheduling) for fleets and dealer networks to capture adjacent service revenue and improve retention.
- Selective M&A and partnerships: target bolt-on acquisitions in regional markets where distribution is fragmented or in technology pockets (bio-based chemistries, rapid-descaling) to accelerate capability without heavy greenfield investment.
- Regulatory-ready operations: implement compliance playbooks and training modules addressing recent refrigerant and building-code changes, minimizing service interruptions and liability exposure.
What PW Consulting’s full report delivers (practical components)
The published study is designed as a decision-making toolkit for 2026 and beyond. Highlights include:
- Quantified market model: annual historical and forecast revenue model with bottom-up and top-down reconciliations, scenario runs (base, upside, downside) and sensitivity levers for input-cost and fleet-utilization variables.
- Competitive intelligence packet: 10 in-depth company dossiers, product maps, channel economics, pricing matrices and capability heatmaps for rapid benchmarking.
- Regulatory impact assessment: jurisdiction-level implications, compliance cost estimates and a step-by-step operational compliance checklist.
- Procurement playbook: supplier scorecards, hedging templates, total-cost-of-ownership calculators and supplier-disruption contingency plans.
- M&A and partnership screening: quantitative target-scoring model, integration risk checklist and a shortlist of acquisition archetypes matched to strategic objectives.
- Commercial execution tools: go-to-market playbooks for retail, fleet and OEM channels, including bundling strategies, margin waterfall templates and KPIs for 90/180/360-day rollout plans.
Importantly, while this briefing highlights high-level market sizing and growth trajectory, the full report contains the granular segmentation, regional splits, product-chemistry breakdowns and absolute-dollar benchmarks that underpin the strategic tools above. That granular intelligence is intentionally gated to enable bespoke advisory engagements and to preserve the integrity of our benchmarking datasets.
Competitive highlights — what to watch in 2026
Our competitor analysis identifies three near-term behaviors likely to shape the competitive landscape in 2026:
- Brand incumbents doubling down on service integration: Expect established aftermarket names to increasingly bundle radiator flush products with service-bay programs and diagnostics to defend retail share and secure recurring revenue.
- Technical suppliers driving specification wins: Companies focused on performance chemistry (including rapid-flush and non-acidic formulations) will pursue fleet and OEM approvals, leveraging technical credentials to capture higher-margin contracts.
- Regional players exploiting localized cost advantages: In markets with distinct feedstock pricing or regulatory profiles, nimble local producers will push private-label and distributor partnerships to capture price-sensitive demand.
We analyze representative firms across these behaviors in the full report, mapping product innovations to customer segments and quantifying likely revenue upside for strategic moves such as expanding service partnerships, launching OEM-compatible formulations, or executing targeted tuck-in acquisitions.
Next steps for leaders
For C-suite and commercial leaders preparing 2026 plans, prioritize three immediate actions based on our findings: 1) run a rapid procurement stress-test against the report’s sensitivity scenarios to identify margin pressure points; 2) pilot a bundled maintenance offering with one fleet or dealer partner to validate pricing and operational workflows; and 3) initiate a focused due-diligence pipeline of regional acquisition targets or technical partners aligned with your desired route-to-market.
PW Consulting’s full Worldwide Radiator Flushing Chemicals Market report is structured to support those actions with executable tools, verified datasets and a shortlist of strategic options tailored to your corporate objectives. For organizations that need hands-on implementation support, our advisory teams are available to convert the report’s insights into a prioritized 90-day action plan.
To access granular segmentation, regional breakdowns, and the complete set of decision-support tools referenced here, visit our report page or contact PW Consulting’s industry desk to schedule a briefing and bespoke modeling session.
For detailed analysis of this topic, please visit the official page: Worldwide Radiator Flushing Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com