

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide PEI Films Market Poised for Robust Expansion at a 7.12% CAGR, New Report Finds

PW Consulting: Strategic Outlook — Worldwide Polyetherimide (PEI) Films Market Through 2032
As organizations position product roadmaps and capital allocation for 2026, the polyetherimide (PEI) films market is emerging as a quietly strategic arena. Our latest PW Consulting report — based on a rigorous five-year historical review and a seven-year forecast horizon — maps the market’s structure, supply-chain fault lines, regulatory inflection points, and competitor plays that will determine which manufacturers, converters, and end-users capture disproportionate value through the next business cycle.
Worldwide Polyetherimide (PEI) Films Market
Executive snapshot: scale, trajectory, and concentration
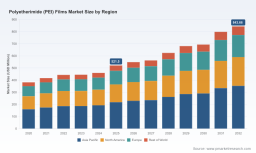
PEI films are now a mid-sized specialized polymer market with measurable scale and attractive growth fundamentals. Using 2025 as the base year, PW Consulting estimates the market value at approximately USD 521.5 Million (revenue, USD Million). Under the assumptions and scenarios modelled in this study, the market grows at a compound annual growth rate (CAGR) of 7.12% across the 2026–2032 forecast period, targeting a near-term seven-year market value that materially exceeds current run-rates.
Worldwide Polyetherimide (PEI) Films Market
Market concentration is meaningful: the top three players account for a majority share, and the top five approach near-complete control of the competitive landscape. This structure creates three practical realities for corporate strategists: (1) incumbents enjoy scale economies and technical validation advantages, (2) niche entrants can thrive with differentiated formulations or service models, and (3) M&A or strategic partnerships remain high-impact levers for gaining access to qualified material supply and application know-how.
Worldwide Polyetherimide (PEI) Films Market
Why PEI films matter to 2026 strategies
-
High-performance polymer positioning: PEI films combine heat resistance, dielectric properties, and thin-gauge form factors. These attributes make the material an enabler across demanding applications where qualification cycles are long and material change is non-trivial. For product teams planning 2026 rollouts, material selection decisions made today will lock in cost, performance, and qualification timelines for several product generations.
-
Value capture through application engineering: Firms that invest in application-specific grades and conversion capabilities can convert structural polymer demand into differentiated, higher-margin film solutions. Technical depth in film processing and tailored formulations creates defensible customer relationships, especially in industries with stringent fire, thermal, and outgassing requirements.
-
Supply-chain and input-cost volatility: Feedstock tightness and price inflation upstream have real-time implications. For instance, a key PEI monomer experienced double-digit price escalation in Asia in late 2024, a dynamic that reverberates through producer margins and conversion economics. Companies that proactively hedge, qualify alternate feedstock sources, or integrate upstream will be better positioned in 2026.
Regulatory and standards dynamics shaping product strategy
Regulatory compliance and sectoral standards are decisive variables in the PEI films market. Several contemporary developments are particularly relevant to 2026 decision-making:
-
Flammability and aerospace certification: Modern PEI films are capable of achieving stringent flammability ratings at thin gauges, enabling use in weight-sensitive aerospace and avionics architectures. For producers and Tier-1 suppliers, readiness to support aerospace qualification protocols is a commercial advantage.
-
Chemical migration and materials restrictions: Certain PEI grades comply with restrictive substance frameworks relevant to food contact and consumer safety. The convergence of end-market expectations and regulatory scrutiny requires robust compliance documentation and testing programs — an often-underestimated barrier to market entry for smaller converters.
Competitive landscape — what differentiates winners
Our report devotes extensive coverage to corporate strategy and capability mapping. Three archetypal players illustrate the competitive contours:
-
SABIC (Riyadh, Saudi Arabia): A global leader in technical PEI films, SABIC’s product portfolio and material validation footprint across aerospace, electronics, and medical sectors provide a high bar for scale and technical certification. Their thin-gauge offerings and thermal performance benchmarks underscore the premium positioning incumbents enjoy in certified markets.
-
Ensinger GmbH (Nufringen, Germany): Ensinger represents a technical-specialist model focused on tailored film and sheet products for demanding automotive, electronics, and medical applications. Close customer collaboration, custom thicknesses, and application engineering are the hallmarks of this approach.
-
RTP Company (Winona, Minnesota, USA): RTP embodies a differentiated-compounding play, offering custom-formulated PEI films for niche electrical insulation and flexible circuitry applications. Their competency in compounding and specialty grades highlights the role of formulation flexibility as an entry route into targeted high-value use cases.
The market’s competitive balance — with concentrated leaders and agile specialists — suggests a bifurcated strategy set for 2026: scale-driven incumbents will continue to defend specification-intensive segments, while nimble specialists can win through customization, fast qualification support, and co-development with OEMs.
Supply-chain risks and mitigation tactics
Two supply-side realities will shape corporate risk registers in 2026:
-
Upstream feedstock tightness and price pass-through: The market saw notable monomer price pressure in 2024. Material buyers should embed feedstock sensitivity analyses into sourcing strategies and consider long-term contracts, dual-sourcing, or backward integration where scale and regulatory feasibility permit.
-
Qualification lead times: End-market qualification windows — particularly in aerospace and medical segments — can be multi-year endeavors. Suppliers that provide comprehensive validation documentation, accelerated testing services, and pre-qualified material kits will shorten customer adoption cycles and capture premium share.
Strategic imperatives for decision-makers planning in 2026
Building on our quantitative forecasting and qualitative interviews across the value chain, PW Consulting recommends four high-impact moves for companies developing 2026 strategies:
-
Prioritize qualification-capability investments: Allocate budget to testing labs, flame- and toxicity-testing capacity, and accelerated ageing protocols. These assets shorten sales cycles in aerospace, defense, and medical segments where regulatory certainty drives procurement.
-
Hedge or diversify feedstock exposure: Given the recent monomer price volatility, establish a layered procurement strategy that combines strategic contracts, geographic diversification, and potential collaboration with monomer producers to secure competitive input costs.
-
Pursue targeted M&A or JV activity to accelerate market entry: For companies seeking volume or certification uplift, acquiring a converter with established aerospace or electronics approvals can shortcut multi-year organic efforts. Conversely, niche specialists should evaluate partnerships that expand go-to-market footprints without diluting technical focus.
-
Differentiate through services: Offer engineering consultancy, custom lamination, or integration services (e.g., flexible circuit lamination or EMI shielding assemblies). Value-added services convert material sales into longer-term contracts and higher lifetime customer value.
Report composition — what PW Consulting delivers
The full PW Consulting report translates these strategic implications into actionable tools for executives and investment committees. Highlights include:
-
Quantitative market model (USD Million) with historical reconciliation (2020–2025) and a detailed forecast through 2032, stress-tested across demand and price scenarios.
-
Competitive landscaping, capability maps, and profiled playbooks for leading producers and specialty converters — including go-to-market differentiation, validation credentials, and technology roadmaps.
-
Risk matrices covering supply-chain exposure, regulatory trajectories, and substitution threats, alongside mitigation playbooks tailored to strategic archetypes (incumbent manufacturer, specialty converter, and OEM-integrator).
-
Go-to-market implications for product managers, procurement teams, and corporate development groups — including a prioritized list of pilot use-cases and vendor selection criteria for 2026 engagements.
In keeping with the “trailer” approach, this release purposefully outlines strategic contours and market-scale metrics to inform executive decision-making, while detailed regional, type, and application-level splits remain available exclusively in the full report. These deeper breakdowns are essential for deal structuring, capex prioritization, and targeted go-to-market plans — and are therefore reserved for subscribers and report purchasers.
How to use this insight in 2026 planning cycles
For product leaders and corporate strategists preparing 2026 roadmaps, the PEI films sector presents a blend of steady growth and high entry barriers. Use the forecast as a gating input to strategic choices: whether to onboard PEI films in next-generation products, to invest in conversion capacity, or to pursue vertical scale through acquisition. Balance the revenue growth potential surfaced by the 7.12% CAGR against supply-side risk and certification timeframes to prioritize capital and hiring decisions.
PW Consulting is prepared to support customized scenario modelling, supplier due diligence, and target screening for M&A or JV opportunities. Our modular advisory scope includes rapid 90-day market-entry playbooks and longer-term integration planning for firms seeking to accelerate capability build-out.
Concluding perspective
The PEI films market is not a mass-market polymer opportunity; it is a high-value, specification-driven arena where technical capability, certification readiness, and supply resilience determine winners. The market’s trajectory from a solid 2025 base toward considerably larger volumes by 2032 creates strategic incentives for focused investment, but also demands disciplined risk management. For executives finalizing 2026 budgets, the choice is clear: treat PEI films as a strategic enabler within high-performance product lines — and plan with the precision that their qualification and procurement complexities require.
To access the full PW Consulting Worldwide Polyetherimide (PEI) Films Market report, including granular regional, type, and application breakdowns that support transactional and operational decision-making, contact our market intelligence team or visit the PW Consulting publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Polyetherimide (PEI) Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com