

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Food‑Grade Ammonium Chloride Market Poised to Grow at 4.12% CAGR from 2026–2032

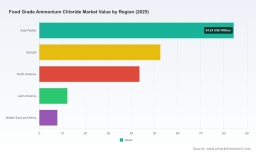
PW Consulting: Strategic Brief — Worldwide Food Grade Ammonium Chloride Market and Tactical Roadmap for 2026
PW Consulting today publishes a focused industry brief drawn from our full Worldwide Food Grade Ammonium Chloride Market report (base year 2025; historical 2020–2025; forecast 2026–2032). This briefing is intended as a strategic “preview trailer” for executives, investors and commercial leaders preparing for near-term decisions in 2026. We reveal high‑confidence macro trends, systemic risks and practical playbooks while intentionally reserving granular segmentation tables and proprietary scorecards for subscribers of the full study.
Worldwide Food Grade Ammonium Chloride Market
Macro snapshot: what the numbers tell senior teams
The market for food‑grade ammonium chloride has exhibited steady growth through the past business cycle and into the recovery phase. Our consolidated market sizing tracks from approximately USD 164.2 million in 2020 to USD 200.2 million in 2025, and our forecast extends to roughly USD 268.0 million by 2032. This trajectory reflects a compound annual growth rate (CAGR) of 4.12% across the 2026–2032 forecast window and underscores resilient demand from food applications, supported by pharmaceutical and speciality uses.
Worldwide Food Grade Ammonium Chloride Market
Concentration metrics indicate a moderately consolidated supply base: the top three producers capture under half of market revenues while the top five account for slightly more than half. For commercial strategists, this implies both predictable competitive behavior among incumbents and recurring opportunities for focused challengers that can deliver differentiated grade quality, regulatory credentials, or local logistics advantages.
Worldwide Food Grade Ammonium Chloride Market
Why this matters for 2026 decisions — five executive implications
- Commercial negotiation and pricing strategy: With growth steady but supply‑side sensitivities concentrated in feedstock inputs (notably ammonia and hydrochloric acid), procurement teams should adopt blended-sourcing strategies and renegotiation cadences that reflect regional price dispersion and pass‑through dynamics.
- Portfolio and grade prioritization: Food and pharma customers increasingly value certified high‑purity grades and anti‑caking formulations. R&D and product managers should prioritize grade certification roadmaps that align with buyer due‑diligence expectations in target markets.
- Capacity and CAPEX sequencing: Capacity additions must be staged against scenario stress tests for raw material shocks and trade friction. Capital allocation that favors modular, scalable lines will outperform monolithic expansions in an environment of feedstock volatility.
- Regulatory readiness and market access: Regulatory clarity—for example, recognition of ammonium chloride uses under US GRAS frameworks and extended EU authorizations for animal feed—reduces market access friction but raises compliance expectations. Compliance teams must lock in documentation and supply‑chain traceability ahead of customer audits.
- M&A and partnership screening: The market structure supports bolt‑on acquisitions for regional footprint and backward integration for feedstock security. Financial sponsors and corporate development teams should use scenario-based valuation models that incorporate feedstock price pass‑through and certification upgrade costs.
What the full report delivers — practical, actionable content
Our full report is designed as an operational toolset for 2026 planning, not just a desk reference. Key deliverables include:
- Dynamic market model (Excel) with historical time series (2020–2025) and a configurable forecast engine for 2026–2032 that allows users to stress test demand, price and margin assumptions.
- Price‑sensitivity and cost‑pass‑through templates linking ammonia/hydrochloric acid inputs to finished‑goods margins under alternative energy cost scenarios.
- Regulatory tracker and compliance matrix summarizing GRAS status, EU feed authorizations and regional documentation requirements—mapped to likely audit checklists used by major food manufacturers.
- Supply‑chain heatmap that identifies chokepoints (feedstock, logistics, packaging) and quantifies time‑to‑remedy for common mitigation measures (dual sourcing, buffer inventory, tolling arrangements).
- Competitive benchmarking pack with supplier scorecards, capability maps and a ranked shortlist for potential acquisition or JV targets based on technical competence, certification coverage and distribution strengths.
- Practical go‑to‑market playbooks for ingredient distributors and processors, including customer segmentation heuristics, margin models by sales channel, and sample commercial terms used by leading buyers.
- InvestorReady executive deck and slide bank to accelerate decision cycles for boards and PE sponsors pursuing consolidation or strategic growth investments.
These components were curated to convert analytics into executable decisions: renegotiated contracts, prioritized CAPEX, rapid certification programs, and live M&A screening—each backed by downloadable templates that reduce execution friction.
Competitive landscape — who matters and where strategic moves are happening
Industry participants range from diversified chemical majors to regional specialists. Our coverage highlights several players whose strategic moves and capabilities warrant close attention:
- BASF SE (Ludwigshafen, Germany): A global chemicals leader offering food and pharma‑grade ammonium chloride with applicable manufacturing and regulatory certificates. Recent capacity improvements in Ludwigshafen have increased output flexibility and improved grade quality—an important factor for buyers seeking scale and traceability.
- Jiangsu Khonor Chemicals (Jiangsu, China): A vertically integrated supplier with a broad grade portfolio across food, feed and pharma use cases. Their geographic cost advantage and certification reach make them a frequent contender in price‑sensitive contracts.
- Muby Chemicals (Mubychem Group, Mumbai, India): An established manufacturer of multiple pharmacopeial grades and anti‑caking variants; positioned as a preferred supplier when specialized formulations are required.
- Regional industrial producers and suppliers: Several Indian and European firms (including Tuticorin Alkali Chemicals, Tata Chemicals, Anmol Chemicals, CFL Chemische Fabrik Lehrte and Macco Organiques) play important roles for localized demand and specialized formulations. Their strengths lie in regulatory familiarity and proximity to FMCG and spice‑manufacturing clusters.
Notable recent developments that influenced our outlook include a product launch and certification by a large regional player in mid‑2025 aimed at updated international purity standards, and a prior capacity expansion by a major European operator that has altered regional competitive dynamics. These types of moves—capacity scaling and upgraded certification—are the primary vectors by which incumbent power shifts in this market.
Market dynamics, supply‑side risks and regulatory context
Strategic risk assessment requires careful attention to both physical supply chains and regulatory guardrails. On the supply side, ammonium chloride is primarily produced either by direct reaction of ammonia with hydrochloric acid or as a by‑product of certain soda ash processes. This production linkage creates second‑order exposure: price volatility in ammonia and hydrochloric acid—often tied to natural gas and global chemical cycles—transmits directly into finished‑goods economics.
Price dispersion across regions is material and persistent. For example, as of late 2025 there were significant per‑kilogram differences across major producing regions. These disparities create trade arbitrage opportunities but also invite regulatory scrutiny and potential trade remedies when supply imbalances persist.
On the regulatory front, important certainties reduce near‑term policy risk: in the United States, ammonium chloride is affirmed under GRAS uses for specific food functions (e.g., dough strengthening and leavening within current good manufacturing practice), and in the European Union authorization for certain ammonium chloride preparations in animal feed has been extended into the next decade. Nonetheless, companies must remain prepared for tightened documentation requests, chain‑of‑custody proofing and periodic re‑assessments of allowable use levels in target markets.
Recommended 90–180 day playbook for 2026
- 90 days: Run the report’s Excel stress tests against your current contracts; quantify exposure to upstream feedstock price swings and determine minimum margin thresholds for price pass‑through. Launch urgent supplier audits where documentation gaps exist.
- 180 days: Implement a prioritized CAPEX or contract strategy: (a) secure modular capacity expansions or tolling agreements where volume growth is clear; (b) pursue targeted supplier partnerships for certification upgrades; and (c) begin discrete M&A diligence on 2–3 regional specialists that close logistical or certification gaps.
Concluding view and how to obtain the full intelligence
For 2026, the food‑grade ammonium chloride market looks like a classic middle‑market chemical segment: predictable aggregate growth, meaningful regional price dispersion, and a competitive structure that rewards either scale or specialized differentiation. The decisive factor for commercial and investment success will be the combination of feedstock risk management, speed of certification and the ability to align commercial terms to evolving buyer due‑diligence standards.
PW Consulting’s full report contains the complete segmentation matrices, regional and application breakdowns, supplier scorecards, and the downloadable models referenced in this brief. Those granular tables and proprietary scenarios are intentionally withheld from this preview to preserve the operational utility of the full deliverable. For teams preparing strategic choices in 2026—whether contracting, investing, or integrating—access to the complete dataset and playbooks will materially shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Worldwide Food Grade Ammonium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com