

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Radiator Flushing Chemicals Market Reaches USD 225.5 Million in 2025, Poised for 5.48% CAGR Through 2032

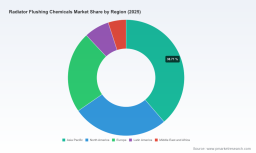
Worldwide Radiator Flushing Chemicals Market — Strategic Outlook for 2026 Decisions
As companies plan resource allocation, M&A, and product launches for 2026, they need a concise, actionable view of the radiator flushing chemicals market that balances conviction with prudent uncertainty. PW Consulting’s latest market intelligence positions senior leaders to make those calls with confidence: the global market for radiator flushing chemicals reached approximately USD 225.5 Million in our base year (2025) and, guided by macro drivers and material-cost dynamics, is modeled to expand at a compound annual growth rate (CAGR) of 5.48% across our 2026–2032 forecast horizon, reaching roughly USD 327.6 Million by 2032. This briefing summarizes the strategic implications our full report unpacks in operational detail and highlights the specific decision levers enterprises should prioritize in 2026.
Worldwide Radiator Flushing Chemicals Market
Why this market matters to corporate strategy in 2026
At first glance radiator flushing chemicals sit at the intersection of automotive aftercare, heavy equipment maintenance, and industrial cooling-system reliability. But the market’s strategic relevance in 2026 flows from three forces coming into alignment:
Worldwide Radiator Flushing Chemicals Market
- Maintenance-as-differentiator: OEMs, fleet operators and aftermarket service chains are increasingly viewing maintenance programs (including coolant and radiator health) as channels for cost reduction, uptime improvement and customer retention.
- Input-cost and formulation pressure: Upstream feedstock volatility (notably ethylene glycol) and specialty chemical costs (including phosphoric acid) continue to shape margin dynamics and incentivize formulation innovation and supplier hedging.
- Regulatory and infrastructure shifts: New or strengthened regulation—ranging from U.S. federal refrigerant management rules now in force to building code updates that change EV-charging and ventilation dynamics—has indirect but material effects on service patterns, component lifecycles and parts-replacement cadences.
For executives, that combination means radiator-flush manufacturers, distributors and end-user fleets must translate market growth into concrete choices: where to invest in R&D, how to structure procurement, how to price value-added services, and whether to pursue consolidation or partnerships to protect margin and market access.
Worldwide Radiator Flushing Chemicals Market
Market structure and competitive implications
Our concentration analysis shows a market that is neither atomized nor locked: leading players capture a meaningful share, but sufficient space exists for regional specialists, private-label programs and technical innovators. The top three players account for a material, but not overwhelming, portion of sales, and the top five increase that concentration further—conditions that favor both targeted M&A and aggressive channel strategies.
Key competitive archetypes we profile in the full study:
- Large brand incumbents with broad aftermarket distribution and integrated service offerings. These firms leverage retail shelf presence, service-bay relationships and brand trust to maintain volume and premium pricing.
- Technical formulators and specialist suppliers focused on performance chemistry and OEM/industrial approvals—positioned to win fleet and OEM-specified programs where performance and compatibility are paramount.
- Regional formulators and private-label manufacturers with deep local procurement advantages and cost structures tailored to price-sensitive buyers.
Representative company profiles in the report span these archetypes and include legacy household names and technical specialists. Our competitive chapter examines their product positioning, go-to-market motions, channel economics and recent strategic moves—arming buyers and sellers with the context needed to evaluate partnership or M&A prospects in 2026.
Input-cost dynamics: what the numbers mean for margins and pricing
Raw-material trajectories are central to near-term margin risk. Ethylene glycol—an upstream feedstock influential for coolant-related formulations—experienced a period of elevated prices early in 2025 followed by a decline and a year-end rebound; our market-source consensus for 2026 anticipates initial weakness and then range-bound stability with typical levels around 4,000–4,400 RMB/ton amid ample supply. Separately, phosphoric acid pricing in early 2026 shows geographic variation (with prices reported at different levels across North America, Europe, Northeast Asia and Africa), underscoring regional input-cost differentials for manufacturers with geographically dispersed sourcing.
Operational takeaway for procurement and pricing teams: establish dual-track hedging and flexibility in supplier contracts now. Manufacturers with rigid single-source exposure risk margin erosion; distributors and private-label partners should prioritize formulations that tolerate modest raw-material price swings or allow rapid reformulation to protect gross margin.
Regulatory and infrastructure catalysts
Two regulatory developments merit explicit attention for 2026 planning. First, tighter federal handling rules for reclaimed refrigerants have implications across aftermarket service workflows and technician training budgets; compliance-driven service-protocol changes can alter the economics and cadence of maintenance visits. Second, building-code updates in leading jurisdictions (including expanded EV charging and ventilation rules) are shifting vehicle use patterns and service-site infrastructure—indirectly changing where and how thermal-management maintenance is performed. Our report translates these legal changes into practical checklists and scenario adjustments for product liability, service SOPs and technician certification investments.
Actionable plays for 2026 — prioritized
From our strategy work with manufacturers, distributors and fleets, PW Consulting recommends five prioritized plays to convert market growth into commercial advantage in 2026:
- Procurement resilience: renegotiate supply agreements with flexible volume bands, secure alternate feedstock sources, and institute a lightweight price-pass mechanism to protect margins during short-term feedstock volatility.
- Formulation stratification: maintain a core brand line for retail customers while accelerating development of higher-value, OEM-compliant formulations and service-bay concentrates that command premium margins and deeper customer lock-in.
- Service integration: build bundled maintenance offers (coolant chemistry + diagnostic + scheduling) for fleets and dealer networks to capture adjacent service revenue and improve retention.
- Selective M&A and partnerships: target bolt-on acquisitions in regional markets where distribution is fragmented or in technology pockets (bio-based chemistries, rapid-descaling) to accelerate capability without heavy greenfield investment.
- Regulatory-ready operations: implement compliance playbooks and training modules addressing recent refrigerant and building-code changes, minimizing service interruptions and liability exposure.
What PW Consulting’s full report delivers (practical components)
The published study is designed as a decision-making toolkit for 2026 and beyond. Highlights include:
- Quantified market model: annual historical and forecast revenue model with bottom-up and top-down reconciliations, scenario runs (base, upside, downside) and sensitivity levers for input-cost and fleet-utilization variables.
- Competitive intelligence packet: 10 in-depth company dossiers, product maps, channel economics, pricing matrices and capability heatmaps for rapid benchmarking.
- Regulatory impact assessment: jurisdiction-level implications, compliance cost estimates and a step-by-step operational compliance checklist.
- Procurement playbook: supplier scorecards, hedging templates, total-cost-of-ownership calculators and supplier-disruption contingency plans.
- M&A and partnership screening: quantitative target-scoring model, integration risk checklist and a shortlist of acquisition archetypes matched to strategic objectives.
- Commercial execution tools: go-to-market playbooks for retail, fleet and OEM channels, including bundling strategies, margin waterfall templates and KPIs for 90/180/360-day rollout plans.
Importantly, while this briefing highlights high-level market sizing and growth trajectory, the full report contains the granular segmentation, regional splits, product-chemistry breakdowns and absolute-dollar benchmarks that underpin the strategic tools above. That granular intelligence is intentionally gated to enable bespoke advisory engagements and to preserve the integrity of our benchmarking datasets.
Competitive highlights — what to watch in 2026
Our competitor analysis identifies three near-term behaviors likely to shape the competitive landscape in 2026:
- Brand incumbents doubling down on service integration: Expect established aftermarket names to increasingly bundle radiator flush products with service-bay programs and diagnostics to defend retail share and secure recurring revenue.
- Technical suppliers driving specification wins: Companies focused on performance chemistry (including rapid-flush and non-acidic formulations) will pursue fleet and OEM approvals, leveraging technical credentials to capture higher-margin contracts.
- Regional players exploiting localized cost advantages: In markets with distinct feedstock pricing or regulatory profiles, nimble local producers will push private-label and distributor partnerships to capture price-sensitive demand.
We analyze representative firms across these behaviors in the full report, mapping product innovations to customer segments and quantifying likely revenue upside for strategic moves such as expanding service partnerships, launching OEM-compatible formulations, or executing targeted tuck-in acquisitions.
Next steps for leaders
For C-suite and commercial leaders preparing 2026 plans, prioritize three immediate actions based on our findings: 1) run a rapid procurement stress-test against the report’s sensitivity scenarios to identify margin pressure points; 2) pilot a bundled maintenance offering with one fleet or dealer partner to validate pricing and operational workflows; and 3) initiate a focused due-diligence pipeline of regional acquisition targets or technical partners aligned with your desired route-to-market.
PW Consulting’s full Worldwide Radiator Flushing Chemicals Market report is structured to support those actions with executable tools, verified datasets and a shortlist of strategic options tailored to your corporate objectives. For organizations that need hands-on implementation support, our advisory teams are available to convert the report’s insights into a prioritized 90-day action plan.
To access granular segmentation, regional breakdowns, and the complete set of decision-support tools referenced here, visit our report page or contact PW Consulting’s industry desk to schedule a briefing and bespoke modeling session.
For detailed analysis of this topic, please visit the official page: Worldwide Radiator Flushing Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com