

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Anti‑Nestin Antibody Market Poised to Surge at 6.64% CAGR, Reaching USD 74.53 Million by 2032

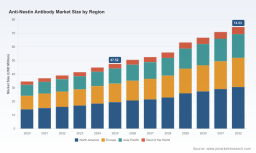
Worldwide Anti‑Nestin Antibody Market — Strategic Imperatives for 2026
PW Consulting today publishes a strategic briefing derived from our full market research report on the Worldwide Anti‑Nestin Antibody Market (base year: 2025; historical review: 2020–2025; forecast period: 2026–2032). The market has expanded steadily from the low‑30s (USD Million) in 2020 to just under USD 48 Million in 2025 and is forecast to reach the mid‑70s (USD Million) by 2032, reflecting a compound annual growth rate (CAGR) of 6.64% across the forecast period. This release is designed as an executive “trailer”: it synthesizes the research team’s most consequential insights and action points for 2026 decision‑makers while reserving granular regional, application and price tables for the full report.
Worldwide Anti-Nestin Antibody Market
Executive snapshot: what this means for 2026 strategy
- Growth momentum is durable but selective. Overall expansion is supported by sustained investment in basic and translational neuroscience, stem cell biology and oncology research; however, pockets of commercial intensity and competitive pressure vary by product format and validation claims.
- Market structure presents both concentration and opportunity. The market displays measurable concentration with the top three and top five suppliers commanding material portions of commercially available offerings—creating a commercial environment where scale and validation resources are differentiators.
- Regulatory and labeling realities shape near‑term addressable demand. Anti‑Nestin antibodies supplied by leading vendors remain Research Use Only (RUO), constraining direct diagnostic or therapeutic deployment and making rigorous, application‑specific validation a commercial differentiator rather than a compliance lever.
- Supply chain and manufacturing details matter. Production relies heavily on recombinant proteins and synthetic peptides as immunogens, with affinity purification and formulation choices (e.g., stabilizers such as BSA or sodium azide) materially affecting product stability, lot‑to‑lot consistency and buyer procurement preferences.
Why 2026 is a turning point
Two dynamics converge in 2026 to make strategic choices urgent. First, the research landscape is experiencing discrete increases in funding for neural stem cell and neuro‑oncology programs, driving demand for validated markers and conjugated formats that support flow cytometry, immunofluorescence and multiplex workflows. Second, suppliers face margin pressure as commoditization of basic antibody formats accelerates and customers increasingly demand validated, reproducible reagents with transparent manufacturing histories.
Worldwide Anti-Nestin Antibody Market
For suppliers, 2026 is a decision year: invest in depth (validation, conjugates, recombinant clones), protect margins through upstream control of immunogen and purification processes, or pursue scale via distribution agreements and portfolio breadth. For buyers and procurement leaders, 2026 is the inflection where certification of supply continuity and batch comparability becomes as important as unit price.
Worldwide Anti-Nestin Antibody Market
Competitive landscape — profiles and strategic positioning
- Thermo Fisher Scientific (Invitrogen) — Offers breadth: an extensive catalog of monoclonal, polyclonal and recombinant anti‑Nestin reagents validated across IHC, WB, ICC, FC and ELISA. Strategic advantage: scale and global validation data that appeal to academic and large‑scale industrial buyers.
- BD Biosciences — Focused presence in flow cytometry‑grade conjugated reagents and clone‑based solutions for intracellular staining. Strategic advantage: integration with established cytometry platforms and strong RUO positioning for developmental biology applications.
- Bio‑Rad Laboratories — Historically oriented toward research markets with polyclonal formulations targeted at neuroectodermal and tumor marker research. Strategic advantage: specialized formulations for histology and WB customer segments.
- STEMCELL Technologies — Differentiates via stem‑cell centric reagents and conjugate options, targeting embryonic neuroepithelial and glioblastoma research communities. Strategic advantage: deep domain alignment with stem‑cell researchers and associated protocols.
- R&D Systems (Bio‑Techne) — Emphasizes validated clones with publication citations; appeals to groups prioritizing reproducibility and citation lineage.
- Sino Biological — Competitive on recombinant and hybridoma‑derived formats with flexible formulations; strategic strength in cost‑competitive supply and upstream recombinant capability.
- Miltenyi Biotec — Positions reagents in the context of developmental neurobiology research and cell separation workflows.
- Abcam — Offers a diverse antibody catalog with options across host species and conjugations; strong digital searchability and technical resources.
- Sigma‑Aldrich (Merck KGaA) — Leverages legacy reagent brand recognition with multiple clone and polyclonal options suitable for basic research applications.
Collectively, the market’s concentration measures indicate a landscape in which leading suppliers maintain meaningful share advantages but do not fully preclude nimble challengers that combine targeted validation data, competitive pricing and close engagement with research communities.
What the full report delivers — operational intelligence for 2026
- Robust market sizing and forward forecasts (2026–2032) with scenario and sensitivity modeling tied to funding, regulatory, and adoption variables.
- Commercial diagnostic: pricing benchmarks, channel mixes, and distributor margins — actionable for commercial and procurement teams.
- Supplier scorecards and comparative technical matrices (clone provenance, host species, validated applications, conjugates, lot‑release testing protocols).
- Product development playbooks including recommended validation studies that shorten customer adoption cycles and improve SKU stickiness.
- Supply‑chain due diligence dossiers on key raw materials (recombinant immunogens, peptides, affinity resins, stabilizers) and identified single‑source risks.
- M&A and partnership screening: target lists and valuation yardsticks for buyers and PE investors seeking consolidation or strategic bolt‑ons.
- Regulatory & labeling FAQ tailored to RUO constraints and pathways for transitioning selected reagents toward clinical‑grade workflows.
- Regional and application demand heatmaps (note: detailed regional/application tables are available only in the licensed full report).
Actionable recommendations for decision‑makers in 2026
- Prioritize validation that maps to customer workflows. Invest in multi‑application validation packages (IHC, FC, ICC, WB) and publish reproducibility datasets; customers increasingly buy against demonstrated protocol fit rather than brand alone.
- Differentiate via conjugation and recombinant offerings. Conjugated clones and recombinant antibodies reduce variability and unlock premium pricing in flow and multiplex assays.
- Strengthen upstream control of immunogen and purification processes. Vertical integration or qualified long‑term supplier contracts for recombinant proteins/peptides can improve margin and reduce supply interruptions.
- Deploy tiered commercial models. Maintain a commodity tier for cost‑sensitive buyers while creating a premium validated tier with technical support, lot comparability documentation and co‑development options for translational projects.
- For biotechs pursuing translational/diagnostic paths: begin early engagement with regulatory counsel and design validation protocols that can be adapted from RUO to regulated contexts; the RUO status of current offerings is a constraint, not an immutable barrier.
- Consider targeted M&A or distribution partnerships to round out gaps in conjugate technologies, geographic coverage or publication‑grade validation data.
- Build transparent supply‑chain traceability. Provide end‑to‑end manufacturing information (immunogen sequence, purification methods, stabilizers) to reduce customer switching costs.
Scenario planning and financial contours
Our baseline forecast assumes the 6.64% CAGR across 2026–2032 and reflects current adoption trajectories in core research domains. The full report includes upside and downside scenarios that model: accelerated adoption driven by new multiplex assays and increased research funding; and downside outcomes from tighter RUO interpretations or significant supply chain disruptions. Each scenario is supplied with implied revenue curves, margin pressure analyses and recommended tactical responses so commercial teams can prioritize investments with a clear view of expected ROI horizons.
Regulation, manufacturing nuances and buyer FAQs
Key practical realities addressed in the report’s FAQ: major commercial anti‑Nestin reagents remain designated RUO and are not for diagnostic or therapeutic use; manufacturing typically employs recombinant proteins or synthetic peptides as immunogens with affinity purification workflows and stabilizers (e.g., bovine serum albumin or sodium azide) incorporated at formulation. These elements influence labeling, shipping, cold‑chain requirements and customer acceptance; the full FAQ includes recommended labeling language and suggested lot‑release test panels.
Next steps — how to use this intelligence
PW Consulting’s briefing is intended to catalyze decisive actions in 2026. Suppliers should use the competitive and supply‑chain analysis to define investment priorities in validation and upstream control. Buyers and procurement teams should incorporate the supplier scorecards and risk dashboards into contract renewal cycles. Investors should leverage the scenario models and supplier shortlists to evaluate consolidation targets and technology bets.
For access to the full dataset, detailed regional and application splits, supplier scorecards and the complete methodological appendix, please consult the licensed report on the PW Consulting website. The full report contains the granular tables and appendices referenced in this briefing that are essential for transaction‑level decisions and product development roadmaps.
PW Consulting — actionable market intelligence for leaders shaping the future of antibody reagents and research‑grade diagnostics.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Nestin Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com