

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Zero-point Clamping System Market Poised for 6.55% CAGR Through 2032

Worldwide Zero-point Clamping System Market — Strategic Briefing for 2026 Decision Makers
Executive summary
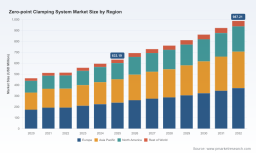
PW Consulting’s newest market research briefing on the Worldwide Zero-point Clamping System market synthesizes five years of historical observation (2020–2025) and a seven-year forecast window (2026–2032) into an actionable decision toolkit for manufacturing leaders, procurement officers, and corporate strategists. The market has expanded from roughly USD 462 million in 2020 to about USD 633 million in 2025, and our base-case forecast projects growth to nearly USD 1.0 billion by 2032 at a 6.55% compound annual growth rate (CAGR) for the forecast period. This trajectory reflects the combined impact of automation adoption, higher-mix/lower-volume production patterns, and ongoing performance improvements in workholding technology.
Worldwide Zero-point Clamping System Market
Why this report matters for 2026 strategy
-
Timing of capital allocation: With the market entering a sustained mid-single-digit CAGR phase, 2026 will be a pivotal year for committing CapEx to zero-point architectures as part of broader factory modernization and lights-out strategies.
Worldwide Zero-point Clamping System Market -
Supplier selection and risk mitigation: The market shows moderate concentration (CR3 ~42.8%, CR5 ~57.5%), indicating several influential incumbents alongside a diverse set of regional and niche players. This structure creates opportunity for leveraging competitive dynamics while requiring careful vendor qualification to avoid single-source exposure.
Worldwide Zero-point Clamping System Market -
Automation and integration: Zero-point systems are a pragmatic interface to Industry 4.0 goals — unlocking shorter setups, higher spindle utilization, and robotic handling compatibility. Decisions made in 2026 on standardizing interfaces and vendor platforms will materially shape throughput and flexibility for the next decade.
What PW Consulting’s report delivers — practical, transaction-ready content
-
Market-sizing and methodology: Transparent build-up from machine-level adoption assumptions to macro demand, reconciled to observed vendor footprints and trade-show intelligence. The report discloses base-year assumptions and sensitivity bounds to test investment theses.
-
Decision frameworks: Playbooks for procurement (TCO frameworks, warranty and service overlays, retrofit vs. greenfield cases), CapEx prioritization matrices, and ROI models calibrated for small-batch/high-mix operations as well as high-volume cellular environments.
-
Technical integration guidance: Interface checklists for mechanical, pneumatic, and hydraulic actuation types; automation-ready specifications; and thermal-management considerations for precision repeatability under production loads.
-
Vendor scorecards and RFP templates: Comparative assessment criteria covering precision, cycle-speed, sealing and cleaning readiness, integration with loading units, aftermarket support, and upgrade pathways — designed to accelerate vendor shortlists and procurement cycles.
-
M&A and partnership heatmaps: Strategic targets and capability clusters to consider for bolt-on acquisitions or distribution partnerships, including technology gaps and regional go-to-market considerations.
-
Scenario planning: Three demand scenarios (conservative, base, accelerated) with implications for inventory policies, supplier selection, and long-lead procurement decisions across a seven-year planning horizon.
Market dynamics shaping commercial choices in 2026
-
Operational economics: OEMs and job shops report setup-time reductions up to 90% with modern zero-point solutions; the knock-on effect is increased machine availability and reduced operator dependency. Our models quantify how incremental reductions in setup time translate into payback windows under different utilization profiles.
-
Materials and durability: System life depends on hardened alloy steel components treated for high surface hardness (approx. 57 HRC) to withstand cyclic loads and contamination — a non-negotiable design parameter for high-duty installations.
-
Precision and thermal behavior: Leading products deliver sub-3 μm repeatability and design for symmetrical thermal expansion to preserve datum integrity over temperature swings — criteria that should be explicit in technical procurement specs for precision-critical work.
-
Standards and automation: Vendors are converging on standardized, repeatable interfaces that facilitate integration into robotic loading, palletizers, and lights-out cells. Buyers should prioritize platforms that clearly map to their automation roadmap and allow future-proofing through modularity.
Competitive landscape — what the vendor field means for buyers and investors
The sector comprises established European innovators, global system integrators, and regional manufacturers offering differentiated approaches (mechanical, pneumatic, hydraulic, and integrated rotary-table solutions). Several vendors have shown active product development and trade-show presence in the past 18 months — activity that signals both continued incremental innovation and intensifying commercial outreach.
-
STARK Spannsysteme GmbH (ROEMHELD Group) — recognized for pioneering zero-point architectures and for emphasizing setup-time optimization across milling, turning, and automated lines. Their presence at major trade shows underlines a continued push into integrated factory solutions.
-
LANG Technik GmbH — known for modular grid systems and retrofitting capability, appealing to shops seeking to upgrade existing machines without large-stack modifications.
-
Zimmer Group — positions itself with application-specific modularity, supporting a range of processes from milling to EDM and grinding with focused error-reduction claims.
-
HAINBUCH GmbH — brings form-fit station systems that emphasize fast changeover for fixed-station, high-mix setups.
-
SMW-AUTOBLOK and EROWA AG — offer sealed, automation-optimized modules and palletized platforms respectively, targeting lights-out manufacturing and integration with automated loaders and EDM cells.
-
AMF Andreas Maier — demonstrates breadth across actuation types and has refreshed its catalog for 2025/2026 with modular offerings for cutting and non-cutting processes.
-
ZeroClamp, NIKKEN (Lyndex-Nikken), SCHUNK, Jergens, Gressel, and several Chinese manufacturers — represent either specialized high-precision options, integrated rotary-table strategies, or competitively priced alternatives for retrofit and domestic OEMs.
Recent product and trade-show activity (product module launches, EMO exhibitions, and catalog refreshes) confirms a market that is innovating incrementally and consolidating around automation-ready platforms. For organizations evaluating partners in 2026, due diligence should emphasize system compatibility with robotic handling, service networks, and the vendor’s roadmap for sealing, thermal management, and modular upgrades.
How to use this report to accelerate 2026 programs
-
Fast-track CapEx approvals: Use the report’s ROI matrices to build conservative and upside cases for immediate retrofit projects vs. phased greenfield investments; the workback from expected utilization gains will clarify acceptable payback thresholds.
-
Standardize interfaces now: Establish a plant-level mechanical and automation interface standard to reduce variation across installed systems and to enable multi-vendor sourcing without requalification costs.
-
Negotiate service-level agreements: With moderate market concentration, leverage competition to secure multi-year service contracts, spare-parts pooling, and rapid-response field service clauses that align with uptime targets.
-
Design supplier scorecards: Adopt the report’s vendor evaluation template to score vendors on repeatability, sealing, automation compatibility, retrofit complexity, and aftermarket support — then weight criteria to your production priorities.
-
Prepare integration pilots: Run two to three small-scale pilot integrations (different vendors or actuation types) in Q1–Q2 2026 to generate real-world data on cycle-time gains, fixturing flexibility and maintenance cadence before enterprise rollouts.
Risks, watchpoints, and red flags
-
Vendor lock-in and proprietary interfaces: Favor vendors that commit to open mechanical interfaces or provide adapter strategies to avoid future switching costs.
-
Underestimating thermal and contamination loads: Systems specified without adequate sealing or thermal-management provisions will degrade accuracy and life in heavy-duty environments.
-
Service-network gaps: Rapid adoption in new regions can outpace local service capabilities; ensure service and spare strategy is in place before scale-out.
-
Over-optimistic utilization assumptions: Payback models relying on unrealistic machine-utilization improvements can lead to stranded assets; stress-test assumptions across conservative scenarios.
Concluding recommendations
For 2026 decision cycles, zero-point clamping systems represent a high-leverage investment for companies pursuing increased machine capacity, faster changeovers, and deeper automation. Our market sizing and scenario work shows a market that has achieved meaningful scale and is forecast to expand steadily through 2032. Executives should treat zero-point selection as both a technical and strategic choice — one that will shape operational flexibility, supplier relationships, and automation outcomes for years to come.
PW Consulting’s full Worldwide Zero-point Clamping System Market report contains detailed vendor scorecards, the full segmentation model, RFP templates, and downloadable ROI tools designed to expedite procurement and integration. The report intentionally reserves certain granular segmentation and vendor-by-vendor numeric breakdowns to subscribers; this ensures the strategic exclusivity of commercially sensitive comparisons.
Next steps
-
Request a briefing with our industry team to align the report’s scenarios with your plant-level KPIs and CapEx calendar.
-
Commission a tailored procurement playbook using our RFP templates and vendor scorecards for immediate deployment in 2026 sourcing rounds.
-
Engage a pilot integration program to validate vendor claims on repeatability and cycle-time impact under your production conditions.
For access to the full dataset, downloadable tools, and the complete vendor assessments, please visit the PW Consulting report landing page or contact our lead analyst team to arrange a confidential walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Zero-point Clamping System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com