

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Paper Direct Dyes Market to Expand at 4.5% CAGR Through 2032 as Asia‑Pacific Leads Demand
By pmarketresearch, 2026-07-15
Worldwide Paper Direct Dyes Market — Strategic Briefing for 2026 Decision-Making
As global paper and board value chains recalibrate for sustainability, higher recycled content, and tighter chemical regulations, direct dyes for paper are emerging as a strategically significant input. PW Consulting’s new Worldwide Paper Direct Dyes Market study provides executive teams with the evidence base and decision tools required to convert macro trends into 2026 actions. The report shows the market expanding from about USD 442 million in 2020 to roughly USD 546 million in 2025, with a modeled progression into the forecast window (2026–2032) that reaches approximately USD 742 million by 2032, reflecting a 4.5% CAGR across the forecast period. These headline dynamics frame a market with predictable growth but shifting margin and regulatory risk profiles — context that should shape procurement, product, and M&A choices in 2026.
Worldwide Paper Direct Dyes Market
Why this matters to executives in 2026
- Timing: 2026 will be the first full year in which REACH 2025 revisions, strengthened PFAS controls, and expanded data requirements for endocrine disruptors materially alter supplier compliance costs and product acceptability in Europe. Buyers and suppliers who acted early on compliance will enjoy advantaged access to regulated end-markets.
- Cost pressure: Raw-materials and fiber-cost volatility continue to put pressure on paper producers’ margins; colorant suppliers are not immune. Cost passthrough strategies and localized sourcing will be critical in 2026 negotiations.
- Consolidation opportunity: Market concentration metrics indicate a moderately fragmented landscape (CR3 ~28.5%; CR5 ~41.1%), presenting scope for value-creative bolt-on deals for scale players and for specialist entrants to capture niche high-value applications.
Market dynamics and what the numbers conceal — interpreted
The overall market growth — underpinned by steady demand in packaging grades, tissue/towel consumption, and ongoing demand for print and specialty papers — masks divergent segment dynamics. Some end-use channels are tightening specifications (food-contact compliance, ecolabels), while others prioritize cost and throughput. Likewise, changes in pulp availability and price cycles have knock-on effects on dye uptake patterns and supplier pricing power: the industry’s exposure to raw-material swings (notably pulp and certain petrochemical intermediates) materially affects dye demand elasticity and supplier margin management.
Worldwide Paper Direct Dyes Market
Regulatory evolution is the single largest near-term structural force. The 2025 EU REACH revisions introduce essential-use criteria for higher-risk chemistries and greater data obligations. Concurrently, food-contact regulations (e.g., FDA guidance and BfR standards) and voluntary frameworks (ZDHC MRSL, bluesign, GOTS) are moving from marketing differentiators to commercial prerequisites in many geographies. For companies operating in or selling to regulated markets, 2026 will require documented compliance pathways rather than aspirational statements.
Worldwide Paper Direct Dyes Market
Competitive landscape — capabilities that matter in 2026
The supplier map blends global chemical champions, regional specialists, and local producers. Competitive advantage in 2026 will be determined by a mix of regulatory credentials, application know-how, and service-centered offerings (on-site dosing, shade-accurate colorants, wastewater-compatible chemistries). Key archetypes include:
- Integrated paper-chemicals platforms — Firms with broad paper-chemicals portfolios leverage cross-selling and operational integration to offer end-to-end optimization (e.g., water chemistry coupled with color solutions). These players are well-placed to offer compliance-backed formulations and operational support at scale.
- Color specialists with application focus — Vendors deeply embedded in pulp & paper applications (wet-end dosing, size-press, specialty boards) deliver shade precision and fiber-specific performance. Their value proposition centers on lower fixative needs and consistent runnability across furnish mixes.
- Regional producers — Local manufacturers can compete on price and local compliance speed; they are often first movers in fast-growing emerging markets but may lag on international regulatory certifications.
Illustrative supplier strengths observed in the market (non-exhaustive):
- Some suppliers emphasize high fiber affinity and reduced fixative requirements, lowering downstream chemical usage and improving runnability in mixed-fiber furnishes.
- Others have positioned portfolios toward food-contact and ecolabel compliance, offering formulations that simplify mills’ regulatory reporting.
- Several participants have increased public disclosure of sustainability metrics and adopted third-party standards to safeguard market access; this is now a procurement checkbox for many large converters and brand owners.
Recent corporate moves and implications
- Price adjustments and supply-side inflation have not been uniform. Public price moves in Asia and elsewhere in recent years underscore the need for buyers to design multi-year sourcing agreements and indexed pass-through mechanisms.
- Sustainability reporting from several suppliers reflects both genuine operational improvement and a strategic response to buyer demand for transparent supply chains. Buyers should triangulate reported KPIs with on-site audits and compliance documentation.
- Portfolio reshuffles and carve-outs (noted industry transactions since 2022) have reshaped competitive footprints; buyers and investors should reassess counterparty risk and continuity plans where ownership has changed.
What PW Consulting’s report delivers to support 2026 decisions
Our report is built as a decision support package, not a descriptive summary. It is designed to be used in procurement negotiations, R&D roadmaps, regulatory planning, and M&A diligence. Key actionable components include:
- Proprietary market model (2020–2032) with scenario-mode capability — run sensitivity tests on raw-material price shocks, regulatory adoption timelines, and substitution trends to quantify volume and revenue outcomes.
- Structured regulatory impact matrix — maps REACH 2025 changes, food-contact standards, and voluntary frameworks to product classes and supplier compliance risk levels.
- Supplier scorecards and risk profiles — assessment of technical capability, geographic coverage, regulatory credentials, and commercial flexibility to inform preferred-supplier lists and contingency sourcing.
- Procurement playbook — contracting templates, escalation clauses for raw-material inflation, and a six-step sourcing & qualification process tailored to paper direct dyes.
- Product-development and sustainability playbook — recommended formulations and testing pathways to accelerate time-to-market for compliant colorants, including wastewater compatibility checks and certification timelines.
- M&A and partnership screening framework — criteria to identify bolt-on candidates and JV partners that deliver immediate route-to-market advantages or required technical capabilities.
- Commercial impact calculators — ROI models for CAPEX (on-site dosing systems, automation) and OPEX (shade consistency, reduced rework) investments.
Strategic actions we recommend for 2026
- Embed regulatory-first product development: Prioritize reformulation workstreams to align with REACH and food-contact expectations; treat certification timelines as critical path items.
- Negotiate multi-year, indexed supply contracts: Use our scenario outputs to define trigger points for price reviews and to build in workload/volume flex that reflect pulp price volatility.
- Invest selectively in on-site service capabilities: Shade control, dosing automation, and wastewater-friendly chemistries reduce total cost of ownership and lock in customer relationships.
- Evaluate targeted M&A: Given the current fragmentation, strategic bolt-ons in specialized applications or in high-growth regions can accelerate access to technical talent and local approvals.
- Operationalize sustainability claims: Translate sustainability KPIs into product labelling and supplier scorecards to satisfy brand-owner procurement teams and regulators alike.
How to use the report in your 2026 planning cycle
Procurement teams can use the supplier scorecards and contracting playbook as the basis for a 12–24 month sourcing roadmap. R&D and product teams should adopt the regulatory matrix to prioritize reformulation projects and certification runs. Corporate development and strategy functions will find the scenario models and concentration metrics useful for sizing acquisition targets and anticipating competitor moves.
Next steps — where to get the full intelligence
This briefing highlights the macro trajectory and the high-level competitive dynamics you need to start planning for 2026. The full PW Consulting report contains the granular segmentation, regional and application-level demand curves, supplier share-by-subsegment tables, and downloadable model workbooks that underpin the recommendations above. For teams preparing procurement RFIs, R&D roadmaps, or M&A screens, those granular data and model permissions are mission-critical.
To access the complete dataset, templates, and the interactive forecast model, please follow the report access link on our website. PW Consulting stands ready to support tailored workshops, model-run sessions, and supplier diligence assignments to convert the report’s insights into executable 2026 plans.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Direct Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hardbanding Services Market to Expand at 5.1% CAGR (2026–2032), Peaking at USD 639.74 Million in 2031
By pmarketresearch, 2026-07-15
Worldwide Hardbanding Services Market — Strategic Intelligence to Guide 2026 Decisions
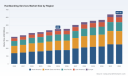
PW Consulting’s new market briefing on Worldwide Hardbanding Services synthesizes proprietary modelling, primary interviews, and on-the-ground service-provider intelligence to help C-suite leaders and investment teams make disciplined decisions in 2026. The hardbanding services market, having risen steadily through the early 2020s, stood at approximately USD 450 million in our 2025 base year and is modelled to grow at a steady compound annual growth rate (CAGR) of 5.1% across the 2026–2032 forecast window, reaching roughly USD 637 million by the end of the period. This release presents the strategic implications of that trajectory and highlights the operational levers executive teams should prioritize — without disclosing the granular segment tables contained in the full report.
Worldwide Hardbanding Services Market
Executive summary — why this matters in 2026
- Durability-driven demand: Increased upstream activity and an intensified focus on lowering cost-per-foot drilled mean operators will continue to prioritise tool-joint protection and service models that extend drill string life.
- Margin pressure from inputs: Volatility in wear-materials (notably tungsten carbide) and the evolving alloy mix will influence provider cost structures and pricing power.
- Certification and standards: Approval regimes are becoming decisive commercial differentiators — vendors with recognized approvals see easier operator uptake and premium positioning.
- Service model differentiation: Mobile applicator networks, certified shop capabilities, and value-added inspection & reporting are the primary levers to capture share.
Market trajectory and key macro drivers
The hardbanding market has demonstrated resilient growth since 2020, reflecting a combination of recovering drilling activity and a structural push toward lifecycle-cost reduction for drill strings. Our historical series (2020–2025) shows a steady increase in overall market spend as operators re-prioritise asset longevity and maintenance optimisation. Looking forward, the 5.1% CAGR we model for 2026–2032 is a function of modest E&P expansion in targeted basins, incremental adoption of higher-performance alloys, and a maturing replacement cycle for legacy service models.
Worldwide Hardbanding Services Market
Two macro considerations will shape near-term strategy:
Worldwide Hardbanding Services Market
- Input-cost dynamics: Tungsten carbide remains a critical raw material for many wear-resistant alloys. By Q4 2025 tungsten carbide prices reached approximately USD 57/kg, and the broader tungsten carbide market exceeded the multi-billion-dollar mark in 2025 — trends that speak to both supply tightness and the strategic importance of procurement and material substitution strategies for service providers.
- Standards & approvals: Industry-standard approvals (for example, recent Fearnley Group NS-1 approvals) are not only technical badges; they materially affect re-application permissions, operator acceptance, and contract awarding. Firms that secure widely recognised certifications shorten commercial lead times and command premium positioning.
Competitive landscape — positioning the leading players
The market remains moderately concentrated, with several technology and service specialists commanding meaningful share through differentiated alloys, applicator networks, and integrated service offerings. The competitive set spans global alloy innovators and regional mobile-service specialists. Key strategic characteristics of leading participants include:
- Postle Industries / Hardbanding Solutions (Cleveland, OH): A global leader in casing-friendly, crack-free alloys (e.g., proprietary Duraband variants) and end-to-end application solutions. Their focus on product performance and recent certifications has reinforced operator trust — a model that incumbents and challengers should seek to emulate through validated field performance and re-application pathways.
- Arnco Technology (Houston, TX): Specialist alloy development, including heatless tungsten-carbide options and robust applicator networks. Arnco’s technical depth around heatless and premium alloy formulations positions it well for high-spec applications and partnerships with field service providers.
- National Oilwell Varco (NOV) / Tuboscope (Houston, TX): Integration of hardbanding consumables with inspection, pipe services, and aftermarket offerings creates a bundled value proposition. NOV’s strength is in providing a one-stop solution linking application, inspection, and data — an attractive playbook for operators seeking simplified vendor management.
- Castolin Eutectic (Lausanne, Switzerland, global ops): Offers a broad wire portfolio and demonstrated capability in testing for abrasion, erosion, and sour-service conditions. Their laboratory-backed casing wear simulations underpin credibility for high-risk use cases.
- Regional/mobile specialists (e.g., Hard Band Industries, Pro‑Tech, Thompson & Thompson, Bandit Tech, Tech Energy): These providers combine shop and portable on-site capabilities, focused regional coverage, and rapid deployment models. Their competitive advantage is logistical agility and local relationships — valuable where time-to-service is a key operator constraint.
Strategic implication: partnerships between global alloy innovators and regional service operators are the most likely route to rapid commercial scale. Investors should prioritise platforms that blend proprietary consumables with scalable applicator networks and digital reporting.
Service models, technology trends and regulatory impacts
Two technical pathways dominate the innovation narrative: alloy evolution (including chromium- and titanium-enabled metals) and application technique (cored-wire vs. manual welding vs. heatless carbide deposition). The market is seeing incremental but material migration toward casing-friendly alloys that reduce secondary casing damage while delivering wear resistance. Simultaneously, demand for non-magnetic and low-distortion processes is rising in response to directional and complex-well programmes.
Regulatory and standards developments have also shifted the competitive landscape. Approvals such as Fearnley Group NS-1 play a deterministic role in enabling re-application over previous hardbanding layers and in operator supplier-selection processes. Our field interviews underscore that certification timelines are now a gating factor for commercialisation; securing approvals can materially accelerate uptake in operator fleets.
Supply chain and margin considerations
Input prices and raw-material availability are primary drivers of provider margin volatility. With tungsten carbide dynamics evident in late‑2025, service providers should consider three concrete mitigations:
- Hedging or contractual procurement strategies with primary carbide suppliers to stabilise cost of goods sold;
- R&D investment into alloy formulations that optimise tungsten-carbide loading without sacrificing life-cycle performance;
- Operational efficiency programmes — from improved application yield to reduced rework — that insulate gross margins from raw-material swings.
Actionable playbook for 2026
The market intelligence contained in PW Consulting’s briefing translates into immediate, actionable priorities for operators, service providers, and investors preparing for 2026.
- For operators (E&P companies and drill contractors): Consolidate supplier panels around vendors with both validated performance data and recognised approvals; pilot alloys in lower-risk wells before fleet-scale rollouts; demand transparent life-cycle cost modelling (not just price-per-application).
- For service providers: Invest in certification pathways and applicator training to convert product R&D into commercial adoption; deploy modular mobile units in high-opportunity basins; bundle inspection and digital reporting to create stickier service contracts.
- For OEMs and consumable manufacturers: Prioritise alloy formulations that reduce dependence on high-cost inputs, and pursue strategic alliances with regional applicators to accelerate field penetration.
- For financial sponsors and M&A teams: Target platform investments that combine proprietary consumables with scalable applicator footprints; value accrual will primarily come from consolidation of mobile service fleets, cross-selling of inspection services, and vertical integration into consumables supply.
About the report — practical content that supports decision execution
PW Consulting’s full Worldwide Hardbanding Services Market report (2026–2032 forecast) is structured to be directly actionable for deal teams and operating executives. Key deliverables include:
- Executive dashboards and scenario models calibrated to macro and basin-level drilling outlooks;
- Proprietary cost-to-serve and price-benchmark frameworks that convert product specifications into margin implications;
- Vendor scorecards and capability matrices including applicator networks, certification status, and service-level benchmarks;
- Operational playbooks for deploying mobile units, setting up shop capabilities, and field-testing new alloys;
- M&A diligence templates and valuation sensitisation tied to raw-material exposure and service mix;
- Implementation roadmaps for certification sequences and operator acceptance trials.
In keeping with our “trailer” approach, this communication intentionally showcases the report’s analytical depth while omitting the granular segment tables and region-application splits that form the core of the dataset. Those tables, and the underlying primary-data matrices, are contained in the full report and in the interactive models we deliver to clients.
Closing — how PW Consulting can support your 2026 agenda
For executive teams making capex, procurement, or M&A decisions in 2026, the right intelligence is both top-line directional and operationally prescriptive. PW Consulting’s briefing bridges that gap: it combines market sizing and growth trajectories with vendor-level insight, certification risk analysis, and executable playbooks to reduce time-to-value. If your team is prioritising hardbanding strategy in 2026 — whether to optimise fleet economics, scale a service platform, or identify buy-side targets — PW Consulting can provide a focused briefing and interactive workshop to translate the market picture into a one- to three-year plan.
Contact our industry team for an executive briefing and to obtain the full report and models. The full dataset contains the granular segment and regional detail required to complete transactional diligence and operational planning.
For detailed analysis of this topic, please visit the official page: Worldwide Hardbanding Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Air Quality Sensor ICs Market to Reach USD 1,569.03 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Air Quality Sensor ICs Market — Strategic Implications for 2026
Executive Snapshot
PW Consulting’s new market research briefing on the Worldwide Air Quality Sensor ICs market synthesizes five years of historical performance (2020–2025) with a rigorous 2026–2032 forecast. The market has moved from early-stage adoption to a strategic technology layer for multiple ecosystems — consumer devices, buildings, transportation, industrial automation and healthcare. At the macro level, the market reached approximately USD 780 million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of roughly 10.5%, reaching an expected market value north of USD 1.5 billion by 2032. Market concentration metrics indicate a moderate level of consolidation: the top three vendors account for a meaningful share of revenue while the top five firms control close to 60% of the market, underlining both incumbent strength and continued room for challengers.
Worldwide Air Quality Sensor ICs Market
Why this report matters for 2026 decision-making
For corporate strategists, product leaders, supply chain executives, and investors, 2026 is a strategic inflection point. The combination of accelerating demand for indoor and transported-air quality monitoring, rapid miniaturization and performance gains in sensor ICs, and shifting geopolitical and regulatory pressures requires concrete, scenario-based planning. This briefing is intentionally tactical: it blends forecast-driven market sizing and a scenario matrix with executable go-to-market playbooks, supplier maps, technical readiness assessments, and M&A/partnership opportunity screens.
Worldwide Air Quality Sensor ICs Market
- Investment timing and allocation: Understand where to prioritize R&D and capex across sensing technologies (gas, particulate, integrated multi-parameter), packaging, and signal conditioning to meet 2026 performance, power and cost targets.
- Supply-chain resilience: Map exposure to tariff and raw-material scenarios and identify hedging and nearshoring tactics to preserve margins under trade or material constraints.
- Commercial strategy: Prioritize sales motions and channel strategies for automotive OEMs, HVAC and building automation vendors, consumer OEMs, and smart-city integrators.
Key market dynamics shaping 2026
Three dynamics should dominate executive agendas this year:
Worldwide Air Quality Sensor ICs Market
- Technology convergence and product differentiation: Vendors are rapidly integrating multi-parameter sensing (gas + PM + environmental parameters), embedding on-chip signal processing and AI models, and refining ultra-low-power and fanless architectures for compact IoT devices. These innovations compress BOM and enable new endpoint designs.
- Geopolitical and regulatory pressure: Recent trade measures (notably tariff actions announced in early 2026) and export restrictions on critical minerals have already influenced supplier sourcing strategies and will continue to affect pricing and lead times. Simultaneously, more stringent indoor air quality standards and building codes in multiple jurisdictions are creating near-term commercial demand windows for compliant systems.
- Upstream environmental and compliance costs: Semiconductor and sensor manufacture itself is facing heightened scrutiny for emissions (VOCs, NOx, SOx, PM), increasing operational and compliance costs for manufacturers and subcontractors and pressuring suppliers to demonstrate sustainable processes.
Competitive landscape — what to watch
The report’s competitive analysis profiles incumbents and fast followers across technology stacks, product roadmaps, and go-to-market alignment. Below is a concise synthesis of strategic positions and implications for partners or bidders:
- Sensirion AG (Stäfa, Switzerland): Strengths include CMOSens®-based platforms and an expanding SEN6x/SEN6x successor family that combine VOC, NOx, PM and CO2-derived metrics. Sensirion’s focus on platform-level solutions paired with strong module supply capability makes it a favorite for indoor-air quality OEMs seeking fast time-to-market.
- ScioSense B.V. (Eindhoven, Netherlands): MOX-centered expertise, including automotive-grade lines, positions ScioSense well for vehicle and demanding consumer applications. Their differentiated processing and integrated compensation support automotive qualification roadmaps.
- Bosch Sensortec GmbH (Reutlingen, Germany): Bosch’s MEMS-based multi-sensing devices and recent ultra-compact, fanless PM offerings illustrate a strategy focused on component-level competitiveness for ultra-small IoT endpoints and mobile devices.
- Renesas Electronics Corporation (Tokyo, Japan): Renesas’ firmware-configurable ZMOD series delivers architectural flexibility, attractive to platform vendors and integrators who require field-updatable sensing stacks and signal conditioning.
- Infineon Technologies AG (Neubiberg, Germany): The XENSIV™ PAS CO2 family leverages photoacoustic spectroscopy to pursue high-accuracy CO2 monitoring in compact form factors — attractive for smart building and ventilation control systems seeking standards compliance.
- Amphenol Advanced Sensors / Amphenol SGX (US/UK): These businesses deliver a broad portfolio across NDIR, MOX and PM technologies and maintain strong ties into HVAC/building automation supply chains.
- Cubic Sensor and Instrument Co., Ltd. (Wuhan, China): Focused on integrated modules that combine laser, NDIR and multi-parameter sensing, Cubic serves a range of domestic and export-focused OEMs with vertically integrated manufacturing capabilities.
Recent product launches (Sensirion’s SEN65/SEN63C platforms, Bosch’s BMV080 and BME690 series, Infineon’s XENSIV PAS releases) confirm that incumbents are racing on three vectors: size/power, integration, and automotive/industrial qualification. For 2026, buyers and partners should evaluate vendor roadmaps against explicit product life-cycle windows and qualification timelines.
Strategic recommendations for 2026
Based on our scenario analysis and vendor mapping, PW Consulting recommends the following actions for corporates and investors entering or scaling in this market:
- Dual-source critical components: Implement a dual-sourcing policy for any component tied to constrained supply of critical minerals or advanced packaging steps. Prioritize suppliers with demonstrated capacity to shift wafer or package production regionally.
- Invest in systems-level differentiation: Sensor ICs are increasingly commoditized; winning solutions will combine hardware, embedded signal processing, and cloud analytics. Invest in firmware/ML stacks that compensate for drift, environmental variance and cross-sensitivity.
- Qualify early for automotive and healthcare segments: These segments have high unit value and are governed by long qualification cycles. Begin qualification and co-development in 2026 to capture production windows aligned with 2027–2029 ramps.
- Mitigate regulatory and environmental risk: Build regulatory scenario playbooks and cost models that incorporate tariff impacts and emissions compliance costs; include these in procurement negotiations and supplier scorecards.
- Pursue bolt-on M&A selectively: Look for acquisitions that add software/analytics capability, module assembly, or regional packaging capacity rather than only one-off sensor IP plays. The CR3/CR5 concentration suggests attractive consolidation opportunities at the mid-tier.
What PW Consulting’s report delivers (practical takeaways)
This briefing is structured for immediate operational use. Key deliverables include:
- Proprietary market model (2020–2032) with base-year 2025 calibration and sensitivity testing against tariff and material-shortage scenarios.
- Technology readiness assessments for gas, particulate and integrated multi-parameter ICs, including performance vs. power, size and cost trade-off matrices.
- 50+ supplier profiles and a supplier capability map highlighting regional manufacturing footprints and strategic dependencies.
- Commercial playbooks segmented by buyer persona (consumer OEM, automotive Tier-1, HVAC integrator, smart-city aggregator, and medical device OEM), with channel and pricing recommendations.
- M&A and partnership screening templates, including synergies, integration risk scoring and near-term valuation ranges under different market-growth scenarios.
- Regulatory impact matrix and compliance roadmaps aligned to likely IAQ standards and building-code timelines in target markets.
- Go/no-go decision frameworks for in-house development versus strategic sourcing or licensing.
To respect the “trailer” principle of this release, core segmented numbers for region, application and device-type splits are purposefully omitted here — they are presented in full detail within the report and the online data workbook to enable transactional and procurement-level planning.
How to use this briefing in board-level planning
Boards and executive teams should treat the 2026 planning cycle as an opportunity to convert product and supplier roadmaps into executable programs:
- Update strategic risk registers to reflect tariff and critical-material scenarios and assign mitigation owners.
- Set a cross-functional sensor program office to align R&D, procurement and commercial teams around integrated sensing platforms and qualification milestones.
- Define clear KPIs for supplier diversification, time-to-market for integrated products, and revenue mix by qualified application segments.
Next steps and access
PW Consulting’s full Worldwide Air Quality Sensor ICs Market report includes the complete data workbook, vendor scorecards, and an interactive scenario model that executives can use to quantify the financial impact of sourcing and product decisions. For teams preparing 2026 budgets and strategic plans, this briefing should be used as the foundation for a rapid capability audit and a six- to twelve-month action plan.
Contact PW Consulting to request the full report and the companion data pack to convert these insights into executable projects and procurement decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Air Quality Sensor ICs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Miniature Refrigeration Compressor Market to Expand at 8.52% CAGR — From USD 581.15 Million in 2025 to USD 1,030.04 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Miniature Refrigeration Compressor Market: Strategic Preview for 2026 Decision-Making
PW Consulting presents an executive preview of our new market research report on the Worldwide Miniature Refrigeration Compressor Market. This briefing explains why 2026 is a pivotal year for product, supply-chain and investment strategies in this space, synthesizes the macro growth narrative, and outlines the strategic questions the full report answers. The intent is to demonstrate the analytical rigor underpinning our conclusions while reserving detailed segment-level data for the full report and dataset.
Worldwide Miniature Refrigeration Compressor Market
Market at a Glance — Macro Trajectory
Miniature refrigeration compressors are in an established growth phase. Using 2025 as the report's base year, PW Consulting estimates the global market at approximately USD 581.2 Million (revenue unit: Million), with a multi-year compound annual growth rate (CAGR) of about 8.52% over the 2026–2032 forecast horizon. Our forecast shows continued expansion through 2032, underscoring durable demand drivers across portable cooling, medical cold chain, vehicle refrigeration and electronics thermal management.
Worldwide Miniature Refrigeration Compressor Market
- Base year and scope: 2025 base year; historical window 2020–2025; forecast period 2026–2032.
- Currency and units: USD, revenue reported in Million USD.
- Market concentration: The market exhibits moderate-to-high consolidation at the top, with the three largest firms controlling a meaningful share and the top five accounting for a dominant portion of industry revenue—indicators that scale and IP matter.
Why 2026 Is a Strategic Inflection Point
Several converging forces make 2026 a high-leverage year for executives in compressors, OEMs and systems integrators:
Worldwide Miniature Refrigeration Compressor Market
- Regulatory tightening on refrigerants: Recent mandates accelerating transition to low-GWP refrigerants and A2L classifications for many self-contained systems create immediate technical and certification imperatives for product lines.
- Efficiency and performance standards: Upward pressure from energy-efficiency regulations and buyer expectations is accelerating adoption of variable-speed drives and advanced control algorithms.
- Supply-chain and input-cost volatility: Periodic spikes in copper and other commodities are re-shaping sourcing strategies and should prompt near-term hedging and supplier diversification decisions.
- Commercialization windows: Innovations in ultra-compact, DC and BLDC mini compressors are intersecting with mass-market applications (portable cold-chain, e-mobility accessories, medical devices), making timing critical for first-mover advantage.
Drivers Changing Competitive Advantage
Our scenario analysis identifies three primary capability domains that will determine winners and losers through 2026 and beyond:
- Refrigerant compatibility and safety engineering — compliance with low-GWP mandates and safe handling of mildly flammable A2L agents.
- Power-density and controls — high COP across duty cycles, quiet operation, and seamless integration with variable-voltage vehicle and portable power systems.
- Manufacturing scale and supply resilience — ability to absorb commodity swings and meet OEM qualification timetables without compromising margins.
Companies that can combine these domains with clear go-to-market partnerships in medical, logistics and e-mobility segments will capture outsized value as the market expands.
Competitive Landscape — Who Matters and Why
The miniature compressor arena blends niche specialists and larger hermetic suppliers. Our qualitative benchmarking covers technology platform, application focus, certification status, and route-to-market. Highlights include:
- Aspen Compressor, LLC (Somerset, KY, USA) — Known for ultra-compact rotary compressors and US-made quality, Aspen’s portfolio emphasizes variable-speed DC designs and approvals for low-GWP refrigerants. Their presence at AHR Expo 2026 reaffirmed a premium, safety- and certification-led positioning for mobile and weight-constrained applications.
- RIGID Technology (China) — A leader in high power-density BLDC rotary DC compressors with a broad voltage and capacity range. RIGID plays strongly to OEM-customized micro-cooling modules and direct-expansion systems for portable and medical systems.
- MOIR Cooling Co., Ltd. (Shenzhen, China) — Focuses on minimal footprint, high-COP DC rotary compressors tolerant to elevated ambient temperatures — attractive to industrial, medical and e-mobility customers operating in challenging environments.
- Glen Refrigeration; Lando Chillers; Miracle Refrigeration — Regional innovators focusing on ultra-compact variable-speed modules and micro-system integration, often supporting ODM/OEM partnerships.
- Huayi Compressor — A large-scale hermetic compressor manufacturer extending into mini and DC models; represents a bridge between traditional mass-market compressor production and emerging portable/mobility niches.
- Secop (Germany) — Focused on high-efficiency, sustainable solutions for mobile and light-commercial refrigeration; strong in regulated markets and compliance-heavy segments like medical cold-chain.
- Air Squared (USA) — Notable for scroll-based micro-compressors, representing a technology outlier with implications for noise, vibration and longevity in select compact vapor-compression systems.
These profiles are analyzed in the report against product roadmaps, IP positions, manufacturing footprints, and channel strategies. While top-tier players command a significant share of revenue, the market still leaves room for targeted specialists that combine technical differentiation with regulatory compliance.
Key Risks and Near-Term Shocks to Monitor
- Raw material volatility — Recent copper price swings highlight how commodity cycles can compress margins and force repricing; procurement strategies must now incorporate active hedging and alternative-sourcing playbooks.
- Regulatory acceleration — The combined effect of appliance and refrigerant regulations is compressing product development timelines; non-compliance risks market exclusion in key jurisdictions.
- Technology obsolescence — Rapid advances in motor control, power electronics and materials can make product lifecycles shorter than expected, requiring modular architectures and upgradeable control software.
Actionable Strategic Implications for 2026
PW Consulting recommends that companies take three coordinated moves in 2026 to protect and grow market position:
- Prioritize refrigerant-aligned product upgrades. Fast-track A2L-compatible designs and certification programs for low-GWP refrigerants. For OEMs, specify compressors with verified safety protocols and supplier commitments to certification timelines.
- Invest in power-dense, variable-speed platforms. Variable-speed BLDC architectures deliver energy savings and broader application fit; invest in control software and firmware ecosystems that allow seamless integration with battery systems and vehicle power rails.
- De-risk supply chains. Adopt a dual-sourcing strategy for critical components (motors, copper windings, bespoke housings), paired with inventory hedges or supplier-financing structures to stabilize input-cost exposure during commodity spikes.
What the Full PW Consulting Report Contains (Practical, Actionable)
The full report is structured to be directly usable by product, sourcing, and M&A teams. Core deliverables include:
- Market sizing and outlook with scenario modeling through 2032 (base year 2025), including sensitivity to commodity costs and regulatory adoption curves.
- Competitive intelligence dossiers covering product roadmaps, certifications, channel strategies and estimated market concentration dynamics.
- Practical playbooks: supplier heatmaps, product development checklists for A2L and low-GWP compliance, TCO and payback tools for OEMs evaluating compressor choices.
- Investment frameworks for private-equity and corporate development teams: valuation comparables, M&A integration risks, and three acquisition archetypes tied to scale, technology or channel access.
- Customized scenario templates and dashboards that allow decision-makers to stress-test revenue and margin outcomes under alternate copper-price and regulatory timetables.
Note: To preserve the strategic integrity of our analysis while offering a clear advisory pathway, detailed segment-by-segment revenue tables and granular regional/application splits are included only in the licensed report and dataset.
How to Use This Report in 2026 Planning Cycles
Executives should integrate the insights into three planning processes immediately:
- Product roadmap reviews — Prioritize features and certification assets that impact market access in regulated geographies and high-value use cases (medical, military, portable cold-chain).
- Procurement and sourcing strategy — Use our supplier heatmaps and cost-sensitivity models to set procurement KPIs and contingency plans for commodity shocks.
- Business development and channel strategy — Align sales incentives and partnership models with the fastest-growing end-markets identified in the report, and use our risk-adjusted forecasts to set realistic revenue targets.
Closing Perspective — Where the Value Lies
The miniature refrigeration compressor market is maturing into a strategic domain where technical differentiation, regulatory alignment and supply-chain robustness determine value capture. PW Consulting’s analysis shows a clear growth runway from the 2025 base, with accelerating opportunities for firms that can bring certified, power-dense, quiet and efficient compressors to market at scale. For 2026 decision-making, the actionable edge comes from combining product engineering priorities with pragmatic supplier and certification roadmaps—precisely the integrated guidance our full report provides.
Next Steps
For executives evaluating product investments, supplier strategies, or potential transactions in this market, the full PW Consulting report provides the detailed forecasts, segment analytics and decision tools required to act with confidence in 2026. Contact PW Consulting to license the full dataset, access scenario models, or commission a tailored strategic brief aligned to your organization’s portfolio.
For detailed analysis of this topic, please visit the official page: Worldwide Miniature Refrigeration Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Accountable Care Solutions Market to Reach USD 76,887.31 Million by 2032, Growing at a 14.5% CAGR
By pmarketresearch, 2026-07-15
PW Consulting Releases Strategic Brief: Worldwide Accountable Care Solutions Market — A 2026 Decision Playbook
As health systems, payers, and technology vendors prepare for a decisive year of implementation and consolidation in accountable care, PW Consulting publishes a focused industry briefing derived from our full Worldwide Accountable Care Solutions Market report (base year 2025). The briefing synthesizes macro trajectory, regulatory inflection points, vendor positioning, and pragmatic decision tools that senior executives must use to shape product, commercial, and regulatory strategy in 2026. We deliberately offer deep, actionable perspective here while reserving the granular segmentation and financial line items for the full report to encourage direct engagement and due diligence.
Worldwide Accountable Care Solutions Market
Market trajectory: a rapid, reproducible expansion
Accountable care solutions are moving beyond pilot phases into scaled deployment. Our analysis shows the global market expanding at a compound annual growth rate (CAGR) of approximately 14.5% from 2026 through 2032. After a base-year market estimated at roughly USD 29.8 billion in 2025, the market is expected to accelerate into the mid-2030s, crossing the USD 76.8 billion threshold by 2032 under our central scenario. This pace of expansion reflects a convergence of regulatory momentum, proven shared-savings economics, and rapid adoption of cloud-native, analytics-driven delivery models.
Worldwide Accountable Care Solutions Market
Why 2026 is a strategic inflection point
- Regulatory and reimbursement tailwinds: CMS’ recent program updates and model launches are reshaping the operating environment for ACOs. For Performance Year 2026, CMS reports a meaningful increase in participation and scale, and policy adjustments — such as an uplift to the Continuous Improvement Factor for targeted ACO cohorts — have sharpened incentives for technology-enabled care coordination.
- Proven financial outcomes: Accountable care models have demonstrated material impact on Medicare spending. In reconciled results, MSSP participants recently recorded billions in shared savings and net savings to Medicare, reinforcing payer and provider appetite for platform investments that materially lower total cost of care.
- Strategic program design on the roadmap: With application cycles and preparatory work already underway for next-generation models (including the LEAD design scheduled to launch after ACO REACH), vendors and provider organizations have a finite window in 2026 to align product roadmaps and capital plans to the new performance constructs.
Dynamics shaping vendor and buyer decisions
- From episodic analytics to real-time risk-bearing platforms: Industry reports and buyer feedback indicate a rapid transition toward platforms that support continuous risk stratification, live payer integration, and automated care orchestration. This is not an incremental shift; buyers now expect near-real-time data flows between payers, care managers, and analytics engines.
- API-first payer integration: Payer API initiatives and the integration of claims and clinical data are moving from experimental to operational, demanding that vendors deliver robust, standards-based interfaces and governance models.
- Vendor accountability and accreditation: Accreditation programs targeted at both ACOs and their technology providers have become focal points for procurement teams; buyers are prioritizing vendors that can demonstrate compliance with ACO-specific data exchange, governance, and security requirements.
- Delivery model evolution: Cloud and web-based delivery dominates new procurement decisions due to scalability and faster time-to-value, while on-premise offerings are being assessed for niche use cases tied to legacy integrations and data residency concerns.
Competitive landscape: concentration, capability, and emergent challengers
The market displays moderate concentration: the top three vendors command a meaningful share of commercial and institutional contracts, with the top five representing nearly half of observed revenue in our cross-market review. This structure creates distinct opportunities for mid-market specialists and nimble cloud-native entrants to differentiate on execution, integration speed, and payer relationships.
Worldwide Accountable Care Solutions Market
- Established incumbents — Providers of broad EHR and analytics platforms continue to anchor enterprise deals, leveraging installed bases, deep interoperability stacks, and integrated population health modules. These firms maintain advantages in scale, enterprise-grade security, and longitudinal clinical records.
- Payer-integrated players — Organizations that combine payer operations with clinical tools (including care management and contracting support) are positioned to win bundled value-based care programs. Their strength is in underwriting risk, designing contracts, and operationalizing clinical pathways at scale.
- Point-solution specialists — Care orchestration platforms, risk stratification vendors, and care management specialists are increasingly coalescing around partnerships and API-first strategies to penetrate large accounts without displacing incumbent systems.
Key market participants profiled in our research include prominent EHR and population health vendors, payer-tech integrators, analytics specialists, and emerging ACO enablement firms. Each player has differentiated assets — whether deep EHR integration, AI-driven analytics, payer contracting experience, or operational ACO enablement — that buyers must map to their own maturity and risk-bearing objectives.
What PW Consulting’s full report delivers (practical content for 2026 execution)
Our full report is designed as a hands-on toolkit for senior leaders and their deal teams. The deliverables include:
- Proprietary market sizing and trend models (base 2025; forecast period 2026–2032) with scenario analyses for conservative, central, and aggressive adoption pathways.
- A vendor capability matrix blending commercial footprint, integration posture, regulatory readiness, and typical value propositions for payer and provider procurement teams.
- Go-to-market playbooks for vendor sales leadership, including partner enablement templates, procurement negotiation levers, and win themes tailored to buyer archetypes (e.g., integrated delivery networks, independent physician ACOs, payer-sponsored ACOs).
- Due-diligence checklists and a technical evaluation framework for rapid RFP/rate-card comparison, incorporating security, accreditation, API support, and deployment timelines.
- Financial modeling templates for ACOs and payers that estimate investment payback timelines under alternative shared-savings and downside-risk arrangements.
- Regulatory tracking and scenario planning tied to CMS model updates, accreditation pathways, and emerging payer requirements.
These materials are intentionally operational: they enable product prioritization, M&A screening, procurement standardization, and board-level briefings for capital allocation in 2026.
Actionable strategic imperatives for 2026
- Prioritize real-time capabilities: Product and engineering leaders should accelerate roadmaps toward continuous risk engines and live payer integrations. Short-term investments in event-driven architectures and API certification will materially improve win rates for deals tied to immediate performance objectives.
- Design contracts for shared accountability: Commercial teams must craft contracts that align vendor incentives with ACO outcomes — combining technical SLAs with performance-based components that reflect shared-savings realization and quality metric delivery.
- Build payer partnerships, not just integrations: Strategic alliances with payers — beyond technical interfaces — provide early access to claims feeds, co-developed care pathways, and shift-left population health strategies favored by risk-bearing programs.
- Use accreditation and governance as market differentiators: Vendors that proactively meet ACO accreditation standards and provide buyer-ready governance artifacts will reduce procurement friction and accelerate onboarding.
- Prepare for M&A and alliance opportunities: Given the market’s moderate concentration and rapid growth, 2026 is a window for selective tuck-ins that close capability gaps in real-time analytics, payer connectivity, or care orchestration.
How senior leaders should use this briefing
Executives can use the briefing as a short-form playbook to align cross-functional stakeholders around investment decisions that must be made in 2026. Typical uses include:
- Board and investor update decks that quantify strategic upside under value-based expansion scenarios.
- Product roadmap prioritization to justify resource allocation into cloud-native and API-first capabilities.
- M&A screening to identify target profiles that accelerate entry into payer-integrated or ACO-enablement segments.
- Procurement acceleration: RFP templates and evaluation scorecards to compress vendor selection timelines while elevating outcome alignment.
Where this briefing stops — and why you should access the full report
In keeping with our “trailer” approach, this article surfaces the structural trends, regulatory moments, and strategic levers that will define accountable care market competition in 2026. To preserve competitive integrity and ensure clients receive the precise, transaction-grade inputs they need, we reserve detailed segmentation tables, vendor market shares, and the full suite of financial models for the full report and subscriber portal. The full dataset includes year-by-year market sizing, channel and component splits, and downloadable models that procurement, corporate development, and product teams will rely on for binding decisions.
For companies preparing bids, negotiating contracts, or evaluating M&A in 2026, the full PW Consulting report is the primary source for validated numbers, comparables, and scenario models that boards and investors will require. PW Consulting will also be hosting a subscribers-only webinar and bespoke briefing sessions where our lead analysts walk through the models and facilitate Q&A on strategic applications.
Contact information and access details for the full Worldwide Accountable Care Solutions Market report are available on our website. PW Consulting stands ready to support executive teams with tailored advisory, due diligence support, and implementation roadmaps as organizations convert accountable care strategy into operational outcomes in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Accountable Care Solutions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market to Expand at a 7.15% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s new market study on Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) provides a focused, operationally minded briefing built to inform procurement, manufacturing, and corporate strategy choices in 2026. Anchored on a 2025 base year and a seven‑year forward view (2026–2032), the report synthesizes market sizing, competitive dynamics, regulatory inflection points and supply‑chain levers into a pack of executionable insights. This press release highlights the report’s strategic value while deliberately withholding core segmented datapoints to encourage readers to consult the full deliverable for granular allocations, pricing matrices and supplier scorecards.
Market Snapshot: Growth with Structural Drivers
Following a recovery phase across electronics and specialty chemicals, the NF3 and F2 market reached an inflection point in 2025. Our baseline sizing places the market at approximately USD 1.52 billion in 2025, with a robust compound annual growth rate (CAGR) of 7.15% projected across 2026–2032. Under the baseline scenario, the market is expected to approach the mid‑USD 2.4 billion range by the terminal year of the forecast.
That growth is not uniform: it is concentrated in a small number of high‑technology applications and geographies, and is supported by capex cycles in semiconductor, display, and select specialty chemical segments. The structural picture is therefore one of healthy absolute expansion alongside elevated concentration among a handful of large suppliers — an important combination for buyers and investors to understand when shaping sourcing and investment strategies for 2026.
Why 2026 Is a Pivotal Decision Year
- Capital timing: Equipment and capacity investments initiated in 2026 will come online into a market with multi‑year growth and continued technology migration in semiconductor fabrication—decisions that determine supply security through the next decade.
- Contract design: With raw‑material and logistics volatility elevated, the structure of supply agreements signed in 2026 (indexation, minimums, force majeure clauses) will materially affect TCO and continuity risk.
- Regulatory compliance: New reporting and emission rules enacted recently require operational adjustments that are best scoped and budgeted in 2026 planning cycles.
Key Market Dynamics and Risk Factors
- Concentration and bargaining dynamics: The market demonstrates significant concentration at the top. A small group of suppliers controls the majority of global production capacity, creating asymmetric negotiating leverage for suppliers and underscoring counterparty risk for large buyers.
- Raw‑material and feedstock volatility: Anhydrous hydrogen fluoride (AHF) — a critical feedstock — experienced notable price pressure in late 2024 following supply disruptions. Buyers should assume persistent feedstock cost volatility in short‑term planning and build price adjustment mechanisms into procurement contracts.
- Regulatory tightening: The European regulatory landscape has increased scrutiny on NF3 emissions and reporting obligations, effective from early 2025. This creates compliance cost and monitoring requirements for manufacturers and their suppliers, particularly in high‑emission manufacturing clusters.
- Trade and export controls: Recent expansion of export control measures has changed the flow of F2 and related technologies across some country pairs. The practical effect: buyers who previously relied on single‑country sourcing for specific grades must reassess their cross‑border strategies.
- Logistics and handling costs: F2’s hazardous classification requires specialized cryogenic transport and handling. These constraints add a meaningful uplift to landed cost and influence optimal inventory policies, especially for geographically dispersed manufacturing footprints.
Competitive Landscape — Who Matters and Why
The supplier ecosystem is composed of established industrial gas majors, regional specialty producers and niche manufacturers serving high‑purity electronics applications. The following profiles summarize the strategic positioning and recent moves of the providers that matter to global purchasers and investors.
- Solvay (Belgium) — A global producer of NF3 and advanced F2 grades, Solvay’s strengths lie in industrial scale and product development for pharmaceutical and specialty chemical fluorination. The company launched an upgraded high‑purity F2 grade in 2024, signaling a play to capture higher‑value downstream applications where specification and regulatory traceability matter.
- Air Products (USA) — A major supplier of high‑purity NF3 focused on electronics markets, Air Products has continued to expand regional capacity to meet semiconductor demand. A capacity expansion at its Hsinchu, Taiwan facility in late 2024 underscores the company’s strategy to align production footprints closely with foundry and fab clusters.
- Linde (Germany) — With legacy strengths in gas handling and global supply chains, Linde offers NF3 and F2 with a strong emphasis on operational safety and compliance (recent ISO certification updates). Linde’s network is strategically positioned to serve diversified electronics ecosystems and industrial fluorination users.
- Kanto Denka Kogyo (Japan) — Specializes in ultra‑high‑purity NF3 for LCD and semiconductor manufacturing across Asia. Its regional production hubs provide proximity advantages to major customers in the electronics supply base.
- Hyundai Steel — Green Gas (South Korea) — Supplies NF3 for flat panel display cleaning and F2 derivatives; strategic for buyers operating in the South Korean electronics and display ecosystem due to short lead times and localized technical support.
- Pelchem (Peltzer Group, South Africa) — A key regional producer with global export flows for both NF3 and F2, Pelchem serves niche markets including nuclear and specialty chemical sectors where regulatory pedigree and export documentation are paramount.
- Morita Chemical Industries (Japan) — Focused on high‑purity NF3 grades for semiconductor and solar manufacturing; notable for technical support and tailored purity specifications demanded by advanced fabs.
Together, these players shape the competitive contours of the market. Their recent actions — capacity expansions, product launches and certification efforts — are practical signals of where supply security and quality premiums will concentrate in the coming years.
What PW Consulting’s Report Delivers — Practical Content for Executives
The report is designed for executives and procurement leads who need immediate, implementable inputs for 2026 planning. Key deliverables include:
- Market sizing and a transparent forecasting model (base year 2025) that produces scenario outputs tied to macro and supply‑side shock events.
- Supplier scorecards and a counterparty risk matrix that translate concentration and operational resilience into procurement actions.
- Supply‑chain maps with lead‑time analytics, logistics cost adders for hazardous handling, and recommended inventory models by exposure type.
- Regulatory impact playbooks that align compliance timelines (e.g., recent emissions reporting changes) with CAPEX and process control investments.
- A procurement toolkit with negotiating templates, indexation clause options, and a set of KPIs to monitor contract health and supplier performance.
- Investment decision frameworks for greenfield capacity, strategic off‑takers, and joint‑venture structures tailored to the market’s concentration profile.
- Scenario planning modules that quantify the P&L and continuity impacts of feedstock price shocks, logistics constraints, and export controls.
Each deliverable combines quantitative outputs with qualitative implementation steps — for example, mapping a three‑way hedge between contract tenure, inventory buffers and alternate‑supplier qualification to preserve fab uptime while capping procurement cost exposure.
Actionable Strategic Recommendations for 2026
- Diversify with purpose: Move beyond ad‑hoc multi‑sourcing. Use tiered qualification (primary/secondary/strategic contingency) that matches supplier strengths to application criticality and regulatory risk.
- Re‑engineer contracts: Embed feedstock pass‑through mechanisms, defined escalation ceilings and operational KPIs. Preserve flexibility for re‑routing while locking minimum volumes that secure price stability.
- Invest in upstream visibility: Secure transparency on AHF supply chains and chemical intermediates; consider strategic pre‑payment or offtake to dampen price shocks.
- Operationalize compliance: Treat regulatory changes as a cost and operational contingency. Invest in monitoring and reporting tools now to avoid retrofitting plant controls under compressed timelines.
- Optimize logistics and inventory design: Given specialized transport needs, consider regional hubs and pooled inventories for multi‑site customers to reduce per‑unit logistics premiums.
- Monitor supplier concentration metrics: Track counterparty exposure against leading suppliers and establish trigger points for accelerated mitigation measures when concentration thresholds are breached.
- Consider collaborative CAPEX: For large buyers, co‑investment in regional capacity with trusted suppliers can be the most direct way to lock specification, quality and supply timelines.
How to Use This Insight in Your 2026 Planning Cycle
Procurement leaders should treat PW Consulting’s findings as inputs to three linked processes: 1) contract and inventory policy updates to be completed in Q1–Q2 2026; 2) capex and supplier engagement decisions for the 2026–2027 window; and 3) an enterprise‑level regulatory compliance roadmap aligned to regional rule changes. The report includes actionable checklists and scorecards that can be operationalized directly in supplier review meetings and board‑level investment memos.
Next Steps and Access
This release is a strategic preview intended to outline the report’s operational value. The full PW Consulting Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market report contains the underlying datasets, supplier scorecards, scenario models and segmented forecasting that underpin the recommendations above. For executives preparing budgets, contracts or investment cases in 2026, the complete dataset will be indispensable.
To obtain the full report and supporting templates, please visit the PW Consulting reports page or contact our advisory team to arrange a tailored briefing and model walk‑through. PW Consulting stands ready to convert this market intelligence into a prioritized roadmap that reduces procurement volatility, secures critical supply, and aligns investment choices to long‑term market trajectories.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Energy-Efficient Sludge Treatment Market Set to Grow at 8.85% CAGR
By pmarketresearch, 2026-07-15
Worldwide Energy Efficient Sludge Treatment Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study on Worldwide Energy Efficient Sludge Treatment offers a forward-looking intelligence package designed to inform capital allocation, technology selection, and partnership strategies in 2026. Built on a 2020–2025 historical base with 2025 as the reference year and a 2026–2032 forecast horizon, the report models a sector expanding at an 8.85% compound annual growth rate (CAGR). The market is projected to grow from a 2025 base of USD 5,250 Million to roughly USD 9,505 Million by 2032 — a trajectory that creates both near-term execution imperatives and multi-year strategic opportunities for utilities, technology vendors, private investors, and engineering firms.
Worldwide Energy Efficient Sludge Treatment Market
Why this matters for corporate strategy in 2026
Three dynamics converge to make 2026 a decision point for organizations exposed to sludge management costs and decarbonisation commitments:
Worldwide Energy Efficient Sludge Treatment Market
- Regulatory acceleration — regions are tightening energy and emissions mandates for wastewater operations, pushing sludge treatment from cost-control to strategic decarbonisation levers.
- Technology maturation — energy-efficient thermal and biological pathways (and their hybrid permutations) are crossing from pilots to economically material projects, changing risk profiles for deployment at utility scale.
- Commercial concentration and partnership windows — the market exhibits moderate supplier concentration, which affects procurement leverage, M&A prospects, and alliance formation.
For executive teams, the implication is clear: capital and operating decisions made in 2026 will materially shape regulatory compliance trajectories, P&L energy exposure, and optionality for resource recovery revenues over the next decade.
Worldwide Energy Efficient Sludge Treatment Market
What the report delivers — practical, transaction-focused insight
PW Consulting’s report is not an academic overview. It is structured as a decision support tool for executives and deal teams who must reconcile technical trade-offs and financials on real projects. Key operational sections include:
- Market sizing and forecasting framework — transparent assumptions, sensitivity analyses, and a range-based outlook that supports scenario planning under different policy and energy-price futures.
- Technology deep dives — comparative performance metrics, energy and mass balances, retrofit compatibility, lifecycle emission profiles, and practical limits and prerequisites for anaerobic, thermal hydrolysis, dewatering, and hybrid systems.
- Unit economics and total-cost-of-ownership models — CAPEX/OPEX templates, energy-recovery and offset modelling, and payback/IRR calculators that you can re-run with site-specific inputs.
- Procurement and deployment playbooks — technical evaluation matrices, vendor shortlisting checklists, contract and performance-risk clauses, and commissioning/acceptance protocols tailored to sludge-to-energy projects.
- Regulatory and permitting roadmap — decision timelines and compliance checklists keyed to major frameworks that influence sludge treatment strategy in Europe, the UK, and North America.
- Case studies and field validation — anonymised project dossiers showing baseline conditions, chosen interventions, measured energy performance, and lessons learned on startup and ramp-up.
- M&A, partnership and financing guide — valuation drivers, earnout structures aligned to performance guarantees, and structuring alternatives for project finance vs. corporate investment.
Each of these strands is backed by reproducible models and a set of annexes that include an adaptable Excel workbook for site-level economics, a procurement RFP template, and a regulatory-impact scoring tool for board-level briefings.
Market trajectory and macro takeaways
The energy-efficient sludge treatment market is expanding at a mid-single digit to high-single digit CAGR (8.85% in our central case) through 2032. That pace is being driven by three interlinked forces:
- Policy push — examples include recent EU directives aiming for energy neutrality of wastewater treatment plants on an accelerated timetable, and national commitments such as UK water companies’ net-zero targets that create near-term demand for measurable GHG reductions in sludge operations.
- Operational economics — aeration and biological treatment remain dominant energy consumers in wastewater systems; optimizing sludge processes presents one of the highest-leverage opportunities to reduce plant-level energy intensity.
- Technology stacking — combining digestion, thermal hydrolysis, advanced dewatering, and energy recovery systems is becoming standard for operators seeking energy autonomy or surplus energy generation.
For corporates this means the market is no longer a niche specialist domain — it is a strategic cost and value pool. By 2032, the market size inflection implies meaningful aggregated investment and growing aftermarket services demand for operations & maintenance, performance optimisation, and retrofit execution.
Competitive landscape — who to watch and why
The report’s vendor analysis maps capabilities, deployment footprints, and innovation trajectories of the leading technology and service providers. Highlights include:
- ANDRITZ AG — positioned with adiabatic sludge-treatment and mono-incineration systems that enable self-sustained combustion and district energy integration; a technology option for utilities targeting heat/electricity export without fossil-fuel supplementation.
- Alfa Laval AB — focused on mechanical dewatering and heat-recovery integration; recent strategic partnerships indicate a push toward integrated thermal conversion chains coupled with centrifuge advantages.
- Veolia & SUEZ — global integrators offering end-to-end sludge management, from digestion to biosolids processing, with the ability to combine capex projects with long-term O&M and performance contracts.
- HUBER SE, Flottweg SE, Xylem Inc. — equipment specialists enhancing dewatering efficiency and lowering unit energy consumption through incremental innovation.
- Cambi AS — thermal hydrolysis specialist that materially improves biogas yield and downstream digestion performance, often paired with energy-recovery business cases.
Recent commercial moves underscore a market shifting from point-solutions to integrated systems: major equipment vendors have announced orders and technology partnerships in the past 12–18 months that reflect escalating demand for plant-level energy autonomy and circular-resource outcomes. Market concentration remains moderate (the top-three and top-five supplier shares indicate room for new entrants and consolidation), which preserves both competitive pressure and collaboration opportunities for strategic partners.
Regulatory and policy context shaping 2026 choices
Policy instruments are a critical input to any capex decision. Notable developments captured in the report include:
- EU-level directives tightening energy and emissions performance expectations for wastewater utilities, with compliance timelines that force near-term capital decisions for larger plants.
- National and subnational net-zero commitments (for example, near-term UK targets) that shape procurement criteria and the types of commercial guarantees required by regulators and rate-setting authorities.
- Established frameworks such as the U.S. EPA’s biosolids and land application rules, which continue to influence the acceptable end-uses and regulatory approvals for resource-recovery outputs.
These policy drivers increase the value of technologies which demonstrably reduce GHG intensity while preserving or improving biosolids quality, accelerating adoption cycles for anaerobic and thermal-hybrid approaches.
Five strategic actions for 2026
- Run a site-priority heatmap: use our scoring tool to identify plants with the highest energy-reduction ROI over a 5–7 year horizon and sequence pilots accordingly.
- Prefer modular, staged architectures: select technology stacks that allow pilot-to-scale conversion without stranded asset risk; hybrid architectures ease the regulatory and financing path.
- Lock performance guarantees into procurement: insist on energy and biogas-yield guarantees tied to liquidated damages or shared-savings mechanisms to align incentives.
- Explore partnership structures: for municipalities and smaller utilities, consider joint ventures or long-term concession models with technology vendors to de-risk capex and leverage vendor expertise in O&M.
- Integrate policy scenario planning into business cases: stress-test projects against accelerated decarbonisation scenarios and energy-price sensitivities to protect against downside risk.
How PW Consulting’s report supports your 2026 agenda
The report equips decision-makers with the quantitative templates, comparative vendor intelligence, and regulatory playbooks required to move from strategy to execution in 2026. It is purpose-built for deal teams, plant managers, and public-sector procurement offices seeking defensible, audit-ready analyses to support board approvals and regulatory filings.
To preserve commercial advantage and encourage direct engagement, this briefing highlights strategic findings while reserving detailed regional and application-level splits, unit price decks, and asset-level project models for the full report. These granular data sets and the underlying Excel modelling modules are available in the comprehensive deliverable and on our web portal for licensed clients.
Next steps
If your organisation is evaluating sludge treatment investments or needs to update its decarbonisation roadmap for 2026, PW Consulting can provide bespoke briefings, workshop facilitation, or site-level economic re-runs using the report’s models. Contact our industry practice to schedule an in-depth executive session and to obtain the full report and its reproducible modelling annexes.
For detailed analysis of this topic, please visit the official page: Worldwide Energy Efficient Sludge Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Needle Bearings Market Tops USD 5,200 Million in 2025, Poised for 5.99% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Needle Bearings Market — Strategic Outlook for 2026: A PW Consulting Brief
As manufacturing and mobility sectors enter a decisive investment phase in 2026, needle bearings remain a deceptively simple component with outsized strategic importance. PW Consulting’s newest market study — grounded on a 2020–2025 historical baseline and a 2026–2032 forecast horizon — quantifies how this category is evolving and translates that evolution into practical actions for OEMs, suppliers, investors, and procurement leaders. The headline: the needle bearings market reached approximately USD 5.2 billion in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of roughly 5.99% across the 2026–2032 forecast, underlining steady demand but increasing complexity for participants across the value chain.
Worldwide Needle Bearings Market
What this report delivers — practical, transaction-ready intelligence
- Dynamic market-sizing and trend maps (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario outputs that stress-test growth under alternative macroeconomic and raw-material paths.
- Segment-level frameworks (by product form, application group, and region) that identify structural winners and losers — note: this press summary intentionally omits granular segment tables to preserve the full report’s commercial value.
- Competitor benchmarking and capability matrices covering leading global players and regional specialists, including technology leadership, manufacturing footprint, and go-to-market models.
- Supply-chain and cost structure analysis, featuring bearing-steel input sensitivity, freight and logistics scenarios, and labour/capacity stress tests that can be applied to plant- or SKU-level P&L modeling.
- Actionable playbooks: new-product roadmaps for e-axles and compact powertrains, a supplier selection framework for high-volume programs, an M&A screening checklist, and investment return scenarios for plant upgrades or capacity shifts.
- Interactive decision tools: downloadable Excel models and Monte Carlo sensitivity dashboards that let commercial teams test pricing, mix, and raw-material shocks for their portfolios (available in the full report).
Market trajectory and 2026 implications
The needle bearings market has displayed resilient expansion through the post-pandemic recovery. After a temporary dip in the early-2020s, the category rebounded into a growth trajectory culminating in an estimated market size of USD 5.2 billion in 2025. Under our central forecast, market value continues to expand into 2026 and beyond, reflecting the interplay of three durable structural drivers: (1) continued automotive electrification and the associated demand for compact, high-load bearings in e-axles and transmission sub-systems; (2) accelerated industrial automation and robotics adoption requiring compact precision rolling elements; and (3) OEM and tier-1 emphasis on lightweighting and space-efficient drivetrain components.
Worldwide Needle Bearings Market
For executive teams planning capital, product, or procurement strategy in 2026, two features of the market are immediately relevant. First, growth is meaningful but not exponential — a sub-10% CAGR means leaders must optimize for margin resilience as much as top-line expansion. Second, growth quality is heterogeneous across applications and product technologies: winners will be defined by depth in compact, contamination-tolerant designs and the ability to serve high-volume automotive platforms while also addressing specialized industrial and aerospace needs.
Worldwide Needle Bearings Market
Supply-side dynamics, input cost risk, and concentration
Raw-material dynamics are a central theme for 2026 decision-making. Bearing-grade steel remains a critical input: the broader bearing-steel market is projected to grow materially over the coming decade, reflecting long-term demand for high-purity iron alloys and chromium-bearing steels. Short-term volatility in steel and alloying components — evidenced by recent upticks in global hot-rolled coil prices — is translating into margin pressure unless managed by procurement strategies or product redesigns that reduce steel intensity.
Market concentration is moderate and meaningful: the three-largest firms hold a substantial, but not dominant, share of total market revenue, with the five-largest players cumulatively representing a clear majority. This structure enables regional champions and specialist manufacturers to maintain profitable niches while setting the stage for targeted consolidation and alliance-building. In practice, procurement and corporate development teams should anticipate a market where scale matters for platform wins, but specialized competence (e.g., contamination resistance, ultra-thin cross-sections, or high-volume loose-roller supply) can create defensible margins.
Competitive landscape — capability maps and near-term moves
Our analysis synthesizes product and go-to-market positioning across the industry’s leading firms and several high-impact specialists:
- Schaeffler Group (INA/FAG) — positions itself as a high-precision systems supplier with compact, high load-capacity designs optimized for automotive powertrains and industrial power transmission.
- SKF Group — leverages a broad rolling-bearing portfolio and global service capability, focusing on reliability and friction reduction across industrial and vehicle platforms.
- NTN Corporation — notable for its strategic specialization in e-axle and hybrid vehicle components, developing new configurations targeted at electric powertrains.
- NSK Ltd. — offers a wide product range, including drawn-cup and precision types, with recent exhibition activity signaling a push into MedTech and automation segments.
- Timken Company — brings a heavy-duty performance proposition, emphasizing high-load industrial applications and aftermarket durability.
- JTEKT Corporation (Koyo) — undergoing structural changes in Europe to streamline operations and sharpen focus on competitive segments.
- Regional and niche players (e.g., Universal Bearings, NOSE SEIKO, NRB Bearings, Hartford Technologies) — serve high-volume loose-roller demand, precision assemblies, and custom niches where OEMs prize cost, speed, or unique engineering capabilities.
Recent industry activity confirms these strategic trajectories: leading manufacturers presented at major exhibitions in early 2026, showcasing both incremental product refinements and system-level approaches to contamination control and assembly integration. Corporate restructurings in 2025–2026 among select players reinforce that Europe and other mature markets remain focal points for operational rationalization and platform re-alignment.
Strategic playbook for executives in 2026
- Prioritize platform wins in electrified powertrains but hedge through aftermarket and industrial diversification. Invest selectively in bearing variants and sealing technologies that address contamination-related durability in e-axles.
- Build raw-material resilience: combine medium-term purchase agreements, alternative alloy suppliers, and design-led steel reduction to protect margins against rising bearing-steel costs.
- Optimize footprint with a hybrid nearshoring strategy: retain high-precision lines near core OEMs while outsourcing standardized high-volume manufacturing to cost-effective, quality-controlled partners.
- Target M&A or JVs for capability gaps rather than broadscale roll-ups. Look for acquisitions that add contamination-resistant design, precision cage manufacturing, or proven loose-roller throughput at scale.
- Commercialize service and digital offerings tied to predictive maintenance; bearings are small components, but service contracts and condition-monitoring create recurring revenue and pricing power.
- Implement SKU rationalization guided by cost-to-serve models and platform-revenue forecasts — focus R&D budget on forms and tolerances that align with EV, robotics, and industrial automation roadmaps.
- Scenario-plan for supply shocks: run stress tests in the included Monte Carlo models to identify the breakpoints where price increases or lead-time extensions would necessitate contract renegotiation or redesign.
How to use this report to inform 2026 decisions
PW Consulting designed this study as a working tool for decision-makers. Commercial teams can use the included pricing and mix simulators to evaluate Program Bid/No-Bid decisions. Corporate development groups will find the M&A screening and target scorecards useful when assessing tuck-in acquisitions. Operations and procurement can deploy plant-level cost curves and supplier risk matrices to prioritize investments and second-source strategies.
Importantly, this summary follows a “trailer” principle: it highlights methodologies, directional conclusions, and the strategic implications executives need to act in 2026, while protecting the full dataset and segmented revenue tables that power procurement negotiations and investor diligence. The full report contains the granular segment breakdowns, region- and application-level demand matrices, and supplier scorecards that clients rely on when committing capital or finalizing multi-year supplier agreements.
Next steps — where to get the full intelligence
For leadership teams preparing 2026 budgets, supplier RFQs, or M&A pipelines, the full PW Consulting Worldwide Needle Bearings Market report provides the proprietary models, segment-level forecasts, and company-level benchmarking required to move from analysis to action. The report package includes interactive Excel workbooks, scenario dashboards, and a curated list of actionable due-diligence questions tailored to needle bearings procurement and investment.
Contact PW Consulting to request the full report and accompanying decision tools. Use the intelligence in this study to align product roadmaps, secure supply chains, and prioritize the small but strategically consequential investments that will determine market positioning throughout the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Needle Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com