

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Needle Bearings Market Tops USD 5,200 Million in 2025, Poised for 5.99% CAGR Through 2032

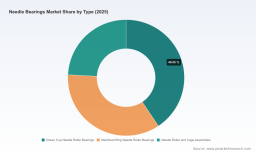
Worldwide Needle Bearings Market — Strategic Outlook for 2026: A PW Consulting Brief
As manufacturing and mobility sectors enter a decisive investment phase in 2026, needle bearings remain a deceptively simple component with outsized strategic importance. PW Consulting’s newest market study — grounded on a 2020–2025 historical baseline and a 2026–2032 forecast horizon — quantifies how this category is evolving and translates that evolution into practical actions for OEMs, suppliers, investors, and procurement leaders. The headline: the needle bearings market reached approximately USD 5.2 billion in our base year (2025) and is projected to grow at a compound annual growth rate (CAGR) of roughly 5.99% across the 2026–2032 forecast, underlining steady demand but increasing complexity for participants across the value chain.
Worldwide Needle Bearings Market
What this report delivers — practical, transaction-ready intelligence
- Dynamic market-sizing and trend maps (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario outputs that stress-test growth under alternative macroeconomic and raw-material paths.
- Segment-level frameworks (by product form, application group, and region) that identify structural winners and losers — note: this press summary intentionally omits granular segment tables to preserve the full report’s commercial value.
- Competitor benchmarking and capability matrices covering leading global players and regional specialists, including technology leadership, manufacturing footprint, and go-to-market models.
- Supply-chain and cost structure analysis, featuring bearing-steel input sensitivity, freight and logistics scenarios, and labour/capacity stress tests that can be applied to plant- or SKU-level P&L modeling.
- Actionable playbooks: new-product roadmaps for e-axles and compact powertrains, a supplier selection framework for high-volume programs, an M&A screening checklist, and investment return scenarios for plant upgrades or capacity shifts.
- Interactive decision tools: downloadable Excel models and Monte Carlo sensitivity dashboards that let commercial teams test pricing, mix, and raw-material shocks for their portfolios (available in the full report).
Market trajectory and 2026 implications
The needle bearings market has displayed resilient expansion through the post-pandemic recovery. After a temporary dip in the early-2020s, the category rebounded into a growth trajectory culminating in an estimated market size of USD 5.2 billion in 2025. Under our central forecast, market value continues to expand into 2026 and beyond, reflecting the interplay of three durable structural drivers: (1) continued automotive electrification and the associated demand for compact, high-load bearings in e-axles and transmission sub-systems; (2) accelerated industrial automation and robotics adoption requiring compact precision rolling elements; and (3) OEM and tier-1 emphasis on lightweighting and space-efficient drivetrain components.
Worldwide Needle Bearings Market
For executive teams planning capital, product, or procurement strategy in 2026, two features of the market are immediately relevant. First, growth is meaningful but not exponential — a sub-10% CAGR means leaders must optimize for margin resilience as much as top-line expansion. Second, growth quality is heterogeneous across applications and product technologies: winners will be defined by depth in compact, contamination-tolerant designs and the ability to serve high-volume automotive platforms while also addressing specialized industrial and aerospace needs.
Worldwide Needle Bearings Market
Supply-side dynamics, input cost risk, and concentration
Raw-material dynamics are a central theme for 2026 decision-making. Bearing-grade steel remains a critical input: the broader bearing-steel market is projected to grow materially over the coming decade, reflecting long-term demand for high-purity iron alloys and chromium-bearing steels. Short-term volatility in steel and alloying components — evidenced by recent upticks in global hot-rolled coil prices — is translating into margin pressure unless managed by procurement strategies or product redesigns that reduce steel intensity.
Market concentration is moderate and meaningful: the three-largest firms hold a substantial, but not dominant, share of total market revenue, with the five-largest players cumulatively representing a clear majority. This structure enables regional champions and specialist manufacturers to maintain profitable niches while setting the stage for targeted consolidation and alliance-building. In practice, procurement and corporate development teams should anticipate a market where scale matters for platform wins, but specialized competence (e.g., contamination resistance, ultra-thin cross-sections, or high-volume loose-roller supply) can create defensible margins.
Competitive landscape — capability maps and near-term moves
Our analysis synthesizes product and go-to-market positioning across the industry’s leading firms and several high-impact specialists:
- Schaeffler Group (INA/FAG) — positions itself as a high-precision systems supplier with compact, high load-capacity designs optimized for automotive powertrains and industrial power transmission.
- SKF Group — leverages a broad rolling-bearing portfolio and global service capability, focusing on reliability and friction reduction across industrial and vehicle platforms.
- NTN Corporation — notable for its strategic specialization in e-axle and hybrid vehicle components, developing new configurations targeted at electric powertrains.
- NSK Ltd. — offers a wide product range, including drawn-cup and precision types, with recent exhibition activity signaling a push into MedTech and automation segments.
- Timken Company — brings a heavy-duty performance proposition, emphasizing high-load industrial applications and aftermarket durability.
- JTEKT Corporation (Koyo) — undergoing structural changes in Europe to streamline operations and sharpen focus on competitive segments.
- Regional and niche players (e.g., Universal Bearings, NOSE SEIKO, NRB Bearings, Hartford Technologies) — serve high-volume loose-roller demand, precision assemblies, and custom niches where OEMs prize cost, speed, or unique engineering capabilities.
Recent industry activity confirms these strategic trajectories: leading manufacturers presented at major exhibitions in early 2026, showcasing both incremental product refinements and system-level approaches to contamination control and assembly integration. Corporate restructurings in 2025–2026 among select players reinforce that Europe and other mature markets remain focal points for operational rationalization and platform re-alignment.
Strategic playbook for executives in 2026
- Prioritize platform wins in electrified powertrains but hedge through aftermarket and industrial diversification. Invest selectively in bearing variants and sealing technologies that address contamination-related durability in e-axles.
- Build raw-material resilience: combine medium-term purchase agreements, alternative alloy suppliers, and design-led steel reduction to protect margins against rising bearing-steel costs.
- Optimize footprint with a hybrid nearshoring strategy: retain high-precision lines near core OEMs while outsourcing standardized high-volume manufacturing to cost-effective, quality-controlled partners.
- Target M&A or JVs for capability gaps rather than broadscale roll-ups. Look for acquisitions that add contamination-resistant design, precision cage manufacturing, or proven loose-roller throughput at scale.
- Commercialize service and digital offerings tied to predictive maintenance; bearings are small components, but service contracts and condition-monitoring create recurring revenue and pricing power.
- Implement SKU rationalization guided by cost-to-serve models and platform-revenue forecasts — focus R&D budget on forms and tolerances that align with EV, robotics, and industrial automation roadmaps.
- Scenario-plan for supply shocks: run stress tests in the included Monte Carlo models to identify the breakpoints where price increases or lead-time extensions would necessitate contract renegotiation or redesign.
How to use this report to inform 2026 decisions
PW Consulting designed this study as a working tool for decision-makers. Commercial teams can use the included pricing and mix simulators to evaluate Program Bid/No-Bid decisions. Corporate development groups will find the M&A screening and target scorecards useful when assessing tuck-in acquisitions. Operations and procurement can deploy plant-level cost curves and supplier risk matrices to prioritize investments and second-source strategies.
Importantly, this summary follows a “trailer” principle: it highlights methodologies, directional conclusions, and the strategic implications executives need to act in 2026, while protecting the full dataset and segmented revenue tables that power procurement negotiations and investor diligence. The full report contains the granular segment breakdowns, region- and application-level demand matrices, and supplier scorecards that clients rely on when committing capital or finalizing multi-year supplier agreements.
Next steps — where to get the full intelligence
For leadership teams preparing 2026 budgets, supplier RFQs, or M&A pipelines, the full PW Consulting Worldwide Needle Bearings Market report provides the proprietary models, segment-level forecasts, and company-level benchmarking required to move from analysis to action. The report package includes interactive Excel workbooks, scenario dashboards, and a curated list of actionable due-diligence questions tailored to needle bearings procurement and investment.
Contact PW Consulting to request the full report and accompanying decision tools. Use the intelligence in this study to align product roadmaps, secure supply chains, and prioritize the small but strategically consequential investments that will determine market positioning throughout the 2026–2032 cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Needle Bearings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com