

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hardbanding Services Market to Expand at 5.1% CAGR (2026–2032), Peaking at USD 639.74 Million in 2031

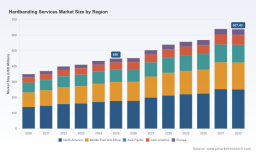
Worldwide Hardbanding Services Market — Strategic Intelligence to Guide 2026 Decisions
PW Consulting’s new market briefing on Worldwide Hardbanding Services synthesizes proprietary modelling, primary interviews, and on-the-ground service-provider intelligence to help C-suite leaders and investment teams make disciplined decisions in 2026. The hardbanding services market, having risen steadily through the early 2020s, stood at approximately USD 450 million in our 2025 base year and is modelled to grow at a steady compound annual growth rate (CAGR) of 5.1% across the 2026–2032 forecast window, reaching roughly USD 637 million by the end of the period. This release presents the strategic implications of that trajectory and highlights the operational levers executive teams should prioritize — without disclosing the granular segment tables contained in the full report.
Worldwide Hardbanding Services Market
Executive summary — why this matters in 2026
- Durability-driven demand: Increased upstream activity and an intensified focus on lowering cost-per-foot drilled mean operators will continue to prioritise tool-joint protection and service models that extend drill string life.
- Margin pressure from inputs: Volatility in wear-materials (notably tungsten carbide) and the evolving alloy mix will influence provider cost structures and pricing power.
- Certification and standards: Approval regimes are becoming decisive commercial differentiators — vendors with recognized approvals see easier operator uptake and premium positioning.
- Service model differentiation: Mobile applicator networks, certified shop capabilities, and value-added inspection & reporting are the primary levers to capture share.
Market trajectory and key macro drivers
The hardbanding market has demonstrated resilient growth since 2020, reflecting a combination of recovering drilling activity and a structural push toward lifecycle-cost reduction for drill strings. Our historical series (2020–2025) shows a steady increase in overall market spend as operators re-prioritise asset longevity and maintenance optimisation. Looking forward, the 5.1% CAGR we model for 2026–2032 is a function of modest E&P expansion in targeted basins, incremental adoption of higher-performance alloys, and a maturing replacement cycle for legacy service models.
Worldwide Hardbanding Services Market
Two macro considerations will shape near-term strategy:
Worldwide Hardbanding Services Market
- Input-cost dynamics: Tungsten carbide remains a critical raw material for many wear-resistant alloys. By Q4 2025 tungsten carbide prices reached approximately USD 57/kg, and the broader tungsten carbide market exceeded the multi-billion-dollar mark in 2025 — trends that speak to both supply tightness and the strategic importance of procurement and material substitution strategies for service providers.
- Standards & approvals: Industry-standard approvals (for example, recent Fearnley Group NS-1 approvals) are not only technical badges; they materially affect re-application permissions, operator acceptance, and contract awarding. Firms that secure widely recognised certifications shorten commercial lead times and command premium positioning.
Competitive landscape — positioning the leading players
The market remains moderately concentrated, with several technology and service specialists commanding meaningful share through differentiated alloys, applicator networks, and integrated service offerings. The competitive set spans global alloy innovators and regional mobile-service specialists. Key strategic characteristics of leading participants include:
- Postle Industries / Hardbanding Solutions (Cleveland, OH): A global leader in casing-friendly, crack-free alloys (e.g., proprietary Duraband variants) and end-to-end application solutions. Their focus on product performance and recent certifications has reinforced operator trust — a model that incumbents and challengers should seek to emulate through validated field performance and re-application pathways.
- Arnco Technology (Houston, TX): Specialist alloy development, including heatless tungsten-carbide options and robust applicator networks. Arnco’s technical depth around heatless and premium alloy formulations positions it well for high-spec applications and partnerships with field service providers.
- National Oilwell Varco (NOV) / Tuboscope (Houston, TX): Integration of hardbanding consumables with inspection, pipe services, and aftermarket offerings creates a bundled value proposition. NOV’s strength is in providing a one-stop solution linking application, inspection, and data — an attractive playbook for operators seeking simplified vendor management.
- Castolin Eutectic (Lausanne, Switzerland, global ops): Offers a broad wire portfolio and demonstrated capability in testing for abrasion, erosion, and sour-service conditions. Their laboratory-backed casing wear simulations underpin credibility for high-risk use cases.
- Regional/mobile specialists (e.g., Hard Band Industries, Pro‑Tech, Thompson & Thompson, Bandit Tech, Tech Energy): These providers combine shop and portable on-site capabilities, focused regional coverage, and rapid deployment models. Their competitive advantage is logistical agility and local relationships — valuable where time-to-service is a key operator constraint.
Strategic implication: partnerships between global alloy innovators and regional service operators are the most likely route to rapid commercial scale. Investors should prioritise platforms that blend proprietary consumables with scalable applicator networks and digital reporting.
Service models, technology trends and regulatory impacts
Two technical pathways dominate the innovation narrative: alloy evolution (including chromium- and titanium-enabled metals) and application technique (cored-wire vs. manual welding vs. heatless carbide deposition). The market is seeing incremental but material migration toward casing-friendly alloys that reduce secondary casing damage while delivering wear resistance. Simultaneously, demand for non-magnetic and low-distortion processes is rising in response to directional and complex-well programmes.
Regulatory and standards developments have also shifted the competitive landscape. Approvals such as Fearnley Group NS-1 play a deterministic role in enabling re-application over previous hardbanding layers and in operator supplier-selection processes. Our field interviews underscore that certification timelines are now a gating factor for commercialisation; securing approvals can materially accelerate uptake in operator fleets.
Supply chain and margin considerations
Input prices and raw-material availability are primary drivers of provider margin volatility. With tungsten carbide dynamics evident in late‑2025, service providers should consider three concrete mitigations:
- Hedging or contractual procurement strategies with primary carbide suppliers to stabilise cost of goods sold;
- R&D investment into alloy formulations that optimise tungsten-carbide loading without sacrificing life-cycle performance;
- Operational efficiency programmes — from improved application yield to reduced rework — that insulate gross margins from raw-material swings.
Actionable playbook for 2026
The market intelligence contained in PW Consulting’s briefing translates into immediate, actionable priorities for operators, service providers, and investors preparing for 2026.
- For operators (E&P companies and drill contractors): Consolidate supplier panels around vendors with both validated performance data and recognised approvals; pilot alloys in lower-risk wells before fleet-scale rollouts; demand transparent life-cycle cost modelling (not just price-per-application).
- For service providers: Invest in certification pathways and applicator training to convert product R&D into commercial adoption; deploy modular mobile units in high-opportunity basins; bundle inspection and digital reporting to create stickier service contracts.
- For OEMs and consumable manufacturers: Prioritise alloy formulations that reduce dependence on high-cost inputs, and pursue strategic alliances with regional applicators to accelerate field penetration.
- For financial sponsors and M&A teams: Target platform investments that combine proprietary consumables with scalable applicator footprints; value accrual will primarily come from consolidation of mobile service fleets, cross-selling of inspection services, and vertical integration into consumables supply.
About the report — practical content that supports decision execution
PW Consulting’s full Worldwide Hardbanding Services Market report (2026–2032 forecast) is structured to be directly actionable for deal teams and operating executives. Key deliverables include:
- Executive dashboards and scenario models calibrated to macro and basin-level drilling outlooks;
- Proprietary cost-to-serve and price-benchmark frameworks that convert product specifications into margin implications;
- Vendor scorecards and capability matrices including applicator networks, certification status, and service-level benchmarks;
- Operational playbooks for deploying mobile units, setting up shop capabilities, and field-testing new alloys;
- M&A diligence templates and valuation sensitisation tied to raw-material exposure and service mix;
- Implementation roadmaps for certification sequences and operator acceptance trials.
In keeping with our “trailer” approach, this communication intentionally showcases the report’s analytical depth while omitting the granular segment tables and region-application splits that form the core of the dataset. Those tables, and the underlying primary-data matrices, are contained in the full report and in the interactive models we deliver to clients.
Closing — how PW Consulting can support your 2026 agenda
For executive teams making capex, procurement, or M&A decisions in 2026, the right intelligence is both top-line directional and operationally prescriptive. PW Consulting’s briefing bridges that gap: it combines market sizing and growth trajectories with vendor-level insight, certification risk analysis, and executable playbooks to reduce time-to-value. If your team is prioritising hardbanding strategy in 2026 — whether to optimise fleet economics, scale a service platform, or identify buy-side targets — PW Consulting can provide a focused briefing and interactive workshop to translate the market picture into a one- to three-year plan.
Contact our industry team for an executive briefing and to obtain the full report and models. The full dataset contains the granular segment and regional detail required to complete transactional diligence and operational planning.
For detailed analysis of this topic, please visit the official page: Worldwide Hardbanding Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com