

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report Finds Worldwide Heavy Equipment Maintenance Service Market Poised for 5.34% CAGR Through 2032
By pmarketresearch, 2026-07-15
PW Consulting: Strategic Brief — Worldwide Heavy Equipment Maintenance Service Market (2026 Outlook)
Executive summary
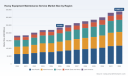
PW Consulting today releases a strategic brief derived from our forthcoming report, Worldwide Heavy Equipment Maintenance Service Market (base year 2025, forecast 2026–2032). The global market for heavy equipment maintenance services reached an estimated USD 235.4 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.34% across the forecast window, moving toward an expected market size in excess of USD 338.8 billion by 2032. Our analysis shows a structurally fragmented services ecosystem, where the top providers capture only a limited share of total revenues — a fact that has important implications for market-entry timing, consolidation strategies and differentiated service propositions.
Worldwide Heavy Equipment Maintenance Service Market
This brief is designed as a strategic “trailer”: it distills the report’s most consequential insights for executive decision-makers in 2026 while intentionally withholding granular regional and end‑use splits to prompt direct engagement with the full report for transaction‑level planning and competitive benchmarking.
Worldwide Heavy Equipment Maintenance Service Market
Why this matters for 2026 decision-makers
- Market scale and momentum: The services market is large, liquid and growing steadily. A mid-single-digit CAGR translates into considerable absolute revenue expansion each year — enough to justify multi-year investments in network expansion, telematics and workforce upskilling for market leaders and new entrants alike.
- Fragmentation equals opportunity: Low top‑tier concentration creates runway for consolidation and for specialized service models (e.g., site-dedicated fleets, mobile overhaul units, subscription uptime contracts). Private equity and strategic acquirers can secure regional platforms at attractive multiples if they execute disciplined integration playbooks.
- Digital is table stakes — but differentiated: Telematics, predictive analytics and integrated maintenance management software are rapidly shifting the value chain from reactive repair to uptime-guaranteed service offerings. Early adopters who combine field capability with data-driven service pricing will extract higher margins and stronger customer retention.
- Labour and regulation are immediate risk levers: Rising technician wages, persistent staffing shortages and updated safety/regulatory requirements materially affect cost-to-serve models and compliance exposure for operators and service contractors.
What the PW Consulting report delivers (practical, action-ready content)
- Market sizing and validated forecasts (2020–2032), with scenario analysis across demand shock, technology adoption and regulatory outcomes.
- Service model taxonomies and cost-to-serve templates for Preventive, Corrective and Predictive services — including margin benchmarking, break-even analyses and price‑to‑value frameworks.
- Competitive intelligence dossiers for leading OEMs, independents and software vendors, with capability maps, service footprints and M&A trackers.
- Operational playbooks for scaling field service — mobile workforce planning, depot footprint optimization, parts logistics redesign and service-level agreements (SLA) that preserve uptime while protecting margins.
- Technology due diligence checklists for telematics, maintenance management platforms and predictive analytics pilots, plus integration roadmaps to realize ROI within 12–24 months.
- Regulatory and labour impact models quantifying sensitivity to wage inflation, certification regimes and documentation requirements — enabling scenario-based capital and headcount planning.
- Deal support materials: target screening frameworks, valuation comparables, integration risk matrices and a phased 100‑day plan for maintenance‑focused buy-and-build strategies.
Competitive landscape — themes and implications
The service ecosystem is shaped by a mix of multinational OEMs, global dealers, regional independents and software providers. OEM networks (led by long‑standing manufacturers) leverage dealer footprints, genuine parts supply and embedded telematics to defend installed fleets. Notable players include established OEMs with global service networks as well as specialist engine and software firms that are reshaping value capture.
Worldwide Heavy Equipment Maintenance Service Market
- Caterpillar: A leader in integrated maintenance offerings combining dealer support, parts availability and telematics-enabled predictive diagnostics. Their scale underpins broad service contracts and rebuild programs that set industry benchmarks.
- Komatsu: Strong dealer-backed preventive programs and remote equipment monitoring capabilities are core strengths. Komatsu’s model emphasizes lifecycle contracts aligned with machine uptime guarantees.
- Volvo Construction Equipment & John Deere: Each leverages telematics ecosystems to deliver uptime services and scheduled maintenance programs—a model that favors close OEM-fleet integration and recurring revenue.
- Liebherr, Hitachi, SANY and XCMG: Their global service networks and component overhaul capabilities signal an intensifying non-OEM competitive field—particularly in regional markets where local service density and parts logistics are decisive.
- DEUTZ Corporation: Recent acquisition activity underscores an aggressive push by specialist engine and powertrain suppliers to broaden full-machine maintenance capability and geographic reach — a trend we expect to accelerate.
- HCSS and Fleetio: Software vendors are pivotal enablers. Their maintenance-management platforms and telematics integrations are becoming standard interfaces between fleet operators and service providers; strategic partnerships or interoperability are now key defensive moves.
Taken together, these players illustrate two convergent dynamics: (1) OEMs and large dealers defend installed bases via integrated hardware‑software-service bundles; and (2) specialist independents and software firms exploit gaps in local coverage and software intercompatibility to capture profitable niches. The market is open to consolidation, but successful acquirers must execute tight integration on logistics, parts, and people.
Market dynamics and short-term risks to model in 2026
- Labour cost pressure: Technician wages and labour rates rose markedly in the recent period. Shops report staffing shortages and rising wage bills — a structural headwind to margins for labor‑intensive service models unless offset by productivity gains or price adjustments.
- Technician supply gap and demographic challenge: An aging workforce and below‑average inflows of younger technicians create training and retention imperatives. Upskilling, apprenticeship partnerships and retention programs should be budgeted as capital investments rather than recurring HR expenses.
- Regulatory tightening: New regulations emphasizing digital documentation, operator certification, and safety compliance increase administrative burden and compliance cost; however, they also raise barriers to entry for informal service providers, favoring well-capitalized and certified operators.
- Consolidation & M&A activity: Strategic acquisitions (including recent engine‑repair rollups) indicate growing appetite for platform plays that combine geographic reach, parts inventory and repair capability. Buyers must stress-test integration assumptions on parts obsolescence and warranty liabilities.
Strategic playbook — recommended moves for 2026
- For OEMs and large dealers: Prioritize telematics-first service bundles, establish performance-based SLAs, and pilot outcome-linked pricing (e.g., uptime guarantees). Use parts availability as a competitive moat and invest in predictive-maintenance service centers at high-density locations.
- For independents and regional service groups: Compete on responsiveness and price-to-uptime trade-offs. Invest in mobile overhaul units, standardized diagnostic toolkits and partnerships with software vendors to offer data-driven predictive services without heavy capex.
- For fleet owners and rental operators: Reassess make-vs-buy for maintenance. Consider hybrid models that combine internal preventive maintenance with outsourced corrective and overhaul services to optimize cash flow and uptime.
- For investors and acquirers: Target bolt‑on acquisitions that add parts inventory density or strategic geographies, and model labour risk explicitly. Valuation should reflect integration cost, parts synergies and service revenue stickiness post-acquisition.
How PW Consulting supports clients
PW Consulting provides end-to-end advisory services tied directly to the findings in this report: transaction due diligence; commercial and operational carve‑outs; go‑to-market and pricing strategy; telematics and predictive‑maintenance technology selection; field‑service transformation; and implementation support for M&A integration. We combine proprietary market data, on-the-ground capability audits and quant models to convert the market’s scale and trends into executable programs that preserve cash and accelerate service revenue growth.
Next steps — obtain the full report
This brief highlights strategic inflection points and practical levers for 2026, but it is only a preview. The full Worldwide Heavy Equipment Maintenance Service Market report contains the detailed regional and end‑use segmentation, vendor scorecards, modeled scenarios and downloadable data tables required for execution-level planning and transaction diligence. To access the complete analysis, including our proprietary datasets and the granular segmentation that informs investment and operating decisions, please visit the PW Consulting publications page or contact our advisory team for a tailored briefing.
PW Consulting’s senior industry analysts remain available for confidential briefings with boards, investors and executive teams to translate these findings into 90‑, 180‑ and 360‑day action plans tailored to your organization’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Equipment Maintenance Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Anti‑Tank Missile System Market to Expand at 5.2% CAGR, Hitting USD 10.27 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Anti-Tank Missile System Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study provides a forward-looking, decision-focused view of the global anti-tank missile systems market. Grounded in a rigorous review of 2020–2025 performance and modeled across multiple demand and supply scenarios for 2026–2032, the report gives defense planners, program managers, investors and OEM executives the strategic context they need to prioritize investments and design procurement strategies for the coming planning cycle.
Worldwide Anti-Tank Missile System Market
Data-driven market outlook
The global anti-tank missile systems market has shown sustained growth through the early 2020s, rising from a mid-single-digit billion USD base in 2020 to a base-year total of approximately USD 7.2 billion in 2025. Our forecast, driven by platform modernization, allied replenishment programs and expanded procurement from emerging buyers, projects a compound annual growth rate (CAGR) of 5.2% across the 2026–2032 forecast window. Under the baseline scenario, the market advances to just over USD 10.2 billion by 2032, with intermediate-year dynamics reflecting both cyclical procurement awards and discrete capacity expansions announced by key suppliers.
Worldwide Anti-Tank Missile System Market
Two observations from the topline data are critical for 2026 planning:
Worldwide Anti-Tank Missile System Market
- The market’s steady historical growth demonstrates resilience to short-term geopolitical shocks, but continued expansion depends on repeatable production profiles and accessible supply chains for advanced materials and electronics.
- Concentration is high: the market is meaningfully consolidated among a small group of established tier‑one prime contractors and strategic national suppliers. This concentration creates both supply-side stability and tactical procurement risk, depending on the geopolitical alignment of buyers and producers.
Why this matters for 2026 strategic decisions
As defense budgets stabilize and modernization programs move from concept to contract, 2026 will be a pivotal year to lock in capability roadmaps and industrial partnerships. Our study translates market growth and supplier dynamics into three decision levers that will shape competitive outcomes:
- Manufacturing scale and flexibility — Organizations that secure production capacity, automation investments, and supplier commitments in 2026 will gain a two‑to‑three year advantage as demand spikes from both replacement orders and allied foreign military sales.
- Supply chain strategic sourcing — Dependence on high-temperature alloys, rare earth magnets, composites and miniature electronics creates choke points. Procurement and program managers must prioritize dual-sourcing, strategic stockpiles and qualified substitutes to avoid schedule risk.
- Integration and lifecycle economics — With systems being mounted across dismounted, vehicle and airborne platforms, decision-makers must weigh not only unit cost but integration cost, training, and sustainment. Early engagement on modular interfaces and common support equipment reduces total cost of ownership over contract horizons.
Competitive landscape — who matters and why
Our competitive assessment identifies the strategic roles of the market’s leading firms and the implications for buyers and investors. Key findings include:
- Prime western manufacturers and multinational joint ventures dominate high-end, fire-and-forget capabilities and top-attack profiles. Their scale, long-term DoD and allied contracts, and integrated supply chains underpin near-term supply reliability.
- Regional and state-owned producers are competitive on cost and localized support, and they play a critical role where offset agreements, technology transfer, or sovereign production are procurement requirements.
- Specialist subsystem players — electro-optics, guidance electronics and advanced propellants — have outsized leverage in program structuring and are frequent targets for strategic partnerships or vertical integration by primes seeking to secure supply.
Representative company profiles in the study (not exhaustive) include tier‑one primes and influential regional suppliers. For example:
- Lockheed Martin (Javelin JV) and RTX — co-production arrangements and long-term contracts underpin high-volume man-portable and heavy-tube solutions, with recent supply‑chain expansion and production contracts indicating continued demand and investment in manufacturing automation.
- Rafael and MBDA — leaders in electro-optical guided families and multi-mode engagement options; active in multi-national production and integration programs.
- Roketsan, Denel Dynamics, Saab and Bharat Dynamics — regional champions offering competitive alternatives and serving as important partners for localized procurement strategies.
- Subsystem and integrator players such as Elbit Systems, Diehl, KBP and General Dynamics — their roles range from guidance modules and warhead technologies to vehicle integration and system-of-systems enablement.
Recent program and supply signals to watch in 2026
Our report synthesizes headline events that illustrate market momentum and risk. Example developments include multi-year production awards for legacy heavy systems, supplier-led capacity expansions for high-demand man‑portable systems, and deliveries under foreign military sales and export contracts. These program flows validate demand and create near-term capacity constraints that can influence pricing, lead times and partnership choices.
Supply chain, materials and production risk analysis
The study’s segment-level risk matrix highlights a few non-obvious but high-impact vulnerabilities:
- Critical materials: rare earth elements for guidance motors and specialty alloys for propulsion and warheads concentrate sourcing risk. Small changes in availability or export policy can ripple into program schedules.
- Production scale-up: expanding missile output is not simply a matter of adding labor — long lead items, qualification cycles for suppliers and test-range capacity impose calendar risk that must be managed years in advance.
- Regulatory and political overlay: major supplier nations’ procurement policies, export controls and alliance politics materially shift options for buyers seeking diversification or local industrial participation.
Operational and procurement playbook for 2026
The report offers an operational playbook for program managers and defense investors, emphasizing practical steps to convert market insight into decisions:
- Short horizon (0–18 months): secure long‑lead components, prioritize supplier audits for critical subsystems, and negotiate flexible lot structures in new contracts to handle demand variance.
- Medium horizon (18–36 months): invest in automation and test-capacity partnerships, pursue strategic co-production or licensed manufacturing arrangements where sovereign capability is required, and incorporate sustainment cost metrics into award criteria.
- Strategic horizon (3–7 years): assess M&A or JV opportunities to obtain rare-earth processing access, expand modular architectures to enable capability upgrades without complete system replacements, and align R&D investments with anticipated countermeasures and active protection system trends.
What the report contains — practical deliverables
PW Consulting’s study is designed as an executable resource rather than a descriptive overview. Deliverables include:
- Topline historical and forecast market sizing with scenario modeling (base, accelerated demand, disruption), and sensitivity analysis tied to procurement policies and geopolitical trajectories.
- Consolidation and competitive scoring: supplier benchmarking across capability, capacity, exportability and industrial offset potential; an executable short-listing tool for sourcing decisions.
- Supply-chain heat maps and risk mitigation templates for critical materials and subsystems, with prioritized contingency options and estimated lead-time impacts.
- Procurement playbooks: sample contract language, lot-sizing strategies, and integration checklists to reduce schedule and TCO risk.
- Program-level total cost of ownership (TCO) models and scenario-based budgetary impacts for platform integrators and fleet sustainment managers.
How PW Consulting’s insight changes the calculus in 2026
For defense buyers and executives, our central conclusion is straightforward: market growth is real and steady, but value will accrue to organizations that pair access to capacity with supply‑chain resilience and integration discipline. Firms that wait for procurement peaks before securing suppliers will face higher cost and schedule risk. Conversely, buyers who use 2026 to lock in flexible production arrangements and dual‑sourcing for critical materials will preserve options and improve bargaining power.
Accessing the full analysis
This press preview outlines the strategic contours of the market and the report’s practical value. It intentionally omits granular sub‑segment allocations and detailed supplier financials that are included in the full study to preserve the analytical core for licensed readers. For procurement teams, investor committees and program offices preparing 2026 budgets and industrial strategies, the full report provides the proprietary stratagems, supplier scorecards and contract templates needed to translate forecasting into executable plans.
PW Consulting invites interested stakeholders to review the complete Worldwide Anti-Tank Missile System Market report for the in-depth data tables, segment breakdowns, supplier matrices and scenario workpapers that inform the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Tank Missile System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Digestive Bitters Market to Reach USD 2,390 Million by 2032, Growing at a 5.48% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Digestive Bitters Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest Worldwide Digestive Bitters Market study provides a clear line of sight into a category undergoing steady, consumption-driven expansion and strategic repositioning. The global market — valued at approximately USD 1.65 billion in our base year (2025) — is projected to expand at a compound annual growth rate (CAGR) of 5.48% over the 2026–2032 forecast window, reaching roughly USD 2.39 billion by 2032. For executives planning portfolios, channel strategies, or M&A activity in 2026, this report is designed to convert broad market momentum into concrete, defensible choices — while conserving proprietary segmentation metrics to preserve competitive advantage.
Worldwide Digestive Bitters Market
Why this market matters for 2026 planning
-
Consumer wellness trends continue to push bitters beyond cocktail culture into everyday digestive and functional health routines. This transition creates adjacent opportunities across formulation, claims architecture, and retailer assortment strategies.
Worldwide Digestive Bitters Market -
Supply-chain dynamics for botanical inputs and the regulatory overlay in key markets are evolving rapidly; companies that align sourcing, quality assurance, and compliance in 2026 will build durable moats.
Worldwide Digestive Bitters Market -
The category remains commercially accessible: brand heritage and craft authenticity can coexist with modernized, evidence-informed positioning. This makes bitters an attractive target for both FMCG and natural-health investors.
Key market dynamics and growth levers
-
Demand synergy across occasions: While bitters retain a heritage role in beverage and cocktail innovation, incremental growth is driven by daily digestive-use propositions — formulations positioned for bloating, indigestion, and liver-support routines. Expect cross-category marketing to accelerate adoption among mainstream wellness consumers.
-
Formulation portability: Liquid bitters continue to dominate shelf space due to ease of dosing and culinary versatility, but tablets, capsules, and powdered concentrates are gaining traction among consumers seeking convenience and travel-friendly formats.
-
Retail and omnichannel evolution: Specialty retailers and online channels are the innovation frontiers — they enable storytelling and trial at lower direct-to-consumer acquisition costs. Hypermarkets retain broad reach, but 2026 should be viewed as a year to invest selectively in digital conversion and subscription models.
-
Ingredient provenance and traceability: High-profile brands emphasize rigorous sourcing standards for bittering botanicals (gentian, dandelion, artichoke, burdock, orange peel, etc.). Supply transparency is quickly becoming a baseline expectation rather than a premium differentiator.
Regulatory and clinical context — navigating complexity
-
Real-world evidence is entering the conversation: A Swiss real-world prescription database study (published early 2026) demonstrates that herbal bitters are present in integrative care pathways — either as registered medicinal products or as magistral preparations manufactured under GMP. For companies seeking to move from supplement to prescribable product, this study both legitimizes the pathway and highlights the regulatory complexity.
-
Labeling and claims constraints: In jurisdictions such as the United States, digestive bitters sold as supplements must adhere to regulatory disclaimers and will face scrutiny over therapeutic claims. In 2026, firms that invest in robust clinical or real-world evidence strategies will have a differential advantage when negotiating retailer listings or pursuing cross-border expansion.
Competitive landscape — heritage brands vs. modern naturals
The market architecture blends long-established spirit-affiliated names with newer organic and herbal specialists. This juxtaposition creates predictable playbooks for incumbents and challengers alike.
-
Heritage incumbents — Brands with multi-decade legacies bring authenticity, global distribution relationships, and recipe IP. Their strengths lie in brand equity and cocktail-culture relevance; their challenge is modernizing positioning to capture everyday digestive use-cases without diluting heritage appeal.
-
Natural and organic specialists — Smaller players built on certified-organic botanicals and clinical-adjacent storytelling are winning consumer trust in the wellness channel. Their agility in product innovation and transparency over sourcing enables premium pricing, but scale and distribution breadth remain constraints.
Representative players analyzed in our report include long-standing producers with historic formulations, and wellness-forward firms that emphasize organic certifications and botanical provenance. Each archetype is pursuing different growth routes: portfolio extensions, limited-edition launches to rejuvenate heritage brands, digital-first direct-to-consumer strategies, and partnerships with integrative-health providers. Recent notable developments — from limited-edition heritage product launches to real-world studies exploring physician-prescribed bitters — underscore the category’s dual identity as both a craft beverage ingredient and a functional botanical remedy.
Supply chain and ingredient risk management
-
Botanical concentration risk: Leading formulations rely on a defined set of bittering agents. For example, certain legacy recipes synthesize inputs from multiregional herb sources, demanding comprehensive inspection regimes. Procurement strategies that diversify supplier bases and build forward inventory against seasonal variability will be essential in 2026.
-
GMP and traceability investments: High-value buyers increasingly demand GMP-aligned manufacturing and detailed batch traceability. Firms that certify upstream suppliers and embed traceability technologies (e.g., QR-enabled provenance tracking) will unlock premium channel access.
Innovation, product development and differentiation
-
Claim architecture: Moving from general digestive support to targeted claims (e.g., postprandial relief, bloating modulation, liver-support adjuncts) requires an evidence strategy. In 2026, pairing mechanistic preclinical data with small pragmatic clinical or real-world studies will be a cost-effective route to claim differentiation.
-
Format innovation: Expect a pipeline of new delivery formats that balance efficacy, convenience, and sensory experience — tinctures optimized for mixability, micro-dosed sprays, and single-serve powder sachets designed for travel and foodservice.
-
Flavor and culinary collaborations: Co-branding with cocktail bars, culinary influencers, and recipe platforms can accelerate mainstream acceptance while preserving performance positioning.
M&A, partnerships and commercialization playbook for 2026
-
Acquisition targets: Strategic acquirers should target firms with strong digital customer acquisition economics, differentiated formulations with IP or certification, and validated supplier relationships. Bolt-on acquisitions can rapidly broaden channel access — particularly into specialty health retailers and online subscription ecosystems.
-
Partnerships: Collaborations with integrative-care clinics and compounding pharmacies in markets with established magistral practice can open prescriber channels and validate higher-order health claims. Early partnerships should focus on real-world evidence capture rather than large-scale RCTs to control cost and accelerate learning.
-
Go-to-market: A hybrid model that layers premium omnichannel placement with targeted digital community building is optimal. Invest in education-based content and practitioner engagement to accelerate trial among higher-LTV consumers.
What’s in the full PW Consulting report (practical, operational deliverables)
-
A detailed market-sizing framework (historical analysis and transparent forecasting methodology covering 2020–2025 base and 2026–2032 forecasts).
-
Channel and format playbooks, with retailer-level negotiation tactics and suggested margin modeling for 2026 product launches.
-
Competitive profiles and benchmarking of leading heritage and natural-health brands, including recent product initiatives, supply-chain footprints, and go-to-market case studies.
-
Regulatory and evidence-building pathways mapped to key markets, with cost-and-timeline estimates for claim substantiation and GMP transitions.
-
Scenario planning and sensitivity analysis illustrating how raw material volatility, regulatory shifts, and channel disruption could alter revenue trajectories.
-
Actionable M&A screening criteria and a prioritized target list aligned to acquisition, partnership, or distribution strategies.
Concrete next steps for executives (2026 roadmap)
-
Prioritize supply security: conduct an immediate supplier stress-test and build dual-sourcing for critical botanicals.
-
Define an evidence plan: map claims to incremental data needs and begin low-cost real-world studies in partnership with integrative-care providers.
-
Test omnichannel pilots: deploy subscription + DTC bundles and specialty retail assortments in two geographies to validate price elasticity and acquisition costs.
-
Evaluate bolt-on acquisition targets that bring digital scale or certified-organic credentials.
-
Invest in traceability tech and packaging storytelling to convert sustainability and provenance into premiumization.
Conclusion — opportunity framed, but not unlocked
The digestive bitters category offers a compelling balance of heritage credibility and modern wellness upside. With global revenues growing steadily and a moderate CAGR through 2032, the commercial horizon is attractive — but the path to market leadership in 2026 requires disciplined choices on sourcing, evidence generation, and channel execution. PW Consulting’s full Worldwide Digestive Bitters Market report provides the granular segmentation, retailer-level margin models, and company-level data necessary to convert this strategic preview into executable plans. For readers seeking the specific segmentation insights and the proprietary competitive scorecards referenced here, please consult the full report to access the actionable data reserved for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Worldwide Digestive Bitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automatic Noise Monitoring Market to Rise from USD 875.8 Million in 2025 to USD 1,551.2 Million by 2032 on an 8.51% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide Automatic Noise Monitoring System Market — Strategic Outlook for 2026 Decision-Makers
As cities, airports, construction sites and industrial operators move from periodic auditing to continuous environmental stewardship, automatic noise monitoring systems are becoming a procurement and policy priority. PW Consulting’s latest market study — anchored in a 2025 base year and projecting through 2032 — places the sector on a sustained growth trajectory (CAGR 8.51% across the forecast window). The global market has expanded markedly since 2020 and is forecast to roughly double by the end of the forecast horizon, underscoring why decisions made in 2026 will determine competitive positioning and compliance readiness for the remainder of the decade.
Worldwide Automatic Noise Monitoring System Market
Why 2026 is a strategic inflection point
- Regulatory acceleration. National and supra‑national bodies are increasingly mandating real‑time, automatic monitoring for infrastructure projects and urban noise management. Compliance is no longer a periodic checkbox but a continuous operational requirement; IEC 61672‑1 performance criteria and the ISO 1996 series are now baseline expectations, and features such as remote calibration verification (e.g., Charge Injection Calibration) are rapidly moving from “nice to have” to contractual must‑haves.
- Technology enablers mature. Battery‑optimized wireless units, cloud platforms with real‑time alarms, directionality and multi‑sensor integration (noise + meteorology + particulate/vibration) have lowered deployment friction and expanded use cases from airports to smart cities and infrastructure monitoring.
- Stakeholder expectations shift. Community engagement, reputational risk management and ESG reporting push owners to adopt continuous monitoring to demonstrate transparency, resolve complaints faster and feed data into digital twins and asset management systems.
What PW Consulting’s report delivers — practical outputs for 2026 action plans
The study is designed as an operational playbook for buyers, vendors, integrators and investors. Highlights include:
Worldwide Automatic Noise Monitoring System Market
- Market sizing and scenario modelling that translates macro growth into procurement demand curves over 2026–2032 (base year 2025).
- Vendor benchmarking and capability matrices that map hardware (Class 1 performance, battery life, ingress protection), software (cloud analytics, APIs, alerting), service models (installation, calibration, maintenance) and go‑to‑market approaches.
- Procurement tools: RFP templates, evaluation scorecards, total cost of ownership (TCO) calculators, sample SLA language and security checklists for cloud data management.
- Deployment playbooks: pilot design, siting guidelines (including standards for sensor placement and meteorological integration), calibration verification procedures and phased scale‑up plans to manage community engagement and risk.
- Strategic modules for investors and acquirers: consolidation scenarios, partnership archetypes, and integration blueprints for cross‑asset environmental monitoring (noise+air+vibration).
Market dynamics and growth drivers you must factor into 2026 decisions
The market expansion to 2025 shows a clear, sustained upward trend in demand for both permanent and portable monitoring solutions. A compound annual growth rate of 8.51% across the forecast period reflects combined drivers: regulatory tightening; infrastructure investment; the proliferation of smart‑city initiatives; and a shift toward managed service models that bundle sensors, connectivity and analytics. While the vendor landscape includes established measurement specialists and nimble systems integrators, concentration metrics indicate an industry that is neither monopolized nor atomized — a mid‑consolidation market where scale, service breadth and partnerships matter.
Worldwide Automatic Noise Monitoring System Market
- Regulation and compliance: IEC 61672‑1 and ISO 1996 become procurement filters, and many jurisdictions now require meteorological integration and documented remote calibration capabilities.
- Integrated monitoring demand: Project owners prefer multi‑parameter stations that reduce field visits and support integrated environmental reporting.
- Service economics: Buyers increasingly favour subscription or managed‑service contracts that shift capital expense and ensure lifecycle support for sensors and cloud platforms.
Competitive landscape — strategic implications for incumbents and challengers
The competitive field blends legacy instrumentation manufacturers, specialized environmental monitoring vendors and software/cloud first entrants. Key players each bring differentiated propositions:
- Brüel & Kjær (HBK) — decades of measurement expertise, robust noise monitoring terminals designed for unattended all‑weather operation, and established processes for remote calibration and sound recording. Strengths: measurement credibility, engineering depth and high‑assurance solutions for complex, high‑risk sites.
- Svantek — product innovation focused on smart‑city integration and directionality; cloud connectivity and alarming are core. Strengths: urban deployments and multi‑point topologies accelerated by recent product introductions.
- ACOEM Group (01dB) — systems integrator model combining hardware, installation and managed services for transport and large‑scale urban networks. Strengths: project delivery and lifecycle maintenance capabilities.
- Sigicom — wireless, battery‑optimized devices and a strong presence in construction site monitoring. Strengths: modularity, long field life and software for remote fleet management.
- Sonitus Systems — cloud‑centric analytics and a recent acquisition and partnership activity that broadens its environmental monitoring footprint. Strengths: SaaS analytics and rapid scaling through M&A and distribution partnerships.
- Larson Davis, Norsonic, RION, Cirrus, Casella — each offers focused strengths across portable/permanent instrumentation, compliance support and channel reach.
Recent industry moves illustrate strategic fault lines: acquisitions and partnerships (e.g., cloud analytics providers aligning with hardware vendors) accelerate platform plays, while product launches that improve battery life, connectivity and directionality expand addressable markets. For buyers, this creates vendor selection tradeoffs between measurement provenance (traditional OEMs) and speed to value (cloud‑first providers).
Technology and procurement playbook for 2026
To translate market intelligence into executable strategy, PW Consulting recommends a pragmatic, risk‑managed approach:
- Mandate Class 1 compliance and calibration verification. Specify IEC/ISO standards conformance and require CIC or equivalent remote calibration checks in procurement documents.
- Adopt hybrid deployments. Combine fixed terminals for continuous trending with portable units for site‑specific investigations and community response.
- Define data ownership and SLA terms up front. Cloud analytics vendors must meet availability, latency and security SLAs, with clear data export and retention policies to avoid vendor lock‑in.
- Model full lifecycle economics, not just capex. Include calibration, firmware upgrades, network connectivity and analytics subscriptions in TCO models to compare bundled managed services vs. raw hardware purchases.
- Pilot for six months, then scale. Use geographically and operationally representative pilots to stress test siting, false alarm rates, community response workflows and data pipelines.
- Build integration roadmaps. Ensure monitoring data can feed into existing asset management, incident management and GIS systems.
Risks, uncertainty and mitigation approaches
- Standards evolution. Changes to measurement standards or local calibration rules can impose retrofit costs; include upgrade clauses in supplier contracts.
- Supply chain and component risk. Connectivity modules and sensor capsules can face shortages; consider dual‑sourcing strategies and inventory buffers for critical projects.
- Data privacy and governance. Public‑facing noise portals and audio capture require careful privacy assessments and redaction controls.
- False positives and community trust. Ensure analytics pipelines include human‑in‑the‑loop validation and clear escalation protocols to avoid eroding confidence.
Actionable next steps for executives in 2026
For infrastructure owners, municipalities, construction firms and industrial operators preparing 2026 budgets, PW Consulting recommends a five‑point starter plan:
- Commission a short diagnostic to map regulatory obligations and current monitoring gaps against the 2026 project pipeline.
- Run a targeted pilot that validates siting, connectivity and analytics against live conditions for at least one season to capture variability.
- Issue an RFP that mandates standards conformity, remote calibration, clear data ownership and security provisions; evaluate total lifecycle pricing.
- Negotiate pilot‑to‑scale commercial terms with preferred vendors, including performance guarantees and migration paths.
- Institute a data governance and community engagement protocol that turns monitoring into a public trust instrument, not just a compliance artifact.
Conclusion — the strategic value of this report for 2026 decision cycles
PW Consulting’s Worldwide Automatic Noise Monitoring System Market report is built to be a practical decision‑support tool for 2026. It combines market sizing (anchored to a 2025 base year and projecting through 2032 with a clear growth trajectory), vendor intelligence, procurement instruments and deployment playbooks so executives can convert regulatory pressure and technological opportunity into measured, cost‑effective programs. The market structure — moderate concentration with room for consolidation and specialist plays — means timing and partner selection will determine who captures service margins and who becomes a long‑term platform supplier.
This article intentionally highlights strategic insights while reserving detailed segmented datasets, regional and application splits, vendor scorecards and downloadable procurement templates for the full report. For access to the complete dataset, segmentation breakouts, and our vendor selection matrix, visit PW Consulting’s report page and request the 2026 executive briefing pack.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Noise Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Commercial Drink Mixer Market Set to Expand at a 4.85% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Commercial Drink Mixer Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As the global hospitality and beverage-service landscape stabilizes post-pandemic, the commercial drink mixer market is entering a new phase of steady expansion and structural reconfiguration. PW Consulting’s latest market study — with a 2025 base year and a forecast horizon to 2032 — finds the market at approximately USD 1,045 Million in 2025 and projecting to more than USD 1,455 Million by 2032, representing a compound annual growth rate (CAGR) of 4.85% across the forecast period. For executives preparing budgets, M&A pipelines, and product roadmaps for 2026, the study provides decision-ready insight while deliberately withholding granular split-level figures in this summary to encourage download of the full model and datasets.
Worldwide Commerical Drink Mixer Market
Why this report matters for 2026 decision cycles
- Actionable forecasting: A robust, scenario-ready demand model calibrated to 2020–2025 trends and stress-tested across recovery, baseline, and accelerated-premium scenarios for 2026–2032.
- Commercial playbooks: Step-by-step GTM (go-to-market) templates for on-trade channels — bars, restaurants, coffee programs — and for managed procurement into multi-unit operators.
- Risk-first supply planning: Practical tools and hedging checklists that translate raw-material, tariff and regulatory risks into procurement actions and capex triggers.
- M&A and partnership scouting: A shortlisted framework to evaluate consolidation targets and artisanal alliances that accelerate premium offerings in on-trade programs.
Market dynamics shaping 2026 strategies
- Premiumisation continues to accelerate demand for specialty mixers. Cocktail program maturation across urban centers and rising bar-led consumer education are driving growth in premium tonic, botanical sodas and syrup-based mixers.
- Channel recovery is uneven but durable. On-trade volumes rebounded materially through 2023–2025 and are projected to underpin mid-single-digit market expansion through 2032, creating selective opportunities for volume and margin expansion.
- Input-cost volatility. Agricultural inputs and botanical extracts are constraining margin expansion: global raw sugar averaged roughly 22.75 cents per pound in 2024 (up ~5% from 2023), and quinine-containing inputs faced supply-led price pressure with cinchona/quinine extract costs rising in recent years. These moves compress formulations and require procurement playbooks for 2026.
- Regulatory and labeling pressure. Several jurisdictional mandates — from quinine limits in tonic formulations to EU nutritional labeling requirements — are influencing formulation choices, packaging claims, and go-to-market timing. Compliance-driven SKU rationalisation is a near-term imperative for cross-border distributors.
- Trade frictions and tariffs. Ongoing tariff measures in key markets (for example, certain carbonated mixers facing higher import duties) demand scenario planning for sourcing diversification and landed-cost optimization.
- Fragmented competitor field. Market concentration remains moderate: the top three commercial mixer suppliers account for under one-third of market value, and the top five remain below 40%. That combination of scale players plus vibrant niche brands sustains both consolidation opportunities and incubators for innovation.
Competitive landscape — strategic moves to watch
The market is populated by global beverage conglomerates and a growing cohort of artisan specialists. Our report synthesizes competitive positioning, recent tactical moves and capability gaps across the spectrum.
Worldwide Commerical Drink Mixer Market
- Global beverage majors: The largest beverage suppliers are leveraging scale to serve bulk and dispense formats for large hospitality chains, emphasizing supply reliability and integrated distribution. Expect continued focus from these players on cost-effective, high-availability SKUs, co-pack partnerships, and chain-level contracting.
- Premium and artisanal specialists: Brands focused on botanical tonics, craft ginger beers and slim-can formats are capturing premium cocktail placements in bar programs and influencer-driven menus. Several of these players have recently introduced regionally inspired flavors and smaller-format packaging tailored to on-trade cocktail servings.
- Product innovation and capacity expansion: Notable recent industry activity includes product launches and capacity investments that signal confidence in on-trade demand; examples include trade-show introductions of new Mediterranean and citrus tonics, artisanal grapefruit/elderflower can formats for bars, and facility expansions to meet botanical-mixer demand in Europe.
- What this means for incumbents and challengers: Scale players must accelerate premiumization through M&A or white-label partnerships, whereas challenger brands should prioritize distribution partnerships, hospitality-focused merchandising and protected trade-channel agreements to avoid commoditization.
Report contents — what’s inside (practical, executable)
PW Consulting’s study blends quantitative forecasting with deliverable tools for commercial teams and boards. Key inclusions are:
Worldwide Commerical Drink Mixer Market
- Top-down and bottom-up market model covering 2020–2032 with scenario variants and sensitivity controls for price, volume and channel mix.
- Price and cost build-ups including raw-material baskets, packaging differentials and incremental logistics impacts under tariff and fuel scenarios.
- Supply-chain risk heatmap and supplier-disruption playbook — supplier concentration, single-source botanical risks and seasonal supply windows are profiled with mitigation timelines.
- Regulatory compliance matrix and SKU-level labeling guide for major markets.
- Go-to-market templates for on-trade segmentation, distributor incentive structures, and value-based pricing worksheets.
- M&A screening tool and valuation primer for bolt-on acquisitions (criteria include route-to-market, asset-light production capability, brand equity and distribution foothold).
- Competitive benchmarking dossier covering product portfolios, channel strategies and recent strategic maneuvers of key players across the value chain.
Note: In keeping with our “trailer” approach, detailed regional, type and application splits — and the granular revenue-by-segment tables used in client models — are reserved for the full report and downloadable data package.
Priority strategic recommendations for 2026 (executive summary)
- Establish a raw-material hedge and supplier diversification program now. Given recent sugar and botanical price swings, lock-in conditional hedges and build dual-source pathways for quinine and key botanicals before peak-season disruptions.
- Rationalise SKUs across regulated markets. Consolidate low-rotation SKUs and accelerate reformulation of high-sugar lines to meet both consumer demand for lower-sugar options and regulatory labeling burdens.
- Invest in on-trade formats that maximize per-serving margin. Slim cans and portioned mix formats continue to improve cocktail margins for bar operators and increase placement frequency — prioritize piloting these in 2026 rollouts with top-tier accounts.
- Define a two-track growth engine: defend mass-channel contracts with optimized cost-to-serve while incubating premium, botanical-led brands for margin-rich placements. Use white-label and co-packing agreements to bridge capabilities quickly.
- Prepare a consolidation playbook. With market concentration moderate, 2026–2028 represents a window to acquire specialist brands that provide immediate route-to-premium coverage and cultural cachet within hospitality channels.
- Upgrade analytics: implement POS and hospitality consumption tracking to move from shipment-based planning to consumption-sensor inputs for better inventory turns and promotional ROI.
How boards and executive teams should use this study in 2026
- Budget & CapEx planning: Use the model to stress-test packaging investments and capacity projects under multiple demand and cost scenarios before committing capital.
- M&A and partnerships: Use the M&A screening tool to prioritize targets that accelerate premiumization or address single-source botanical risk.
- Procurement negotiations: Translate model outputs into procurement KPIs and contract clauses — indexed pricing windows, force majeure thresholds specific to botanical supply, and shelf-life-based buying windows.
- Commercial KPI setting: Rebase sales incentives and distributor margins on per-serving economics rather than case volumes in order to capture premium upside.
PW Consulting’s Worldwide Commercial Drink Mixer Market report is designed as both a strategic compass and a tactical workbench for 2026. It demonstrates where volume and margin expansion will occur, the nature of supply-side constraints, and the strategic moves that will determine winners in the coming three years.
For the full dataset, regional and application splits, downloadable financial models and proprietary competitor scorecards that informed this brief, access the full report landing page or contact PW Consulting’s beverage practice. The complete package contains the confidential appendices and worksheet tools executives need to operationalize a winning 2026 plan.
For detailed analysis of this topic, please visit the official page: Worldwide Commerical Drink Mixer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Renal Denervation Devices Market Poised to Grow at a 14.55% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Renal Denervation Devices Market — Strategic Preview for 2026 Decision‑Makers
Executive overview
PW Consulting’s latest market study on Worldwide Renal Denervation (RDN) Devices synthesizes clinical, commercial, regulatory, and financial intelligence to support board-level and operational decision-making in 2026. The RDN market has entered an accelerated deployment phase following landmark regulatory and reimbursement milestones; our base-year analysis (2025) positions the global device market at approximately USD 320.5 Million (USD Million unit), with a projected compound annual growth rate (CAGR) of 14.55% across the 2026–2032 forecast window. By 2032, the market is modelled to approach the high hundreds of millions (USD 826.9 Million), reflecting rapid adoption in mature payor environments and an expanding addressable patient population.
Worldwide Renal Denervation Devices Market
Why 2026 is a strategic inflection point
- Reimbursement clarity: Payers in major jurisdictions have moved from pilot schemes to formal coverage frameworks, creating a commercial runway for scale.
- Clinical validation and approvals: Multiple regulatory approvals and the maturation of pivotal evidence sets reduce technology and clinical adoption risk—accelerating hospital and clinician uptake.
- Competitive consolidation: High concentration among a small number of technology leaders has elevated deal activity, making 2026 a window for strategic partnerships, licensing, and selective M&A.
For executives deciding on capital allocation, clinical trial investments, or market expansion strategies this year, these three forces combine to create both opportunity and execution risk. Our report is designed to convert these macro-level signals into actionable go/no-go inputs for 2026 planning cycles.
Worldwide Renal Denervation Devices Market
Market trajectory and scenario framing
Our modelling, grounded in 2020–2025 historical performance and primary research with clinicians, payors and procurement leads, projects a sustained double-digit growth trajectory. The market’s trajectory is driven by a confluence of: broader reimbursement (notably national coverage decisions that enable evidence-development pathways), NTAP-style transitional payments that de-risk hospital economics, and commercially available devices employing differentiated energy modalities.
Worldwide Renal Denervation Devices Market
To aid decision-makers, the report contains multiple forecast scenarios (base, accelerated uptake, constrained adoption) that stress-test the market against variables such as procedure pricing, payor policy adoption speed, and long-term durability data. These scenario outputs are instrumental for financial planning, capacity investments, and pricing negotiations.
Regulatory and reimbursement dynamics shaping commercial access
Over the past three years the regulatory environment has evolved from cautious approval to structured coverage frameworks. National coverage decisions and specific coding have materially altered the revenue calculus for hospitals and device sponsors. In parallel, transitional and supplemental payment mechanisms have been introduced to offset initial hospital acquisition and procedural costs, lowering barriers to adoption.
From a market-access standpoint, the 2026 battleground will be evidence-generation under coverage regimes, especially Coverage with Evidence Development (CED)-style pathways. Manufacturers must design registries and trials that satisfy payor endpoints (hard cardiovascular outcomes, durable blood pressure reductions, and health-economic thresholds). Our report maps regulatory timelines, coding pathways, and recommended evidence strategies by major market—translating policy signals into tactical plans for submission and post-market programs.
Competitive landscape: what the leaders and challengers are doing
The RDN competitive set is characterized by a small number of well-capitalized platform incumbents alongside a cohort of specialized innovators focusing on differentiated mechanisms of action. Market concentration is high at the top: the three largest participants capture a substantial share of commercial activity, and the top five firms consolidate almost the entirety of near‑term commercial volume. This structure creates a tilt toward platform-led commercialization and selective partner opportunities for smaller entrants.
- Medtronic: Positions its Symplicity Spyral RF platform as a leadership franchise, emphasizing a broad commercial footprint and clinician training programs. Medtronic’s corporate communications frame RDN as a multi‑billion-dollar opportunity and underscore investments in post‑market evidence and hospital economics.
- Recor Medical (Otsuka Medical Devices): The Paradise uRDN ultrasound system has rapidly scaled following regulatory approvals and market recognition for therapeutic innovation. Recent awards and national reimbursement actions in select markets validate the commercial potential for ultrasound-based approaches.
- Large strategic players (e.g., Boston Scientific, Terumo): These companies remain active in adjacent hypertension device strategies and represent potential acquirers or alliance partners, particularly where portfolio adjacency or channel strength matters.
- Specialized innovators (Ablative Solutions, Mercator MedSystems, Symple Surgical): These firms pursue niche technical differentiation—micro-infusion, alcohol-based denervation, and other targeted approaches—creating pockets of clinical differentiation that buyers and partners will evaluate for licensing or acquisition.
The competitive chapter of the report uses a decision-focused framework: value‑proposition heat maps, clinical evidence matrices, partner fit analyses, and five-year positioning roadmaps that show where to compete, collaborate, or exit.
Practical contents: what the full report delivers
PW Consulting’s study was developed for executives requiring executable intelligence, not just descriptive analysis. Key deliverables include:
- A validated market-sizing model (2020–2032) with base and sensitivity scenarios, and clear assumptions for patient population, penetration rates, and procedure economics.
- Technology assessments comparing radiofrequency, ultrasound, and infusion-based modalities across efficacy durability, procedural workflow, and adoption friction.
- Reimbursement playbooks: coding, billing, and evidence requirements by major payor, including operational templates for registry design and payer negotiations.
- Hospital and clinician adoption models: total cost of ownership, revenue impact, and change-management roadmaps for interventional cardiology and hypertension programs.
- Commercial go-to-market blueprints: segmentation, launch sequencing, pricing strategies, salesforce sizing, and account-based marketing programs.
- Competitive intelligence dossiers for the leading and emerging companies, plus an M&A target short-list and valuation frameworks.
- Risk and resilience analysis for supply chain, manufacturing scale-up, and regulatory contingencies.
Each module is accompanied by executable templates—e.g., payer engagement scripts, hospital value-case slides, and a 36-month launch playbook—so teams can move from insight to deployment quickly.
Strategic recommendations for 2026 planning
Our top-line strategic counsel for decision-makers preparing 2026 plans is practical and prioritized:
- Prioritize market-access investments: Fund registries and real-world evidence programs aligned with payor endpoints. Coverage with Evidence Development environments reward credible, rapid data collection.
- Model hospital economics meticulously: Use granular cost and reimbursement scenarios to negotiate NTAP-like support or shared-risk pilots with health systems.
- Differentiate clinically and commercially: For smaller innovators, pursue either clear clinical differentiation (durability, safety) or unique commercial channels (ASC-focused workflows) before scaling a direct sales model.
- Consider partnership-first routes: Where channel or scale gaps exist, licensing, distribution, or co-commercialization with larger medtech incumbents can de-risk rollouts and accelerate payer acceptance.
- Maintain optionality for M&A: Given high market concentration and active strategic interest, maintain a shortlist of bolt-on targets and prepare diligence packages to move quickly on attractive valuations.
How PW Consulting’s report supports board and investor decisioning
The report is structured so that C-suite teams, investor committees, and commercial leaders can extract the inputs they need within an executive day. Boards receive an investment-risk dashboard and a three‑year cash-flow sensitivity model; commercial teams receive playbooks and launch trackers; clinical teams receive evidence-planning templates mapped to payor endpoints. For investors, the study highlights where capital can be deployed to compress time-to-scale and where downside risk is concentrated.
Conclusion and call to action
Renal denervation has moved from experimental therapy to an investable device market with defined commercial pathways. The convergence of regulatory approvals, reimbursement mechanisms, and platform maturation positions the sector for meaningful growth through the end of the decade. PW Consulting’s Worldwide Renal Denervation Devices Market report translates these macro trends into operational steps for 2026—allowing organizations to convert momentum into measurable commercial outcomes.
To review the full dataset, scenario outputs, company dossiers, and the operational playbooks referenced here, please visit the report landing page for secure access to the complete intelligence package. The public preview provided in this release demonstrates our analytical depth while preserving the proprietary segmentation and revenue-level tables that are available with purchase—ensuring you can execute with the confidence of full-spectrum market visibility.
For detailed analysis of this topic, please visit the official page: Worldwide Renal Denervation Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Monochlorobenzene Market Poised for 3.8% CAGR, New Report Predicts
By pmarketresearch, 2026-07-15
Worldwide Monochlorobenzene Market — 2026 Outlook: Strategic Imperatives for Decision-Makers
Executive summary
PW Consulting’s latest market study on Worldwide Monochlorobenzene (MCB) provides a focused, decision-ready view for executives planning through 2026 and beyond. Built on a historical base covering 2020–2025 (base year 2025) and a forward-looking forecast window spanning 2026–2032, our model projects the global MCB market to grow at a compound annual growth rate (CAGR) of 3.8% (USD, revenue unit: Million). The market expanded from an estimated USD 881.35 Million in 2023 to USD 950.0 Million in 2025, and our mid-case projection reaches approximately USD 1,233.4 Million by 2032. These topline dynamics reflect steady demand in chemical intermediates, continued substitution in certain end-use streams, and ongoing feedstock- and regulatory-driven cost pressure.
Worldwide Monochlorobenzene Market
Why this report matters in 2026 — the strategic value
- Investment and capacity timing: With moderate, predictable growth at a 3.8% CAGR, capital deployment decisions should prioritize flexible, scalable assets that can respond to feedstock swings and premium-grade demand.
- Procurement and margin protection: Feedstock price volatility (see price signals below) is the most immediate margin lever for producers and converters; procurement strategies and hedging structures implemented in 2026 will materially affect full-year profitability.
- Regulatory preparedness: Recent regulatory moves require proactive product stewardship and labeling updates — companies that integrate compliance into product roadmaps will avoid downstream disruption and create differentiation for higher-purity offerings.
- M&A and partnership prioritization: Market concentration (CR3 ~45%, CR5 ~62%) suggests room for bolt-on consolidation and value-creating partnerships that balance regional supply imbalances and technical product capabilities.
- Commercial positioning: Buyers in agrochemicals, specialty chemicals and industrial applications are increasingly selective on impurity profiles and supply reliability — positioning around grade, traceability and sustainability will command premium contracts.
Key market signals to watch in 1H–2H 2026
- Topline trajectory: The market advanced from ~USD 881.35 Million (2023) to ~USD 950.0 Million (2025), and is projected at ~USD 986.1 Million in 2026 under baseline assumptions — a profile consistent with steady, non-disruptive growth into 2032.
- Feedstock pricing: Benzene, the primary upstream feedstock for MCB production, continues to exhibit regional variation; for context, Northeast Asia benzene prices were reported around USD 0.94/kg in March 2026. Chlorobenzene family pricing has shown notable upward moves in early 2026: reports indicate April 2026 chlorobenzene prices near USD 1.23/kg in Northeast Asia (up ~10.8%), USD 1.48/kg in Europe (up ~8.0%), and USD 1.19/kg in India (up ~14.4%). These moves materially influence short-term margins and prompt tactical inventory management.
- Regulatory developments: The US EPA finalized amendments to National Volatile Organic Compound Emission Standards for Aerosol Coatings in January 2025, updating reactivity factors (monochlorobenzene CAS 108-90-7: reactivity factor 0.36). Additionally, pre-publication notices in December 2024 signaled closer TSCA scrutiny of certain solvents and industrial cleaning uses. Expect buyers and producers to re-evaluate solvent specifications and risk provisions in contracts.
What’s in the PW Consulting report — practical, executable deliverables
Our study is designed for commercial, procurement and executive teams who need to convert market intelligence into action plans. The report includes:
Worldwide Monochlorobenzene Market
- Scenario-based demand forecasts (base, upside, downside) for 2026–2032 with sensitivity to feedstock cost, regulatory constraints and substitution trends.
- Financial and pricing model in USD (revenue unit: Million) that allows users to run bespoke scenarios, including margin levers and capex timing.
- Raw-material price shock analysis and procurement playbooks — practical hedging and inventory strategies keyed to benzene and chlorination utility exposure.
- Regulatory tracker with impact assessment and compliance roadmaps for North American and global jurisdictions.
- Supplier and competitor benchmarking matrices, production-configuration archetypes, and a prioritized list of strategic trade actions for 2026.
- Go-to-market options for premium grades and high-purity MCB targeting specialty applications.
Note: this release is intentionally calibrated to demonstrate depth while withholding proprietary segment-level tables and granular region/application splits — these are available in the full report package.
Worldwide Monochlorobenzene Market
Competitive landscape — who matters and why (actionable takes)
Market concentration sits in a mid-range band (CR3 ≈ 45%, CR5 ≈ 62%), indicating that scale matters but regional players and specialty producers retain meaningful influence. The competitive set features a mix of large integrated chemical players, regional producers with export footprint, and specialty manufacturers focused on high-purity grades.
- Aarti Industries Limited (India) — Major Indian producer with deep downstream integration into dyes, pigments and agrochemical intermediates. Strategic implication: strong domestic demand capture and export-oriented growth; attractive partner for feedstock-secured expansions. ( https://www.aarti-industries.com)
- ChemieOrganic Chemicals India Pvt. Ltd. (India) — Focused chlorobenzene manufacturer serving industrial derivatives. Strategic implication: agility in serving reagent and industrial-grade segments with competitive cost structures. ( https://chemieorganic.com)
- LANXESS AG (Germany) — Global specialty chemicals player producing high-purity chlorobenzenes for biocides and specialty compounds. Strategic implication: premiumization trend favors players with high-purity credentials and regulatory compliance capabilities. ( https://lanxess.com)
- China Petroleum & Chemical Corporation (Sinopec) and major Chinese producers — Large state-owned and regional producers underpin global midstream supply; strategic implications include export-led competitiveness and potential for rapid volume shifts driven by domestic demand and policy.
- Kureha Corporation (Japan), PPG Industries (USA), Muby Chemicals (India) and other specialty players — These firms offer differentiated product grades and geographic reach; they represent logical targets for offtake deals, technical partnerships or bolt-on acquisitions depending on strategic intent.
For buyers and investors, the practical takeaway is clear: pursue a mix of scale and technical differentiation. Scale provides cost leadership; technical capability and regulatory compliance enable margin capture in premium downstream niches.
Market dynamics, risks and upside levers
- Input cost volatility: Benzene and nascent chlorobenzene price moves are the dominant short-term risk. Companies should deploy dynamic hedging and flexible contract terms to avoid margin compression during price spikes.
- Regulatory tightening: Emissions and solvent use regulations necessitate early investment in emissions controls, documentation systems and product stewardship to avoid penalty-driven disruption.
- Substitution and technology: Some end-use sectors are exploring solvent substitution and greener chemistries; this presents both risk to commodity streams and opportunity for high-purity, low-emission differentiated products.
- Supply chain concentration: Geographic imbalances in production capacity create latency in supply-response — near-term supply squeezes can be mitigated via strategic inventory and diversified sourcing arrangements.
Priority actions for executives in 2026
- Short-term (next 6–12 months): Implement tactical procurement hedges, renegotiate contracts with pass-through clauses, and run a one-off cost-to-serve analysis focused on high-volume customers.
- Medium-term (12–24 months): Invest in emissions control and quality assurance to capture premium pricing for specialty and pharmaceutical-adjacent grades; secure feedstock supply via long-term agreements or captive feed strategies.
- Strategic (24+ months): Evaluate bolt-on acquisitions in regions where scale is lacking or technical capability is needed; prioritize assets that enable grade diversification and regulatory-compliant production.
- Commercial: Redesign go-to-market terms to reflect regulatory compliance value-add, and create tiered product portfolios with corresponding logistics and contractual terms.
Accessing the full intelligence
This brief is a curated preview intended to support 2026 decision-making and to point executives to the levers that matter. The full PW Consulting Worldwide Monochlorobenzene Market report includes the complete set of proprietary segmentation tables, country- and application-level forecasts, downloadable Excel models, supplier scorecards, and an actionable regulatory playbook. For access to the full report and bespoke consulting engagements tailored to your portfolio, please visit our report page or contact PW Consulting directly.
For detailed analysis of this topic, please visit the official page: Worldwide Monochlorobenzene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Digital Scent Market Poised for 11.64% CAGR, Accelerating Global Adoption Through 2032
By pmarketresearch, 2026-07-15
Worldwide Digital Scent Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
As enterprises evaluate emerging sensory technologies to differentiate products, optimize operations, and create new customer experiences, digital olfaction is moving from niche experimentation toward meaningful commercialization. PW Consulting’s latest market research — the Worldwide Digital Scent Market report — provides the essential strategic intelligence leaders need to make high-confidence decisions in 2026. The market reached roughly USD 1.44 billion in 2025 and is expected to surpass USD 1.65 billion in 2026, with a projected trajectory to exceed USD 3.1 billion by 2032. Between 2026 and 2032 the market’s compound annual growth rate is modeled at 11.64%, signaling sustained, multi-year opportunity across industry verticals.
Worldwide Digital Scent Market
Why 2026 is a Turning Point
-
Technology maturation: Sensor fidelity, miniaturization, and cloud-native analytics have converged. New generations of e-noses and scent synthesizers are offering repeatable, programmable olfactory outputs and machine-readable odor signatures that make industrial integration materially easier than five years ago.
Worldwide Digital Scent Market -
Commercial proofs and product launches: Over the past 18 months the industry has moved beyond lab demos to pilots and commercial products targeting VR/AR immersion, workplace wellness, retail atmospherics, and automated quality control. These deployments expose the operational constraints and integration patterns that now inform repeatable go-to-market playbooks.
Worldwide Digital Scent Market -
Capital and IP momentum: Venture and strategic capital flows, alongside a surge in AI-enabled fragrance R&D, are accelerating ingredient discovery and scent design capabilities. The rapid proliferation of related patents and corporate filings is broadening competitive moats for firms that can couple olfaction data with proprietary models.
-
Policy and standardization awakening: Industry governance bodies and standardization initiatives are drawing clear lines around ethics, data formats, and interoperability — a necessary precondition for scaling olfactory systems in safety- and privacy-sensitive contexts.
What the Report Delivers — Practical, Decision-Ready Content
This report is designed as an operator’s manual for executives, product leads, investors, and public-sector planners who must translate olfaction hype into measurable outcomes. Key, actionable deliverables include:
-
A validated market model and demand forecast spanning 2020–2032, with scenario-based sensitivities tuned to adoption levers such as standards rollout, regulatory friction, and consumer acceptance curves.
-
End-to-end value-chain maps and use-case economics for priority verticals — healthcare diagnostics, food quality control, entertainment & gaming, retail & marketing, and environmental monitoring — including payback templates and deployment cost drivers.
-
Vendor assessment framework and scorecard: comparative analysis of sensor vendors, platform providers, and integrators across technical maturity, data strategy, IP position, go-to-market reach, and partnership fit.
-
Procurement and pilot-to-scale playbook: test protocols, data-hygiene requirements, integration checklists for hardware/software interactions, and KPIs to de-risk PoCs and accelerate scaling.
-
Regulatory & standards playbook: a matrix of compliance risks, standardization milestones, and stakeholder engagement strategies — including recommended positions for corporate policy teams and public affairs.
-
M&A and investment thesis: target archetypes, valuation sensitivities in platform versus component bets, and a prioritized list of partnership and acquisition levers to gain rapid capability or market access.
-
IP landscape snapshot and freedom-to-operate guidance for R&D leaders planning scent synthesis, digital representation, and olfactory data products.
Competitive Landscape — Who Matters and Why
The market exhibits a hybrid structure: specialist hardware pioneers coexist with software/platform innovators and scent-delivery incumbents. Our concentration analysis shows a moderate aggregation at the top (the three largest firms account for roughly one-third of identifiable market revenue, while the five-largest account for just over half), indicating both established leadership and meaningful room for consolidation and niche specialization.
-
Sensor and e-nose specialists: Companies that have commercialized robust odor-capture hardware and industry-grade analytics are best positioned for regulated and industrial use cases where repeatability matters. These firms excel in calibration protocols, sensor arrays, and cross-environment robustness.
-
Digital olfaction platforms and AI-first players: Organizations that combine chemoinformatics, machine learning, and generative models are creating two-sided advantages — they unlock new scent ingredients and expedite digital scent design while capturing valuable behavioral and perceptual datasets.
-
Scent delivery and integration players: The companies specializing in controlled release, wearable olfactory interfaces, and HVAC-integrated diffusers are the execution partners for consumer and B2B experiential applications. Their strengths are mechanical reliability, safety engineering, and content distribution.
-
Immersive experience integrators: Startups focused on VR/AR olfactory peripherals and fragrance-on-demand wearables are leading the charge in entertainment, training simulators, and therapeutic applications where synchronized multisensor stimuli matter.
For decision-makers, the implication is binary: if your priority is regulatory-grade sensing and process automation, align with established hardware-first vendors and insist on third-party validation; if your objective is rapid user experience innovation, prioritize platform providers with strong data capabilities and content libraries. True strategic advantage accrues to firms that can orchestrate both hardware fidelity and software network effects.
Regulation, Standards, and Ethical Risk
Regulatory and standards work will be a dominant theme in 2026. Industry bodies are moving from ad-hoc guidance to formalized strategies that address data formats, ethical use, safety, and societal impact. Key dynamics to monitor:
-
Standardization of olfactory metadata and exchange protocols to enable interoperability between capture devices and scent displays.
-
Ethics and governance frameworks to prevent misuse — for example, covert sensing in public spaces and privacy concerns related to physiological and behavioral inference from smell data.
-
Regulatory conversations around robotic olfaction, particularly where scent detection intersects with surveillance, safety, or healthcare diagnostics.
Companies that proactively participate in standards-setting and demonstrate transparent governance will enjoy faster procurement cycles and less regulatory friction; laggards risk costly retrofits and restricted market access.
Strategic Playbook for 2026
-
Adopt a use-case-first posture. Prioritize three high-value pilots with measurable KPIs (e.g., reduction in false rejects in quality control, increased dwell time and conversion lift in retail, or improved diagnostic sensitivity in clinical workflows) before committing to large-scale deployments.
-
Clarify the architecture choice: component integration versus platform subscription. Component buys reduce vendor lock-in but increase integration costs; platform agreements accelerate time-to-value but require stronger due diligence on data portability.
-
Invest in data governance. Olfactory datasets are sensitive and heterogeneous. Establish labeling standards, model validation routines, and procedures to prevent bias or adverse inferences.
-
Engage in standards and regulatory channels. Public participation will shape norms and create first-mover advantages for compliant solutions.
-
Prepare an M&A playbook. Identify target archetypes — IP-rich sensor innovators, content-rich scent libraries, or integration-minded system houses — and set valuation guardrails tied to revenue synergies and cost-of-integration assumptions.
Conclusion — Why Read the Full Report
The Worldwide Digital Scent Market report is intentionally prescriptive. It pairs quantitative forecasts with qualitative roadmaps and executable playbooks to help executives convert sensory technology potential into defensible business value in 2026 and beyond. Our analysis highlights the pace of commercial adoption, the structural implications of platform economics, the immediate compliance and standards workstreams that will define permissible use, and the competitive archetypes that matter for partnership or acquisition strategy.
PW Consulting’s release is written to be both an orientation guide and an operations manual: sufficient to inform board-level investment decisions, and tactical enough to steer product managers and procurement teams during pilot selection, vendor negotiation, and scale-up. For full access to the dataset, segmented forecasts, vendor scorecards, and step-by-step deployment templates, please consult the full report and our downloadable toolkits.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Scent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com