

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Digestive Bitters Market to Reach USD 2,390 Million by 2032, Growing at a 5.48% CAGR (2026–2032)

Worldwide Digestive Bitters Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest Worldwide Digestive Bitters Market study provides a clear line of sight into a category undergoing steady, consumption-driven expansion and strategic repositioning. The global market — valued at approximately USD 1.65 billion in our base year (2025) — is projected to expand at a compound annual growth rate (CAGR) of 5.48% over the 2026–2032 forecast window, reaching roughly USD 2.39 billion by 2032. For executives planning portfolios, channel strategies, or M&A activity in 2026, this report is designed to convert broad market momentum into concrete, defensible choices — while conserving proprietary segmentation metrics to preserve competitive advantage.
Worldwide Digestive Bitters Market
Why this market matters for 2026 planning
-
Consumer wellness trends continue to push bitters beyond cocktail culture into everyday digestive and functional health routines. This transition creates adjacent opportunities across formulation, claims architecture, and retailer assortment strategies.
Worldwide Digestive Bitters Market -
Supply-chain dynamics for botanical inputs and the regulatory overlay in key markets are evolving rapidly; companies that align sourcing, quality assurance, and compliance in 2026 will build durable moats.
Worldwide Digestive Bitters Market -
The category remains commercially accessible: brand heritage and craft authenticity can coexist with modernized, evidence-informed positioning. This makes bitters an attractive target for both FMCG and natural-health investors.
Key market dynamics and growth levers
-
Demand synergy across occasions: While bitters retain a heritage role in beverage and cocktail innovation, incremental growth is driven by daily digestive-use propositions — formulations positioned for bloating, indigestion, and liver-support routines. Expect cross-category marketing to accelerate adoption among mainstream wellness consumers.
-
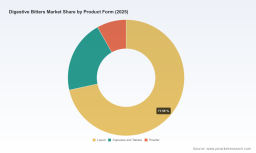
Formulation portability: Liquid bitters continue to dominate shelf space due to ease of dosing and culinary versatility, but tablets, capsules, and powdered concentrates are gaining traction among consumers seeking convenience and travel-friendly formats.
-
Retail and omnichannel evolution: Specialty retailers and online channels are the innovation frontiers — they enable storytelling and trial at lower direct-to-consumer acquisition costs. Hypermarkets retain broad reach, but 2026 should be viewed as a year to invest selectively in digital conversion and subscription models.
-
Ingredient provenance and traceability: High-profile brands emphasize rigorous sourcing standards for bittering botanicals (gentian, dandelion, artichoke, burdock, orange peel, etc.). Supply transparency is quickly becoming a baseline expectation rather than a premium differentiator.
Regulatory and clinical context — navigating complexity
-
Real-world evidence is entering the conversation: A Swiss real-world prescription database study (published early 2026) demonstrates that herbal bitters are present in integrative care pathways — either as registered medicinal products or as magistral preparations manufactured under GMP. For companies seeking to move from supplement to prescribable product, this study both legitimizes the pathway and highlights the regulatory complexity.
-
Labeling and claims constraints: In jurisdictions such as the United States, digestive bitters sold as supplements must adhere to regulatory disclaimers and will face scrutiny over therapeutic claims. In 2026, firms that invest in robust clinical or real-world evidence strategies will have a differential advantage when negotiating retailer listings or pursuing cross-border expansion.
Competitive landscape — heritage brands vs. modern naturals
The market architecture blends long-established spirit-affiliated names with newer organic and herbal specialists. This juxtaposition creates predictable playbooks for incumbents and challengers alike.
-
Heritage incumbents — Brands with multi-decade legacies bring authenticity, global distribution relationships, and recipe IP. Their strengths lie in brand equity and cocktail-culture relevance; their challenge is modernizing positioning to capture everyday digestive use-cases without diluting heritage appeal.
-
Natural and organic specialists — Smaller players built on certified-organic botanicals and clinical-adjacent storytelling are winning consumer trust in the wellness channel. Their agility in product innovation and transparency over sourcing enables premium pricing, but scale and distribution breadth remain constraints.
Representative players analyzed in our report include long-standing producers with historic formulations, and wellness-forward firms that emphasize organic certifications and botanical provenance. Each archetype is pursuing different growth routes: portfolio extensions, limited-edition launches to rejuvenate heritage brands, digital-first direct-to-consumer strategies, and partnerships with integrative-health providers. Recent notable developments — from limited-edition heritage product launches to real-world studies exploring physician-prescribed bitters — underscore the category’s dual identity as both a craft beverage ingredient and a functional botanical remedy.
Supply chain and ingredient risk management
-
Botanical concentration risk: Leading formulations rely on a defined set of bittering agents. For example, certain legacy recipes synthesize inputs from multiregional herb sources, demanding comprehensive inspection regimes. Procurement strategies that diversify supplier bases and build forward inventory against seasonal variability will be essential in 2026.
-
GMP and traceability investments: High-value buyers increasingly demand GMP-aligned manufacturing and detailed batch traceability. Firms that certify upstream suppliers and embed traceability technologies (e.g., QR-enabled provenance tracking) will unlock premium channel access.
Innovation, product development and differentiation
-
Claim architecture: Moving from general digestive support to targeted claims (e.g., postprandial relief, bloating modulation, liver-support adjuncts) requires an evidence strategy. In 2026, pairing mechanistic preclinical data with small pragmatic clinical or real-world studies will be a cost-effective route to claim differentiation.
-
Format innovation: Expect a pipeline of new delivery formats that balance efficacy, convenience, and sensory experience — tinctures optimized for mixability, micro-dosed sprays, and single-serve powder sachets designed for travel and foodservice.
-
Flavor and culinary collaborations: Co-branding with cocktail bars, culinary influencers, and recipe platforms can accelerate mainstream acceptance while preserving performance positioning.
M&A, partnerships and commercialization playbook for 2026
-
Acquisition targets: Strategic acquirers should target firms with strong digital customer acquisition economics, differentiated formulations with IP or certification, and validated supplier relationships. Bolt-on acquisitions can rapidly broaden channel access — particularly into specialty health retailers and online subscription ecosystems.
-
Partnerships: Collaborations with integrative-care clinics and compounding pharmacies in markets with established magistral practice can open prescriber channels and validate higher-order health claims. Early partnerships should focus on real-world evidence capture rather than large-scale RCTs to control cost and accelerate learning.
-
Go-to-market: A hybrid model that layers premium omnichannel placement with targeted digital community building is optimal. Invest in education-based content and practitioner engagement to accelerate trial among higher-LTV consumers.
What’s in the full PW Consulting report (practical, operational deliverables)
-
A detailed market-sizing framework (historical analysis and transparent forecasting methodology covering 2020–2025 base and 2026–2032 forecasts).
-
Channel and format playbooks, with retailer-level negotiation tactics and suggested margin modeling for 2026 product launches.
-
Competitive profiles and benchmarking of leading heritage and natural-health brands, including recent product initiatives, supply-chain footprints, and go-to-market case studies.
-
Regulatory and evidence-building pathways mapped to key markets, with cost-and-timeline estimates for claim substantiation and GMP transitions.
-
Scenario planning and sensitivity analysis illustrating how raw material volatility, regulatory shifts, and channel disruption could alter revenue trajectories.
-
Actionable M&A screening criteria and a prioritized target list aligned to acquisition, partnership, or distribution strategies.
Concrete next steps for executives (2026 roadmap)
-
Prioritize supply security: conduct an immediate supplier stress-test and build dual-sourcing for critical botanicals.
-
Define an evidence plan: map claims to incremental data needs and begin low-cost real-world studies in partnership with integrative-care providers.
-
Test omnichannel pilots: deploy subscription + DTC bundles and specialty retail assortments in two geographies to validate price elasticity and acquisition costs.
-
Evaluate bolt-on acquisition targets that bring digital scale or certified-organic credentials.
-
Invest in traceability tech and packaging storytelling to convert sustainability and provenance into premiumization.
Conclusion — opportunity framed, but not unlocked
The digestive bitters category offers a compelling balance of heritage credibility and modern wellness upside. With global revenues growing steadily and a moderate CAGR through 2032, the commercial horizon is attractive — but the path to market leadership in 2026 requires disciplined choices on sourcing, evidence generation, and channel execution. PW Consulting’s full Worldwide Digestive Bitters Market report provides the granular segmentation, retailer-level margin models, and company-level data necessary to convert this strategic preview into executable plans. For readers seeking the specific segmentation insights and the proprietary competitive scorecards referenced here, please consult the full report to access the actionable data reserved for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Worldwide Digestive Bitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com