

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automatic Noise Monitoring Market to Rise from USD 875.8 Million in 2025 to USD 1,551.2 Million by 2032 on an 8.51% CAGR (2026–2032)

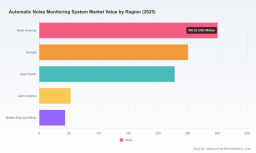
Worldwide Automatic Noise Monitoring System Market — Strategic Outlook for 2026 Decision-Makers
As cities, airports, construction sites and industrial operators move from periodic auditing to continuous environmental stewardship, automatic noise monitoring systems are becoming a procurement and policy priority. PW Consulting’s latest market study — anchored in a 2025 base year and projecting through 2032 — places the sector on a sustained growth trajectory (CAGR 8.51% across the forecast window). The global market has expanded markedly since 2020 and is forecast to roughly double by the end of the forecast horizon, underscoring why decisions made in 2026 will determine competitive positioning and compliance readiness for the remainder of the decade.
Worldwide Automatic Noise Monitoring System Market
Why 2026 is a strategic inflection point
- Regulatory acceleration. National and supra‑national bodies are increasingly mandating real‑time, automatic monitoring for infrastructure projects and urban noise management. Compliance is no longer a periodic checkbox but a continuous operational requirement; IEC 61672‑1 performance criteria and the ISO 1996 series are now baseline expectations, and features such as remote calibration verification (e.g., Charge Injection Calibration) are rapidly moving from “nice to have” to contractual must‑haves.
- Technology enablers mature. Battery‑optimized wireless units, cloud platforms with real‑time alarms, directionality and multi‑sensor integration (noise + meteorology + particulate/vibration) have lowered deployment friction and expanded use cases from airports to smart cities and infrastructure monitoring.
- Stakeholder expectations shift. Community engagement, reputational risk management and ESG reporting push owners to adopt continuous monitoring to demonstrate transparency, resolve complaints faster and feed data into digital twins and asset management systems.
What PW Consulting’s report delivers — practical outputs for 2026 action plans
The study is designed as an operational playbook for buyers, vendors, integrators and investors. Highlights include:
Worldwide Automatic Noise Monitoring System Market
- Market sizing and scenario modelling that translates macro growth into procurement demand curves over 2026–2032 (base year 2025).
- Vendor benchmarking and capability matrices that map hardware (Class 1 performance, battery life, ingress protection), software (cloud analytics, APIs, alerting), service models (installation, calibration, maintenance) and go‑to‑market approaches.
- Procurement tools: RFP templates, evaluation scorecards, total cost of ownership (TCO) calculators, sample SLA language and security checklists for cloud data management.
- Deployment playbooks: pilot design, siting guidelines (including standards for sensor placement and meteorological integration), calibration verification procedures and phased scale‑up plans to manage community engagement and risk.
- Strategic modules for investors and acquirers: consolidation scenarios, partnership archetypes, and integration blueprints for cross‑asset environmental monitoring (noise+air+vibration).
Market dynamics and growth drivers you must factor into 2026 decisions
The market expansion to 2025 shows a clear, sustained upward trend in demand for both permanent and portable monitoring solutions. A compound annual growth rate of 8.51% across the forecast period reflects combined drivers: regulatory tightening; infrastructure investment; the proliferation of smart‑city initiatives; and a shift toward managed service models that bundle sensors, connectivity and analytics. While the vendor landscape includes established measurement specialists and nimble systems integrators, concentration metrics indicate an industry that is neither monopolized nor atomized — a mid‑consolidation market where scale, service breadth and partnerships matter.
Worldwide Automatic Noise Monitoring System Market
- Regulation and compliance: IEC 61672‑1 and ISO 1996 become procurement filters, and many jurisdictions now require meteorological integration and documented remote calibration capabilities.
- Integrated monitoring demand: Project owners prefer multi‑parameter stations that reduce field visits and support integrated environmental reporting.
- Service economics: Buyers increasingly favour subscription or managed‑service contracts that shift capital expense and ensure lifecycle support for sensors and cloud platforms.
Competitive landscape — strategic implications for incumbents and challengers
The competitive field blends legacy instrumentation manufacturers, specialized environmental monitoring vendors and software/cloud first entrants. Key players each bring differentiated propositions:
- Brüel & Kjær (HBK) — decades of measurement expertise, robust noise monitoring terminals designed for unattended all‑weather operation, and established processes for remote calibration and sound recording. Strengths: measurement credibility, engineering depth and high‑assurance solutions for complex, high‑risk sites.
- Svantek — product innovation focused on smart‑city integration and directionality; cloud connectivity and alarming are core. Strengths: urban deployments and multi‑point topologies accelerated by recent product introductions.
- ACOEM Group (01dB) — systems integrator model combining hardware, installation and managed services for transport and large‑scale urban networks. Strengths: project delivery and lifecycle maintenance capabilities.
- Sigicom — wireless, battery‑optimized devices and a strong presence in construction site monitoring. Strengths: modularity, long field life and software for remote fleet management.
- Sonitus Systems — cloud‑centric analytics and a recent acquisition and partnership activity that broadens its environmental monitoring footprint. Strengths: SaaS analytics and rapid scaling through M&A and distribution partnerships.
- Larson Davis, Norsonic, RION, Cirrus, Casella — each offers focused strengths across portable/permanent instrumentation, compliance support and channel reach.
Recent industry moves illustrate strategic fault lines: acquisitions and partnerships (e.g., cloud analytics providers aligning with hardware vendors) accelerate platform plays, while product launches that improve battery life, connectivity and directionality expand addressable markets. For buyers, this creates vendor selection tradeoffs between measurement provenance (traditional OEMs) and speed to value (cloud‑first providers).
Technology and procurement playbook for 2026
To translate market intelligence into executable strategy, PW Consulting recommends a pragmatic, risk‑managed approach:
- Mandate Class 1 compliance and calibration verification. Specify IEC/ISO standards conformance and require CIC or equivalent remote calibration checks in procurement documents.
- Adopt hybrid deployments. Combine fixed terminals for continuous trending with portable units for site‑specific investigations and community response.
- Define data ownership and SLA terms up front. Cloud analytics vendors must meet availability, latency and security SLAs, with clear data export and retention policies to avoid vendor lock‑in.
- Model full lifecycle economics, not just capex. Include calibration, firmware upgrades, network connectivity and analytics subscriptions in TCO models to compare bundled managed services vs. raw hardware purchases.
- Pilot for six months, then scale. Use geographically and operationally representative pilots to stress test siting, false alarm rates, community response workflows and data pipelines.
- Build integration roadmaps. Ensure monitoring data can feed into existing asset management, incident management and GIS systems.
Risks, uncertainty and mitigation approaches
- Standards evolution. Changes to measurement standards or local calibration rules can impose retrofit costs; include upgrade clauses in supplier contracts.
- Supply chain and component risk. Connectivity modules and sensor capsules can face shortages; consider dual‑sourcing strategies and inventory buffers for critical projects.
- Data privacy and governance. Public‑facing noise portals and audio capture require careful privacy assessments and redaction controls.
- False positives and community trust. Ensure analytics pipelines include human‑in‑the‑loop validation and clear escalation protocols to avoid eroding confidence.
Actionable next steps for executives in 2026
For infrastructure owners, municipalities, construction firms and industrial operators preparing 2026 budgets, PW Consulting recommends a five‑point starter plan:
- Commission a short diagnostic to map regulatory obligations and current monitoring gaps against the 2026 project pipeline.
- Run a targeted pilot that validates siting, connectivity and analytics against live conditions for at least one season to capture variability.
- Issue an RFP that mandates standards conformity, remote calibration, clear data ownership and security provisions; evaluate total lifecycle pricing.
- Negotiate pilot‑to‑scale commercial terms with preferred vendors, including performance guarantees and migration paths.
- Institute a data governance and community engagement protocol that turns monitoring into a public trust instrument, not just a compliance artifact.
Conclusion — the strategic value of this report for 2026 decision cycles
PW Consulting’s Worldwide Automatic Noise Monitoring System Market report is built to be a practical decision‑support tool for 2026. It combines market sizing (anchored to a 2025 base year and projecting through 2032 with a clear growth trajectory), vendor intelligence, procurement instruments and deployment playbooks so executives can convert regulatory pressure and technological opportunity into measured, cost‑effective programs. The market structure — moderate concentration with room for consolidation and specialist plays — means timing and partner selection will determine who captures service margins and who becomes a long‑term platform supplier.
This article intentionally highlights strategic insights while reserving detailed segmented datasets, regional and application splits, vendor scorecards and downloadable procurement templates for the full report. For access to the complete dataset, segmentation breakouts, and our vendor selection matrix, visit PW Consulting’s report page and request the 2026 executive briefing pack.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Noise Monitoring System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com