

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Anti‑Tank Missile System Market to Expand at 5.2% CAGR, Hitting USD 10.27 Billion by 2032

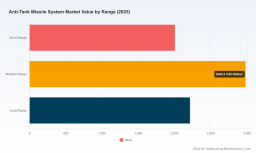
Worldwide Anti-Tank Missile System Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study provides a forward-looking, decision-focused view of the global anti-tank missile systems market. Grounded in a rigorous review of 2020–2025 performance and modeled across multiple demand and supply scenarios for 2026–2032, the report gives defense planners, program managers, investors and OEM executives the strategic context they need to prioritize investments and design procurement strategies for the coming planning cycle.
Worldwide Anti-Tank Missile System Market
Data-driven market outlook
The global anti-tank missile systems market has shown sustained growth through the early 2020s, rising from a mid-single-digit billion USD base in 2020 to a base-year total of approximately USD 7.2 billion in 2025. Our forecast, driven by platform modernization, allied replenishment programs and expanded procurement from emerging buyers, projects a compound annual growth rate (CAGR) of 5.2% across the 2026–2032 forecast window. Under the baseline scenario, the market advances to just over USD 10.2 billion by 2032, with intermediate-year dynamics reflecting both cyclical procurement awards and discrete capacity expansions announced by key suppliers.
Worldwide Anti-Tank Missile System Market
Two observations from the topline data are critical for 2026 planning:
Worldwide Anti-Tank Missile System Market
- The market’s steady historical growth demonstrates resilience to short-term geopolitical shocks, but continued expansion depends on repeatable production profiles and accessible supply chains for advanced materials and electronics.
- Concentration is high: the market is meaningfully consolidated among a small group of established tier‑one prime contractors and strategic national suppliers. This concentration creates both supply-side stability and tactical procurement risk, depending on the geopolitical alignment of buyers and producers.
Why this matters for 2026 strategic decisions
As defense budgets stabilize and modernization programs move from concept to contract, 2026 will be a pivotal year to lock in capability roadmaps and industrial partnerships. Our study translates market growth and supplier dynamics into three decision levers that will shape competitive outcomes:
- Manufacturing scale and flexibility — Organizations that secure production capacity, automation investments, and supplier commitments in 2026 will gain a two‑to‑three year advantage as demand spikes from both replacement orders and allied foreign military sales.
- Supply chain strategic sourcing — Dependence on high-temperature alloys, rare earth magnets, composites and miniature electronics creates choke points. Procurement and program managers must prioritize dual-sourcing, strategic stockpiles and qualified substitutes to avoid schedule risk.
- Integration and lifecycle economics — With systems being mounted across dismounted, vehicle and airborne platforms, decision-makers must weigh not only unit cost but integration cost, training, and sustainment. Early engagement on modular interfaces and common support equipment reduces total cost of ownership over contract horizons.
Competitive landscape — who matters and why
Our competitive assessment identifies the strategic roles of the market’s leading firms and the implications for buyers and investors. Key findings include:
- Prime western manufacturers and multinational joint ventures dominate high-end, fire-and-forget capabilities and top-attack profiles. Their scale, long-term DoD and allied contracts, and integrated supply chains underpin near-term supply reliability.
- Regional and state-owned producers are competitive on cost and localized support, and they play a critical role where offset agreements, technology transfer, or sovereign production are procurement requirements.
- Specialist subsystem players — electro-optics, guidance electronics and advanced propellants — have outsized leverage in program structuring and are frequent targets for strategic partnerships or vertical integration by primes seeking to secure supply.
Representative company profiles in the study (not exhaustive) include tier‑one primes and influential regional suppliers. For example:
- Lockheed Martin (Javelin JV) and RTX — co-production arrangements and long-term contracts underpin high-volume man-portable and heavy-tube solutions, with recent supply‑chain expansion and production contracts indicating continued demand and investment in manufacturing automation.
- Rafael and MBDA — leaders in electro-optical guided families and multi-mode engagement options; active in multi-national production and integration programs.
- Roketsan, Denel Dynamics, Saab and Bharat Dynamics — regional champions offering competitive alternatives and serving as important partners for localized procurement strategies.
- Subsystem and integrator players such as Elbit Systems, Diehl, KBP and General Dynamics — their roles range from guidance modules and warhead technologies to vehicle integration and system-of-systems enablement.
Recent program and supply signals to watch in 2026
Our report synthesizes headline events that illustrate market momentum and risk. Example developments include multi-year production awards for legacy heavy systems, supplier-led capacity expansions for high-demand man‑portable systems, and deliveries under foreign military sales and export contracts. These program flows validate demand and create near-term capacity constraints that can influence pricing, lead times and partnership choices.
Supply chain, materials and production risk analysis
The study’s segment-level risk matrix highlights a few non-obvious but high-impact vulnerabilities:
- Critical materials: rare earth elements for guidance motors and specialty alloys for propulsion and warheads concentrate sourcing risk. Small changes in availability or export policy can ripple into program schedules.
- Production scale-up: expanding missile output is not simply a matter of adding labor — long lead items, qualification cycles for suppliers and test-range capacity impose calendar risk that must be managed years in advance.
- Regulatory and political overlay: major supplier nations’ procurement policies, export controls and alliance politics materially shift options for buyers seeking diversification or local industrial participation.
Operational and procurement playbook for 2026
The report offers an operational playbook for program managers and defense investors, emphasizing practical steps to convert market insight into decisions:
- Short horizon (0–18 months): secure long‑lead components, prioritize supplier audits for critical subsystems, and negotiate flexible lot structures in new contracts to handle demand variance.
- Medium horizon (18–36 months): invest in automation and test-capacity partnerships, pursue strategic co-production or licensed manufacturing arrangements where sovereign capability is required, and incorporate sustainment cost metrics into award criteria.
- Strategic horizon (3–7 years): assess M&A or JV opportunities to obtain rare-earth processing access, expand modular architectures to enable capability upgrades without complete system replacements, and align R&D investments with anticipated countermeasures and active protection system trends.
What the report contains — practical deliverables
PW Consulting’s study is designed as an executable resource rather than a descriptive overview. Deliverables include:
- Topline historical and forecast market sizing with scenario modeling (base, accelerated demand, disruption), and sensitivity analysis tied to procurement policies and geopolitical trajectories.
- Consolidation and competitive scoring: supplier benchmarking across capability, capacity, exportability and industrial offset potential; an executable short-listing tool for sourcing decisions.
- Supply-chain heat maps and risk mitigation templates for critical materials and subsystems, with prioritized contingency options and estimated lead-time impacts.
- Procurement playbooks: sample contract language, lot-sizing strategies, and integration checklists to reduce schedule and TCO risk.
- Program-level total cost of ownership (TCO) models and scenario-based budgetary impacts for platform integrators and fleet sustainment managers.
How PW Consulting’s insight changes the calculus in 2026
For defense buyers and executives, our central conclusion is straightforward: market growth is real and steady, but value will accrue to organizations that pair access to capacity with supply‑chain resilience and integration discipline. Firms that wait for procurement peaks before securing suppliers will face higher cost and schedule risk. Conversely, buyers who use 2026 to lock in flexible production arrangements and dual‑sourcing for critical materials will preserve options and improve bargaining power.
Accessing the full analysis
This press preview outlines the strategic contours of the market and the report’s practical value. It intentionally omits granular sub‑segment allocations and detailed supplier financials that are included in the full study to preserve the analytical core for licensed readers. For procurement teams, investor committees and program offices preparing 2026 budgets and industrial strategies, the full report provides the proprietary stratagems, supplier scorecards and contract templates needed to translate forecasting into executable plans.
PW Consulting invites interested stakeholders to review the complete Worldwide Anti-Tank Missile System Market report for the in-depth data tables, segment breakdowns, supplier matrices and scenario workpapers that inform the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Tank Missile System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com