

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report Finds Worldwide Heavy Equipment Maintenance Service Market Poised for 5.34% CAGR Through 2032

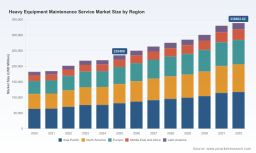
PW Consulting: Strategic Brief — Worldwide Heavy Equipment Maintenance Service Market (2026 Outlook)
Executive summary
PW Consulting today releases a strategic brief derived from our forthcoming report, Worldwide Heavy Equipment Maintenance Service Market (base year 2025, forecast 2026–2032). The global market for heavy equipment maintenance services reached an estimated USD 235.4 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.34% across the forecast window, moving toward an expected market size in excess of USD 338.8 billion by 2032. Our analysis shows a structurally fragmented services ecosystem, where the top providers capture only a limited share of total revenues — a fact that has important implications for market-entry timing, consolidation strategies and differentiated service propositions.
Worldwide Heavy Equipment Maintenance Service Market
This brief is designed as a strategic “trailer”: it distills the report’s most consequential insights for executive decision-makers in 2026 while intentionally withholding granular regional and end‑use splits to prompt direct engagement with the full report for transaction‑level planning and competitive benchmarking.
Worldwide Heavy Equipment Maintenance Service Market
Why this matters for 2026 decision-makers
- Market scale and momentum: The services market is large, liquid and growing steadily. A mid-single-digit CAGR translates into considerable absolute revenue expansion each year — enough to justify multi-year investments in network expansion, telematics and workforce upskilling for market leaders and new entrants alike.
- Fragmentation equals opportunity: Low top‑tier concentration creates runway for consolidation and for specialized service models (e.g., site-dedicated fleets, mobile overhaul units, subscription uptime contracts). Private equity and strategic acquirers can secure regional platforms at attractive multiples if they execute disciplined integration playbooks.
- Digital is table stakes — but differentiated: Telematics, predictive analytics and integrated maintenance management software are rapidly shifting the value chain from reactive repair to uptime-guaranteed service offerings. Early adopters who combine field capability with data-driven service pricing will extract higher margins and stronger customer retention.
- Labour and regulation are immediate risk levers: Rising technician wages, persistent staffing shortages and updated safety/regulatory requirements materially affect cost-to-serve models and compliance exposure for operators and service contractors.
What the PW Consulting report delivers (practical, action-ready content)
- Market sizing and validated forecasts (2020–2032), with scenario analysis across demand shock, technology adoption and regulatory outcomes.
- Service model taxonomies and cost-to-serve templates for Preventive, Corrective and Predictive services — including margin benchmarking, break-even analyses and price‑to‑value frameworks.
- Competitive intelligence dossiers for leading OEMs, independents and software vendors, with capability maps, service footprints and M&A trackers.
- Operational playbooks for scaling field service — mobile workforce planning, depot footprint optimization, parts logistics redesign and service-level agreements (SLA) that preserve uptime while protecting margins.
- Technology due diligence checklists for telematics, maintenance management platforms and predictive analytics pilots, plus integration roadmaps to realize ROI within 12–24 months.
- Regulatory and labour impact models quantifying sensitivity to wage inflation, certification regimes and documentation requirements — enabling scenario-based capital and headcount planning.
- Deal support materials: target screening frameworks, valuation comparables, integration risk matrices and a phased 100‑day plan for maintenance‑focused buy-and-build strategies.
Competitive landscape — themes and implications
The service ecosystem is shaped by a mix of multinational OEMs, global dealers, regional independents and software providers. OEM networks (led by long‑standing manufacturers) leverage dealer footprints, genuine parts supply and embedded telematics to defend installed fleets. Notable players include established OEMs with global service networks as well as specialist engine and software firms that are reshaping value capture.
Worldwide Heavy Equipment Maintenance Service Market
- Caterpillar: A leader in integrated maintenance offerings combining dealer support, parts availability and telematics-enabled predictive diagnostics. Their scale underpins broad service contracts and rebuild programs that set industry benchmarks.
- Komatsu: Strong dealer-backed preventive programs and remote equipment monitoring capabilities are core strengths. Komatsu’s model emphasizes lifecycle contracts aligned with machine uptime guarantees.
- Volvo Construction Equipment & John Deere: Each leverages telematics ecosystems to deliver uptime services and scheduled maintenance programs—a model that favors close OEM-fleet integration and recurring revenue.
- Liebherr, Hitachi, SANY and XCMG: Their global service networks and component overhaul capabilities signal an intensifying non-OEM competitive field—particularly in regional markets where local service density and parts logistics are decisive.
- DEUTZ Corporation: Recent acquisition activity underscores an aggressive push by specialist engine and powertrain suppliers to broaden full-machine maintenance capability and geographic reach — a trend we expect to accelerate.
- HCSS and Fleetio: Software vendors are pivotal enablers. Their maintenance-management platforms and telematics integrations are becoming standard interfaces between fleet operators and service providers; strategic partnerships or interoperability are now key defensive moves.
Taken together, these players illustrate two convergent dynamics: (1) OEMs and large dealers defend installed bases via integrated hardware‑software-service bundles; and (2) specialist independents and software firms exploit gaps in local coverage and software intercompatibility to capture profitable niches. The market is open to consolidation, but successful acquirers must execute tight integration on logistics, parts, and people.
Market dynamics and short-term risks to model in 2026
- Labour cost pressure: Technician wages and labour rates rose markedly in the recent period. Shops report staffing shortages and rising wage bills — a structural headwind to margins for labor‑intensive service models unless offset by productivity gains or price adjustments.
- Technician supply gap and demographic challenge: An aging workforce and below‑average inflows of younger technicians create training and retention imperatives. Upskilling, apprenticeship partnerships and retention programs should be budgeted as capital investments rather than recurring HR expenses.
- Regulatory tightening: New regulations emphasizing digital documentation, operator certification, and safety compliance increase administrative burden and compliance cost; however, they also raise barriers to entry for informal service providers, favoring well-capitalized and certified operators.
- Consolidation & M&A activity: Strategic acquisitions (including recent engine‑repair rollups) indicate growing appetite for platform plays that combine geographic reach, parts inventory and repair capability. Buyers must stress-test integration assumptions on parts obsolescence and warranty liabilities.
Strategic playbook — recommended moves for 2026
- For OEMs and large dealers: Prioritize telematics-first service bundles, establish performance-based SLAs, and pilot outcome-linked pricing (e.g., uptime guarantees). Use parts availability as a competitive moat and invest in predictive-maintenance service centers at high-density locations.
- For independents and regional service groups: Compete on responsiveness and price-to-uptime trade-offs. Invest in mobile overhaul units, standardized diagnostic toolkits and partnerships with software vendors to offer data-driven predictive services without heavy capex.
- For fleet owners and rental operators: Reassess make-vs-buy for maintenance. Consider hybrid models that combine internal preventive maintenance with outsourced corrective and overhaul services to optimize cash flow and uptime.
- For investors and acquirers: Target bolt‑on acquisitions that add parts inventory density or strategic geographies, and model labour risk explicitly. Valuation should reflect integration cost, parts synergies and service revenue stickiness post-acquisition.
How PW Consulting supports clients
PW Consulting provides end-to-end advisory services tied directly to the findings in this report: transaction due diligence; commercial and operational carve‑outs; go‑to-market and pricing strategy; telematics and predictive‑maintenance technology selection; field‑service transformation; and implementation support for M&A integration. We combine proprietary market data, on-the-ground capability audits and quant models to convert the market’s scale and trends into executable programs that preserve cash and accelerate service revenue growth.
Next steps — obtain the full report
This brief highlights strategic inflection points and practical levers for 2026, but it is only a preview. The full Worldwide Heavy Equipment Maintenance Service Market report contains the detailed regional and end‑use segmentation, vendor scorecards, modeled scenarios and downloadable data tables required for execution-level planning and transaction diligence. To access the complete analysis, including our proprietary datasets and the granular segmentation that informs investment and operating decisions, please visit the PW Consulting publications page or contact our advisory team for a tailored briefing.
PW Consulting’s senior industry analysts remain available for confidential briefings with boards, investors and executive teams to translate these findings into 90‑, 180‑ and 360‑day action plans tailored to your organization’s strategic priorities.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Equipment Maintenance Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com