

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market to Expand at a 7.15% CAGR Through 2032

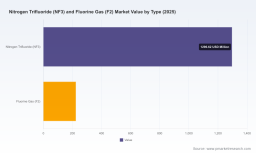
Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s new market study on Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) provides a focused, operationally minded briefing built to inform procurement, manufacturing, and corporate strategy choices in 2026. Anchored on a 2025 base year and a seven‑year forward view (2026–2032), the report synthesizes market sizing, competitive dynamics, regulatory inflection points and supply‑chain levers into a pack of executionable insights. This press release highlights the report’s strategic value while deliberately withholding core segmented datapoints to encourage readers to consult the full deliverable for granular allocations, pricing matrices and supplier scorecards.
Market Snapshot: Growth with Structural Drivers
Following a recovery phase across electronics and specialty chemicals, the NF3 and F2 market reached an inflection point in 2025. Our baseline sizing places the market at approximately USD 1.52 billion in 2025, with a robust compound annual growth rate (CAGR) of 7.15% projected across 2026–2032. Under the baseline scenario, the market is expected to approach the mid‑USD 2.4 billion range by the terminal year of the forecast.
That growth is not uniform: it is concentrated in a small number of high‑technology applications and geographies, and is supported by capex cycles in semiconductor, display, and select specialty chemical segments. The structural picture is therefore one of healthy absolute expansion alongside elevated concentration among a handful of large suppliers — an important combination for buyers and investors to understand when shaping sourcing and investment strategies for 2026.
Why 2026 Is a Pivotal Decision Year
- Capital timing: Equipment and capacity investments initiated in 2026 will come online into a market with multi‑year growth and continued technology migration in semiconductor fabrication—decisions that determine supply security through the next decade.
- Contract design: With raw‑material and logistics volatility elevated, the structure of supply agreements signed in 2026 (indexation, minimums, force majeure clauses) will materially affect TCO and continuity risk.
- Regulatory compliance: New reporting and emission rules enacted recently require operational adjustments that are best scoped and budgeted in 2026 planning cycles.
Key Market Dynamics and Risk Factors
- Concentration and bargaining dynamics: The market demonstrates significant concentration at the top. A small group of suppliers controls the majority of global production capacity, creating asymmetric negotiating leverage for suppliers and underscoring counterparty risk for large buyers.
- Raw‑material and feedstock volatility: Anhydrous hydrogen fluoride (AHF) — a critical feedstock — experienced notable price pressure in late 2024 following supply disruptions. Buyers should assume persistent feedstock cost volatility in short‑term planning and build price adjustment mechanisms into procurement contracts.
- Regulatory tightening: The European regulatory landscape has increased scrutiny on NF3 emissions and reporting obligations, effective from early 2025. This creates compliance cost and monitoring requirements for manufacturers and their suppliers, particularly in high‑emission manufacturing clusters.
- Trade and export controls: Recent expansion of export control measures has changed the flow of F2 and related technologies across some country pairs. The practical effect: buyers who previously relied on single‑country sourcing for specific grades must reassess their cross‑border strategies.
- Logistics and handling costs: F2’s hazardous classification requires specialized cryogenic transport and handling. These constraints add a meaningful uplift to landed cost and influence optimal inventory policies, especially for geographically dispersed manufacturing footprints.
Competitive Landscape — Who Matters and Why
The supplier ecosystem is composed of established industrial gas majors, regional specialty producers and niche manufacturers serving high‑purity electronics applications. The following profiles summarize the strategic positioning and recent moves of the providers that matter to global purchasers and investors.
- Solvay (Belgium) — A global producer of NF3 and advanced F2 grades, Solvay’s strengths lie in industrial scale and product development for pharmaceutical and specialty chemical fluorination. The company launched an upgraded high‑purity F2 grade in 2024, signaling a play to capture higher‑value downstream applications where specification and regulatory traceability matter.
- Air Products (USA) — A major supplier of high‑purity NF3 focused on electronics markets, Air Products has continued to expand regional capacity to meet semiconductor demand. A capacity expansion at its Hsinchu, Taiwan facility in late 2024 underscores the company’s strategy to align production footprints closely with foundry and fab clusters.
- Linde (Germany) — With legacy strengths in gas handling and global supply chains, Linde offers NF3 and F2 with a strong emphasis on operational safety and compliance (recent ISO certification updates). Linde’s network is strategically positioned to serve diversified electronics ecosystems and industrial fluorination users.
- Kanto Denka Kogyo (Japan) — Specializes in ultra‑high‑purity NF3 for LCD and semiconductor manufacturing across Asia. Its regional production hubs provide proximity advantages to major customers in the electronics supply base.
- Hyundai Steel — Green Gas (South Korea) — Supplies NF3 for flat panel display cleaning and F2 derivatives; strategic for buyers operating in the South Korean electronics and display ecosystem due to short lead times and localized technical support.
- Pelchem (Peltzer Group, South Africa) — A key regional producer with global export flows for both NF3 and F2, Pelchem serves niche markets including nuclear and specialty chemical sectors where regulatory pedigree and export documentation are paramount.
- Morita Chemical Industries (Japan) — Focused on high‑purity NF3 grades for semiconductor and solar manufacturing; notable for technical support and tailored purity specifications demanded by advanced fabs.
Together, these players shape the competitive contours of the market. Their recent actions — capacity expansions, product launches and certification efforts — are practical signals of where supply security and quality premiums will concentrate in the coming years.
What PW Consulting’s Report Delivers — Practical Content for Executives
The report is designed for executives and procurement leads who need immediate, implementable inputs for 2026 planning. Key deliverables include:
- Market sizing and a transparent forecasting model (base year 2025) that produces scenario outputs tied to macro and supply‑side shock events.
- Supplier scorecards and a counterparty risk matrix that translate concentration and operational resilience into procurement actions.
- Supply‑chain maps with lead‑time analytics, logistics cost adders for hazardous handling, and recommended inventory models by exposure type.
- Regulatory impact playbooks that align compliance timelines (e.g., recent emissions reporting changes) with CAPEX and process control investments.
- A procurement toolkit with negotiating templates, indexation clause options, and a set of KPIs to monitor contract health and supplier performance.
- Investment decision frameworks for greenfield capacity, strategic off‑takers, and joint‑venture structures tailored to the market’s concentration profile.
- Scenario planning modules that quantify the P&L and continuity impacts of feedstock price shocks, logistics constraints, and export controls.
Each deliverable combines quantitative outputs with qualitative implementation steps — for example, mapping a three‑way hedge between contract tenure, inventory buffers and alternate‑supplier qualification to preserve fab uptime while capping procurement cost exposure.
Actionable Strategic Recommendations for 2026
- Diversify with purpose: Move beyond ad‑hoc multi‑sourcing. Use tiered qualification (primary/secondary/strategic contingency) that matches supplier strengths to application criticality and regulatory risk.
- Re‑engineer contracts: Embed feedstock pass‑through mechanisms, defined escalation ceilings and operational KPIs. Preserve flexibility for re‑routing while locking minimum volumes that secure price stability.
- Invest in upstream visibility: Secure transparency on AHF supply chains and chemical intermediates; consider strategic pre‑payment or offtake to dampen price shocks.
- Operationalize compliance: Treat regulatory changes as a cost and operational contingency. Invest in monitoring and reporting tools now to avoid retrofitting plant controls under compressed timelines.
- Optimize logistics and inventory design: Given specialized transport needs, consider regional hubs and pooled inventories for multi‑site customers to reduce per‑unit logistics premiums.
- Monitor supplier concentration metrics: Track counterparty exposure against leading suppliers and establish trigger points for accelerated mitigation measures when concentration thresholds are breached.
- Consider collaborative CAPEX: For large buyers, co‑investment in regional capacity with trusted suppliers can be the most direct way to lock specification, quality and supply timelines.
How to Use This Insight in Your 2026 Planning Cycle
Procurement leaders should treat PW Consulting’s findings as inputs to three linked processes: 1) contract and inventory policy updates to be completed in Q1–Q2 2026; 2) capex and supplier engagement decisions for the 2026–2027 window; and 3) an enterprise‑level regulatory compliance roadmap aligned to regional rule changes. The report includes actionable checklists and scorecards that can be operationalized directly in supplier review meetings and board‑level investment memos.
Next Steps and Access
This release is a strategic preview intended to outline the report’s operational value. The full PW Consulting Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market report contains the underlying datasets, supplier scorecards, scenario models and segmented forecasting that underpin the recommendations above. For executives preparing budgets, contracts or investment cases in 2026, the complete dataset will be indispensable.
To obtain the full report and supporting templates, please visit the PW Consulting reports page or contact our advisory team to arrange a tailored briefing and model walk‑through. PW Consulting stands ready to convert this market intelligence into a prioritized roadmap that reduces procurement volatility, secures critical supply, and aligns investment choices to long‑term market trajectories.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com