

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Energy-Efficient Sludge Treatment Market Set to Grow at 8.85% CAGR

Worldwide Energy Efficient Sludge Treatment Market — Strategic Briefing for 2026 Decision-Makers
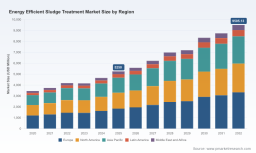
PW Consulting’s latest market study on Worldwide Energy Efficient Sludge Treatment offers a forward-looking intelligence package designed to inform capital allocation, technology selection, and partnership strategies in 2026. Built on a 2020–2025 historical base with 2025 as the reference year and a 2026–2032 forecast horizon, the report models a sector expanding at an 8.85% compound annual growth rate (CAGR). The market is projected to grow from a 2025 base of USD 5,250 Million to roughly USD 9,505 Million by 2032 — a trajectory that creates both near-term execution imperatives and multi-year strategic opportunities for utilities, technology vendors, private investors, and engineering firms.
Worldwide Energy Efficient Sludge Treatment Market
Why this matters for corporate strategy in 2026
Three dynamics converge to make 2026 a decision point for organizations exposed to sludge management costs and decarbonisation commitments:
Worldwide Energy Efficient Sludge Treatment Market
- Regulatory acceleration — regions are tightening energy and emissions mandates for wastewater operations, pushing sludge treatment from cost-control to strategic decarbonisation levers.
- Technology maturation — energy-efficient thermal and biological pathways (and their hybrid permutations) are crossing from pilots to economically material projects, changing risk profiles for deployment at utility scale.
- Commercial concentration and partnership windows — the market exhibits moderate supplier concentration, which affects procurement leverage, M&A prospects, and alliance formation.
For executive teams, the implication is clear: capital and operating decisions made in 2026 will materially shape regulatory compliance trajectories, P&L energy exposure, and optionality for resource recovery revenues over the next decade.
Worldwide Energy Efficient Sludge Treatment Market
What the report delivers — practical, transaction-focused insight
PW Consulting’s report is not an academic overview. It is structured as a decision support tool for executives and deal teams who must reconcile technical trade-offs and financials on real projects. Key operational sections include:
- Market sizing and forecasting framework — transparent assumptions, sensitivity analyses, and a range-based outlook that supports scenario planning under different policy and energy-price futures.
- Technology deep dives — comparative performance metrics, energy and mass balances, retrofit compatibility, lifecycle emission profiles, and practical limits and prerequisites for anaerobic, thermal hydrolysis, dewatering, and hybrid systems.
- Unit economics and total-cost-of-ownership models — CAPEX/OPEX templates, energy-recovery and offset modelling, and payback/IRR calculators that you can re-run with site-specific inputs.
- Procurement and deployment playbooks — technical evaluation matrices, vendor shortlisting checklists, contract and performance-risk clauses, and commissioning/acceptance protocols tailored to sludge-to-energy projects.
- Regulatory and permitting roadmap — decision timelines and compliance checklists keyed to major frameworks that influence sludge treatment strategy in Europe, the UK, and North America.
- Case studies and field validation — anonymised project dossiers showing baseline conditions, chosen interventions, measured energy performance, and lessons learned on startup and ramp-up.
- M&A, partnership and financing guide — valuation drivers, earnout structures aligned to performance guarantees, and structuring alternatives for project finance vs. corporate investment.
Each of these strands is backed by reproducible models and a set of annexes that include an adaptable Excel workbook for site-level economics, a procurement RFP template, and a regulatory-impact scoring tool for board-level briefings.
Market trajectory and macro takeaways
The energy-efficient sludge treatment market is expanding at a mid-single digit to high-single digit CAGR (8.85% in our central case) through 2032. That pace is being driven by three interlinked forces:
- Policy push — examples include recent EU directives aiming for energy neutrality of wastewater treatment plants on an accelerated timetable, and national commitments such as UK water companies’ net-zero targets that create near-term demand for measurable GHG reductions in sludge operations.
- Operational economics — aeration and biological treatment remain dominant energy consumers in wastewater systems; optimizing sludge processes presents one of the highest-leverage opportunities to reduce plant-level energy intensity.
- Technology stacking — combining digestion, thermal hydrolysis, advanced dewatering, and energy recovery systems is becoming standard for operators seeking energy autonomy or surplus energy generation.
For corporates this means the market is no longer a niche specialist domain — it is a strategic cost and value pool. By 2032, the market size inflection implies meaningful aggregated investment and growing aftermarket services demand for operations & maintenance, performance optimisation, and retrofit execution.
Competitive landscape — who to watch and why
The report’s vendor analysis maps capabilities, deployment footprints, and innovation trajectories of the leading technology and service providers. Highlights include:
- ANDRITZ AG — positioned with adiabatic sludge-treatment and mono-incineration systems that enable self-sustained combustion and district energy integration; a technology option for utilities targeting heat/electricity export without fossil-fuel supplementation.
- Alfa Laval AB — focused on mechanical dewatering and heat-recovery integration; recent strategic partnerships indicate a push toward integrated thermal conversion chains coupled with centrifuge advantages.
- Veolia & SUEZ — global integrators offering end-to-end sludge management, from digestion to biosolids processing, with the ability to combine capex projects with long-term O&M and performance contracts.
- HUBER SE, Flottweg SE, Xylem Inc. — equipment specialists enhancing dewatering efficiency and lowering unit energy consumption through incremental innovation.
- Cambi AS — thermal hydrolysis specialist that materially improves biogas yield and downstream digestion performance, often paired with energy-recovery business cases.
Recent commercial moves underscore a market shifting from point-solutions to integrated systems: major equipment vendors have announced orders and technology partnerships in the past 12–18 months that reflect escalating demand for plant-level energy autonomy and circular-resource outcomes. Market concentration remains moderate (the top-three and top-five supplier shares indicate room for new entrants and consolidation), which preserves both competitive pressure and collaboration opportunities for strategic partners.
Regulatory and policy context shaping 2026 choices
Policy instruments are a critical input to any capex decision. Notable developments captured in the report include:
- EU-level directives tightening energy and emissions performance expectations for wastewater utilities, with compliance timelines that force near-term capital decisions for larger plants.
- National and subnational net-zero commitments (for example, near-term UK targets) that shape procurement criteria and the types of commercial guarantees required by regulators and rate-setting authorities.
- Established frameworks such as the U.S. EPA’s biosolids and land application rules, which continue to influence the acceptable end-uses and regulatory approvals for resource-recovery outputs.
These policy drivers increase the value of technologies which demonstrably reduce GHG intensity while preserving or improving biosolids quality, accelerating adoption cycles for anaerobic and thermal-hybrid approaches.
Five strategic actions for 2026
- Run a site-priority heatmap: use our scoring tool to identify plants with the highest energy-reduction ROI over a 5–7 year horizon and sequence pilots accordingly.
- Prefer modular, staged architectures: select technology stacks that allow pilot-to-scale conversion without stranded asset risk; hybrid architectures ease the regulatory and financing path.
- Lock performance guarantees into procurement: insist on energy and biogas-yield guarantees tied to liquidated damages or shared-savings mechanisms to align incentives.
- Explore partnership structures: for municipalities and smaller utilities, consider joint ventures or long-term concession models with technology vendors to de-risk capex and leverage vendor expertise in O&M.
- Integrate policy scenario planning into business cases: stress-test projects against accelerated decarbonisation scenarios and energy-price sensitivities to protect against downside risk.
How PW Consulting’s report supports your 2026 agenda
The report equips decision-makers with the quantitative templates, comparative vendor intelligence, and regulatory playbooks required to move from strategy to execution in 2026. It is purpose-built for deal teams, plant managers, and public-sector procurement offices seeking defensible, audit-ready analyses to support board approvals and regulatory filings.
To preserve commercial advantage and encourage direct engagement, this briefing highlights strategic findings while reserving detailed regional and application-level splits, unit price decks, and asset-level project models for the full report. These granular data sets and the underlying Excel modelling modules are available in the comprehensive deliverable and on our web portal for licensed clients.
Next steps
If your organisation is evaluating sludge treatment investments or needs to update its decarbonisation roadmap for 2026, PW Consulting can provide bespoke briefings, workshop facilitation, or site-level economic re-runs using the report’s models. Contact our industry practice to schedule an in-depth executive session and to obtain the full report and its reproducible modelling annexes.
For detailed analysis of this topic, please visit the official page: Worldwide Energy Efficient Sludge Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com