

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Home Security Market Poised for 8.92% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
Home Security Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s lead industry analyst, I present a strategic preview of our new Home Security Market study—designed specifically to inform boardroom decisions in 2026. This preview synthesizes the empirical trajectory of the market, the structural forces reshaping competitive economics, and the practical levers executives should prioritize. It demonstrates the analytical depth of our full report while intentionally withholding detailed subsegment tables and regional splits to encourage direct access to the full intelligence package.
Home Security Market
Market at a glance: growth trajectory and structural context
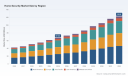
The home security market is on a sustained expansion path. Using 2025 as our base year, PW Consulting’s market model documents growth from approximately USD 42.4 million in 2020 to USD 67.3 million in 2025, and then projects a continuation of that expansion to roughly USD 122.8 million by 2032. This represents a compound annual growth rate (CAGR) of 8.92% across the forecast period (2026–2032). The late-stage acceleration in our forecast reflects intensifying adoption of AI-enabled video analytics, the ongoing transition to cloud-native platforms, and higher ARPU (average revenue per user) through value-added services such as advanced monitoring, automation bundles, and recurring software revenues.
Home Security Market
Two structural features are critical for 2026 strategy: (1) the market has meaningful concentration at the top—our CR3 and CR5 metrics measure 62% and 72% respectively—indicating leading vendors command significant distribution, brand, and monitoring-platform advantages; and (2) the business model bifurcation between DIY, professionally installed, and recurring monitoring plays continues to create differentiated margins and customer lifetime value profiles. Understanding where your organization sits on that spectrum determines the optimal set of investments for 2026.
Home Security Market
Why this research matters for 2026 decisions
- Capex versus recurring-revenue tradeoffs: Our model quantifies the tradeoffs between one-time hardware revenue and subscription-based monitoring/analytics. For executives considering platform investments or pricing restructures in 2026, the choice materially affects EBITDA conversion over a 36–60 month horizon.
- Technology bifurcation: Edge-first, privacy-preserving AI and cloud-centric SaaS platforms are not mutually exclusive, but they demand distinct product roadmaps and partner ecosystems. The study maps where interoperability investments yield the highest strategic ROI.
- Regulatory and infrastructure sensitivity: The industry now operates against a backdrop of regulatory churn and rising infrastructure costs—factors that will influence network dependency, deployment economics, and go-to-market timing.
- M&A and consolidation playbook: With a concentrated top quintile, the report identifies pragmatic bolt-on targets, integration risks, and value capture scenarios for acquirers seeking to expand monitoring footprints or verticalize software stacks.
Report contents—practical, decision-grade deliverables
PW Consulting’s full report is built to be operationally useful to strategy, corporate development, product, and sales leaders. It includes:
- Executive summary and topline market model (base year 2025; historical window 2020–2025; forecast 2026–2032) with sensitivity scenarios calibrated to macro and regulatory shocks.
- Customer economics and LTV/CPA matrices for DIY, professional-install, and managed monitoring business models—presented as actionable levers rather than raw market-share tables.
- Channel and partner economics: dealer networks, telco bundles, and retail/online pathways—paired with go-to-market playbooks for incremental subscriber growth and upsell sequencing.
- Technology and product taxonomy: capabilities map (AI analytics, Wi‑Fi sensing, battery-first devices, edge-cloud orchestration) linked to cost-to-serve and margin implications.
- Vendor benchmarking and win-loss profiles: strategic positioning, product gaps, and potential M&A targets. (Note: our public preview highlights vendor themes; the full report contains detailed scorecards.)
- Regulatory and infrastructure risk scenarios with quantitative overlays—showing how network reclassification or increased FTTH O&M costs could compress time-to-payback for certain models.
- Playbooks for pricing, bundling, and international expansion—each with estimated financial impact ranges and execution milestones.
To honor the "trailer" principle, the report selectively withholds granular regional and application breakdowns from this preview; those segment-level tables are available only within the full research package.
Competitive landscape—who shapes outcomes in 2026
The competitive dynamics are dominated by firms that combine distribution, monitoring infrastructure, and platform capability. Key players we profile in depth include ADT, Vivint, Ring LLC, SimpliSafe, Alarm.com, Brinks Home Security, Abode Systems, Eufy Security, and Johnson Controls. Each brings different strategic advantages:
- ADT: Historically strong in professional monitoring and installation, ADT has accelerated its smart-home play by acquiring AI capabilities to broaden sensing modalities. This signals a shift toward differentiated, privacy-respecting detection capabilities beyond cameras.
- Vivint: A full-stack integrator that competes on seamless installation and integrated automation. Its model favors higher upfront revenue and premium recurring services.
- Ring: A mass-market innovator focused on video doorbells and camera-led detection, increasingly blending DIY affordability with optional professional monitoring.
- SimpliSafe: A leader in DIY, contract-light propositions—appealing to a customer segment that prioritizes flexibility and lower acquisition barriers.
- Alarm.com: A software- and platform-centric vendor; its recent 2026 platform modernization and AI video enhancements underscore the competitive premium on interoperability and analytics.
- Brinks Home Security, Abode, Eufy, Johnson Controls: Each occupies niches—from legacy brand trust to Apple ecosystem integration, battery-first camera economics, and upgraded residential panels—that together portray a market where specialization and platform partnerships win specific cohorts.
Recent industry moves illustrate the tactical environment for 2026. Alarm.com’s platform modernization (April 2026) and expanded AI video portfolio (March 2026) underline how software capability is a near-term differentiator. ADT’s February 2026 acquisition to add Wi‑Fi sensing capabilities indicates a race to diversify sensing beyond cameras. Ring and Johnson Controls product updates in early 2026 point to sustained hardware innovation—particularly in higher-resolution and lower-power devices. Collectively, these moves imply that 2026 will be a year of execution: integrating new capabilities rapidly and proving commercial models that convert them into recurring revenue.
Market dynamics and risk factors
- Regulatory uncertainty: The sector faces legal and regulatory headwinds related to broadband classification and data privacy, creating a shifting compliance landscape. Recent legal rulings and regulatory votes have produced a mix of signals that increase policy execution risk for telco partnerships and cloud-delivered services.
- Infrastructure cost inflation: Rising deployment and O&M costs for fiber and last-mile networks—exacerbated by materials and labor inflation—raise the marginal cost of high-bandwidth features (e.g., always-on video). This elevates the importance of edge processing and bandwidth-efficient analytics in 2026 product roadmaps.
- Technology substitution: The emergence of non-camera sensing (e.g., Wi‑Fi sensing, radar, and improved door/window sensors) threatens to rebalance value between hardware and analytics, changing per-subscriber economics.
- Concentration risks: With a significant share captured by the top firms, challenger brands must either specialize or form distribution partnerships to scale economically.
Strategic imperatives for 2026
- Prioritize recurring revenue clarity: Run scenario modeling on subscription pricing and retention sensitivity to inform product packaging decisions this year.
- Invest selectively in AI at the edge: To mitigate bandwidth exposure and differentiate on privacy-sensitive features, edge-first analytics should be prioritized for new hardware launches.
- Choose partner strategies with care: Telco and retail partnerships can accelerate reach but come with margin tradeoffs; negotiate platform revenue shares tied to monitoring retention KPIs.
- Build M&A playbooks now: Identify small targets that materially accelerate capabilities (e.g., sensing IP, software modules, regional dealer networks) and pre-define integration metrics to speed execution if opportunities arise.
Conclusion and next steps
PW Consulting’s Home Security Market study is designed as a decision-grade tool for 2026 leadership teams. It combines a rigorously validated market model (2020–2025 history; 2026–2032 forecast) with practical playbooks for pricing, product, and M&A. This preview aims to surface the most consequential strategic tradeoffs—without revealing the granular subsegment tables that materially affect competitive positioning and valuation. For teams preparing budgets, capex plans, acquisition screens, or product roadmaps this year, the full report provides the granular, downloadable models and vendor scorecards necessary to act with confidence.
To gain full access to the segment-level breakdowns, scenario workbooks, and vendor scorecards referenced here, please consult the PW Consulting report portal where the complete Home Security Market research package is available.
For detailed analysis of this topic, please visit the official page: Home Security Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Luxury Sunglasses Market to Hit $19.78B by 2032 at 4.59% CAGR
By pmarketresearch, 2026-07-23
Luxury Sunglasses Market — Strategic Outlook for 2026 Decision-Making
As companies prepare budgets, M&A roadmaps, product pipelines, and go-to-market plays for 2026, the luxury sunglasses market presents a balanced mix of steady growth, strategic consolidation, and disruptive technological and regulatory pressures. This briefing—drawn from PW Consulting’s comprehensive market study, base year 2025, historical window 2020–2025 and forecast horizon 2026–2032—highlights the high-level implications executives must weigh now. The full report contains the granular charts, segment tables, and scenario spreadsheets that underpin the conclusions summarized below.
Luxury Sunglasses Market
Market trajectory and what it means for 2026 plans
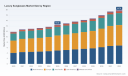
Across the five-year historical period through 2025 the global luxury sunglasses market expanded consistently, reaching a market size of USD 14.45 Billion in the base year. Our forecast window (2026–2032) projects continuation of that growth at a compound annual growth rate (CAGR) of 4.59%, bringing the market to roughly USD 19.78 Billion by 2032 under the baseline scenario.
Luxury Sunglasses Market
For corporate planners, the takeaway is twofold. First, the market is large and predictable enough to justify multi-year investments in brand-building, premium product lines, and supply-chain optimization. Second, growth is not explosive; it rewards disciplined capital allocation and strategies that extract margin through product differentiation, channel control, and cost containment rather than betting on blue‑sky volume expansion alone.
Luxury Sunglasses Market
Competitive structure and strategic consequences
The competitive landscape shows meaningful concentration among leading players, with the top three and top five firms controlling significant shares of the market (CR3 and CR5 at 48.5% and 65.2% respectively). That structure creates both constraints and opportunities for new entrants and incumbents:
- Incumbents benefit from scale in licensing, global distribution, and brand equity—advantages that translate into negotiating power with retailers, preferred access to premium materials, and higher tolerance for short-term price volatility.
- Mid-sized and niche firms can still win by specializing (material craftsmanship, regional cultural resonance, limited-edition drops) and by owning superior DTC experiences and creative collaborations.
Key firms to watch include EssilorLuxottica, the group whose brand and licensing portfolio covers household names and designer collaborations; Italian manufacturers such as Marcolin, De Rigo and Safilo, which combine manufacturing heritage with global license partnerships; and artisanal or boutique players like Garrett Leight and Oliver Peoples that trade on craft, provenance, and selective distribution. Each archetype implies different strategic moves for competitors and partners: from defensive licensing and scale investments to targeted partnerships, white-label production agreements, or acquisitions to gain heritage credentials.
Notable corporate moves and regulatory noise shaping 2026
Recent developments through mid‑2026 emphasize three themes that should be central to corporate strategy next year: premiumization via designer partnerships, technology integration, and tariff-driven cost pressure.
- Design & licensing: Major players continue to lock in long-term licensing deals and capsule collections with luxury houses, reinforcing premium positioning and customer lifetime value. Such partnerships remain high-return plays for companies that can manage production quality and channel control.
- Technology & product innovation: The incorporation of smart/AI-enabled features into eyewear is transitioning from novelty to a product line consideration for mainstream luxury brands. Early waves of hybrid offerings (optical prescription frames with digital features) create adjacent revenue pools and new after-sale service models.
- Tariffs & trade policy: Elevated import duties on optical products—together with episodic policy pauses and unpredictable reciprocal measures—have materially affected landed costs and pricing strategies. Some legacy producers have already moved to mitigate exposure through price increases and supplier diversification.
These dynamics are exemplified by public actions in the market: multi-year licensing renewals, high-profile capsule collections, expansions of AI/glasses portfolios targeted at prescription wearers, and price adjustments implemented to offset tariff impacts. Executives must plan for continued regulatory volatility while exploiting design and tech as sources of differentiation.
What the PW Consulting report offers (practical content)
Our full study was designed as a decision-making toolkit for 2026. It blends rigorous quantitative forecasts with practical, executable guidance:
- Market sizing and validated forecast models across multiple scenarios (baseline, downside, upside) calibrated to tariff, channel, and macroeconomic permutations;
- Channel economics and margin waterfall analyses for wholesale, retail, and direct-to-consumer (DTC) models, identifying where margin can be recovered or enhanced;
- Supply-chain stress tests and sourcing playbooks—evaluating nearshoring, dual-sourcing, and inventory strategies to manage high-duty exposure;
- Consumer segmentation and purchase-motive matrices that translate psychographics into product and price strategies (note: the report contains the segment-level shares and elasticity estimates omitted from this preview to preserve commercial value);
- Product roadmap guidance, including how to integrate smart features without cannibalizing classic premium lines, and material-sourcing recommendations for sustainable, high-margin offerings;
- M&A and partnership screeners—financial thresholds and cultural fit heuristics for deals that accelerate scale, augment brand portfolios, or secure manufacturing competence;
- Operational playbooks for retail footprint optimization and omnichannel orchestration, with KPIs, pilot templates, and a 12–24 month rollout calendar;
- Primary interview summaries and supplier scorecards that validate costs, lead times, and quality differentials used in our forecast models.
We deliberately present the high-level recommendations here while retaining the full tables and sensitivities behind the paywall so decision-makers can test moves against their unique P&L assumptions.
Strategic priorities for 2026
Based on the intersection of steady CAGR, market concentration, product innovation, and tariff risk, we advise leaders to prioritize six actions in 2026:
- Institute a tariff-response program: model landed-cost scenarios, negotiate contractual protections with suppliers, and implement staged price actions tied to clear cost triggers;
- Double down on premiumization where your brand equity supports it—limited editions, luxury licenses, and craft-backed product stories enhance margins and reduce price elasticity;
- Accelerate selective tech integration: pilot AI/smart eyewear in core markets with controlled production runs and service bundles to evaluate willingness-to-pay and brand fit;
- Optimize omnichannel economics by reallocating capex to high-ROI DTC experiences and using wholesale selectively as a distribution amplifier rather than a margin sink;
- Pursue bolt-on M&A or licensing that fills capability gaps—manufacturing, optical tech, or prestige labels—while maintaining strict integration criteria and return hurdles; and
- Embed sustainability and traceability into premium narratives: consumers of luxury are increasingly sensitive to provenance, which can justify price premiums and reduce reputational risk.
Risks, sensitivities, and scenario levers
Although growth is steady, the luxury sunglasses market is sensitive to a limited set of high-impact variables:
- Trade policy volatility—sudden tariff adjustments or retaliatory measures can compress margins quickly; companies should hold contingency pricing and supply plans ready;
- Consumer discretionary cycles—premium eyewear sits in discretionary spend pockets and will bend with broader luxury consumption trends;
- Platform & distribution disruption—shifts in social commerce, resale channels, and vertical DTC brands can alter competitive placement rapidly;
- Technological missteps—over-investing in tech-enabled eyewear before clear consumer acceptance may dilute core brand equity and tie up capital.
Our scenario analysis—available in the full report—quantifies the P&L implications of these levers and prescribes triggering conditions for defensive vs. offensive moves.
How to use this intelligence in boardroom decisions
Executives should use the study to inform four board-level decisions in 2026: capital allocation (where to invest vs. conserve), pricing strategy (dynamic vs. fixed), channel mix (which channels to double down on), and inorganic growth (targets and timing). The report’s models allow custom inputs so leadership teams can run their own sensitivity analyses and produce credible, data-backed plans for investors and lenders.
Next steps
This preview demonstrates the depth and orientation of PW Consulting’s Luxury Sunglasses Market study: rigorous modeling, actionable playbooks, and scenario-tested strategic recommendations. To access the full dataset, segmentation tables, and our proprietary forecast workbook—including the detailed sensitivities on tariffs, channels, and consumer segments—please consult the report landing page or contact your PW Consulting representative. The full intelligence package is designed to be plug-and-play for 2026 planning cycles and to support rapid decision-making under uncertainty.
In markets where growth is steady but risks are concentrated, strategic clarity wins. The decisions companies take in 2026 about sourcing, partnerships, and product architecture will determine who captures the next wave of premium margin expansion in the luxury sunglasses category.
For detailed analysis of this topic, please visit the official page: Luxury Sunglasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Office Storage to Rise from USD 3.15B (2025) to USD 5.34B by 2032 at 7.9% CAGR
By pmarketresearch, 2026-07-23
Office Storage & Organization Market 2026: Strategic Imperatives for Corporate Decision-Makers
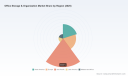
As organizations recalibrate workplace strategies for a hybrid, cost-sensitive era, the Office Storage & Organization market has moved from a back-office procurement item to a strategic lever for productivity, space optimization and capital allocation. PW Consulting’s latest market study—anchored to a 2025 base year and projecting through 2032—maps that trajectory with rigorous scenario modeling: the global market reached approximately USD 3.15 Billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 7.9% over the coming cycle, finishing the forecast horizon materially larger by 2032. For executives planning capex, workplace redesigns, or supplier consolidation in 2026, the report translates these macro dynamics into actionable choices.
Office Storage & Organization Market
Why this research matters for 2026 decisions
-
Timing and scale: The sector’s near-term momentum and sustained mid-term growth mean procurement windows and roll-out schedules have different payoffs depending on whether organizations pursue rapid retrofit projects or phased modular investments. Our study quantifies the trade-offs and identifies inflection points where cost-of-delay exceeds the benefits of waiting for price normalization.
Office Storage & Organization Market -
Risk-adjusted sourcing: With raw-material and labor-cost volatility continuing to bite, buyers who align purchase timing, warranty terms and supplier risk-sharing structures will preserve margins. The research provides practical sourcing structures and contract templates tailored to present market stressors.
Office Storage & Organization Market -
Productivity ROI: Storage and organization decisions now influence real estate utilization, employee experience and records/compliance management. Our economic models tie storage choices to measurable productivity and space-savings outcomes, enabling finance teams to evaluate investments with enterprise-grade rigor.
Market snapshot — what the numbers tell us (high level)
After a resilient recovery in the early 2020s, demand for office storage and organizational solutions has resumed steady expansion. The market’s compound growth reflects several converging forces: continued investment in office modernization, a rise in remote/home-office needs that reshapes product mixes, and renewed spending in sectors prioritizing secure records and asset management. While macro headwinds—most notably cost pressures on inputs and labor—temper margin expansion for manufacturers and distributors, the net demand trajectory remains positive, offering multiple routes to capture value.
Report scope: practical outputs for operators and investors
PW Consulting’s study is designed to be a working tool for decision-makers, not just a reference. Key deliverables include:
- Market sizing and validated forecast models (2020–2032) with scenario sensitivity to input-cost, labor, and regulation shifts.
- Procurement playbooks for different buyer archetypes (corporate real estate teams, facilities managers, small-business consolidators), including RFP templates and supplier scorecards.
- Capex vs. Opex analysis for modular and high-density storage investments, with break-even horizons modeled under multiple occupancy scenarios.
- Compliance and safety checklists referencing current occupational-load and fire-resistance standards, with supplier certification matrices.
- Competitive benchmarking and vendor selection frameworks that map technology, scale, and channel strengths to buyer requirements.
- Implementation roadmaps and change-management guidance to ensure adoption and measurable productivity gains post-deployment.
Competitive landscape — strategic takeaways
The market exhibits a mix of specialized manufacturers, integrated furniture conglomerates, and retail/channel players. Rather than a winner-takes-all dynamic, the landscape favors companies that combine product innovation, distribution agility and services that remove total-cost-of-ownership friction.
-
Office Furniture EZ (Colorado Springs, USA) — A hybrid distributor with showroom and e-commerce capabilities. Their 2026 product catalog release signals a continued focus on omnichannel sales and curated solutions for small-to-mid enterprises. Strategic implication: competitors that lack an integrated online-to-showroom experience will struggle to match their conversion economics among SMB buyers.
-
SHUTER (Taiwan) — A manufacturer emphasizing innovation and durability in modern cabinets and organizational systems. Recent cataloging suggests an iterative product development cadence geared to export markets. Strategic implication: their engineering depth makes them a logical partner or acquisition target for regional distributors seeking differentiated product lines.
-
Livinbox (Taiwan) — Known for stylish, modular solutions for home and office environments; product showcases in global trade events underline a push into lifestyle-oriented office storage. Strategic implication: brands that bridge home-office aesthetics with enterprise standards can open new channel opportunities in corporate gifting, remote-work stipends and employee onboarding kits.
-
HNI Corporation (Muscadine, USA) — An incumbent with integrated workplace furniture and high-density storage capabilities. Their scale and integrated offerings position them well for large corporate and contract clients. Strategic implication: expect continued competition on bundled furniture + storage solutions, with price-pressure on standalone storage vendors.
-
Spacesaver Corporation (Fort Atkinson, USA) and Montel Inc. (Montreal, Canada) — Specialists in high-density and mobile storage systems. Their technical differentiation makes them preferred suppliers where space optimization and archival access are critical. Strategic implication: these players will dominate projects where space-per-staff economics are measured in single-digit percentages.
-
The Container Store (Dallas, USA) and Ikea (Sweden) — Retailers that drive accessibility and price competition, particularly for home-office and small-business channels. Strategic implication: they compress the low-end margin pool but also expand market penetration, creating volume opportunities for suppliers that can cost-effectively serve retail programs.
Recent industry movements and what they mean
-
Product catalog and showcase activity from several vendors in 2025–2026 signals that manufacturers are prioritizing refreshed portfolios to capture hybrid-work demand. Buyers should evaluate product life-cycles and availability lead times when planning 2026 roll-outs.
-
Market noise on labor and raw-material costs is not temporary background: the wood office-furniture PPI indexed near 295.7 in mid-2025, and steel/plastics volatility persists. These inputs are compressing manufacturer margins and prompting tiered pricing and longer lead times—factors that materially affect procurement strategies.
-
Regulatory tightening on load-bearing and fire-resistance standards increases supplier validation requirements. Teams should bake compliance verification into supplier selection rather than treating it as post-hoc diligence.
Risks, headwinds and mitigation strategies
-
Input-cost inflation: Adopt indexed pricing clauses, multi-sourcing strategies and inventory hedging where appropriate.
-
Regulatory compliance risk: Shift to certified suppliers, demand third-party testing documentation, and include warranty and liability protections in contracts.
-
Channel disruption: Retail entrants and direct-to-consumer brands compress margins—differentiate by packaging services (installation, asset tagging, maintenance) rather than competing on headline unit cost.
Investment, financing and procurement levers for 2026
For capital planners, two practical levers deserve attention. First, financing programs—such as long-term small-business loans available in some jurisdictions—can shift high-cost capex into structured, predictable repayments and accelerate deployment where ROI is front-loaded. Second, supplier partnership models that include performance-based rebates and lifecycle service bundles can convert purchase price into a managed-operating cost, smoothing budget impact and tying payoffs to realized space/utilization gains. PW Consulting’s report includes sample financial structures and sensitivity analyses tailored to common corporate procurement policies.
Opportunities to watch
-
High-density, mobile shelving and modular systems that enable flexible space repurposing will command premium consideration among space-constrained occupiers.
-
Product lines that combine aesthetic appeal with enterprise-grade safety and security (e.g., lockable, fire-rated modular cabinets) create cross-segment demand from corporate HQs to remote-office programs.
-
Sustainability credentials—recycled-content panels, cradle-to-grave takeback programs—are increasingly procurement decision criteria in RFPs and ESG reporting frameworks.
How to use PW Consulting’s full study
Consider the report your operational playbook for 2026: use the included supplier scorecards to shortlist vendors, the procurement templates to run compliant and competitive RFPs, and the ROI models to secure capex approvals. For investors, the competitive landscape analysis highlights consolidation targets and margin-lever opportunities; for corporate real estate and facilities teams, the implementation roadmaps convert strategic intent into milestones and KPIs.
Conclusion — a path to action
The Office Storage & Organization market in 2026 is neither a commodity space nor a boutique niche—it’s a configurable capability whose design and supply-chain choices ripple across occupancy economics, employee productivity and compliance risk. PW Consulting’s market research translates the sector’s steady growth and structural shifts into pragmatic, executable strategies. To access the complete dataset, granular segment analysis, and downloadable procurement tools that underpin these recommendations, consult the full report on our website—our trailer here shows the direction; the detailed intelligence is available in the source material for practitioners who need to act in 2026.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Motorcycle Gear Market to Expand at 5.6% CAGR Through 2032
By pmarketresearch, 2026-07-23
Motorcycle Gear Market 2026: Strategic Imperatives from PW Consulting
As companies plan their strategic moves for 2026, the motorcycle gear market presents a study in contrasts: a clear recovery curve after a multi-year contraction, accelerating technological and sustainability-driven product cycles, and a regulatory environment that has grown both more prescriptive and more consequential. This introduction summarizes why PW Consulting’s new Motorcycle Gear Market research report is indispensable for executives who must convert market signals into defensible commercial action in 2026.
Motorcycle Gear Market
Why this timing matters
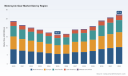
The market’s macro story is straightforward but actionable. After peaking in the early 2020s, total industry revenues contracted through 2025 — with the PW Consulting base year set at 2025 — creating compressed margins and clearance-driven inventories across multiple product categories. Our market sizing shows the overall market moving from a pre-contraction level in 2020 to a lower trough in 2025, before an inflection beginning in 2026 and a steady climb across our forecast window to 2032. The forecasted compound annual growth rate for the 2026–2032 period is 5.6% (USD, Million), and the market is projected to return to and exceed its earlier scale by the end of the forecast period.
Motorcycle Gear Market
For leadership teams, these dynamics mean 2026 is the year to shift from defensive tactics (inventory reduction, promotional discounting) to growth positioning—if you can mobilize clean capital, upgrade compliance processes, and accelerate product differentiation without re-creating legacy cost structures.
Motorcycle Gear Market
What PW Consulting’s study delivers (practical components)
- Granular market sizing and a rigorously validated forecast framework (historical 2020–2025; forecast 2026–2032) expressed in USD Million, with a clear explanation of assumptions and sensitivity cases.
- Competitive landscaping that goes beyond logos — we analyze capability maps, product roadmaps, channel footprints, and relative strength in key go-to-market motions.
- Regulatory and product-safety risk matrices, including recall case studies and compliance gap analysis specifically tailored for North American FMVSS and EU homologation variants.
- Supplier and cost-stack benchmarking covering raw materials (including emerging recycled membranes and biobased textiles), manufacturing labor, and logistics — with levers for near-term margin recovery.
- Commercial playbooks: launch sequencing for premium versus value tiers, omnichannel distribution optimization, pricing elasticity models, and merchandising strategies for core SKUs.
- M&A and partnership scoping: target profiles, accretion/dilution scenarios, and integration checklists for bolt-on capabilities (e.g., protective tech, sustainable textiles, digital services).
- Scenario planning templates for demand shocks, regulatory escalations, and rapid cost inflation — ready to be adapted into a 2026 board pack.
Market dynamics: what’s driving the next phase
- Safety regulation and enforcement : Recent high-profile recalls have re-centered safety as a non-negotiable commercial and reputational risk. Regulatory activity in early 2026 underlines the need for robust product testing, traceability, and post-market surveillance in supplier contracts.
- Product innovation & materials : Technical advances — from integrated armor packages to weather-proofing systems and recycled technical membranes — are accelerating product life cycles. Consumers increasingly pay a premium for demonstrable performance and sustainability credentials.
- Channel maturation : Omnichannel retailing is now table stakes. Brands that blend experiential retail, direct-to-consumer digital engagement, and strategically layered wholesale partnerships are gaining disproportionate share of wallet.
- Concentration and competitive intensity : The market shows moderate concentration at the top: the largest three players control a meaningful plurality of sales, and the top five extend that influence further. This concentration shapes distribution access, supplier bargaining, and brand citation in tiered channel relationships.
- Regional recovery and premiumization : After the contraction into 2025, recovery is heterogeneous by region and use-case, but premium technical and protection-led products consistently outperformed undifferentiated commodity items during early signs of demand renewal.
Competitive landscape — what to watch from leading players
The competitive field blends legacy European performance brands, North American technical specialists, and rising regional players. Our report profiles each major participant with emphasis on their product architecture, manufacturing levers, channel behavior, and strategic intent. A few illustrative insights:
- Alpinestars — Longstanding strength in racing-grade performance products and a clear playbook for translating motorsport credibility into consumer premiumization. Watch their product modularity and licensing moves.
- Dainese — Deeply associated with protective technology and rider safety; their October 2025 launch of eco-friendly lines signals an aggressive dual-pronged approach: safety as baseline, sustainability as premium differentiator.
- REV'IT! — A European technical touring and urban specialist that competes on fit, weatherproofing, and integrated feature sets; they are important to benchmark for functional design and mid-premium channel partnerships.
- Fox Racing — Dominant MX/off-road position and a youth-oriented branding engine; their distribution networks and licensing deals create durable access to the next generation of riders.
- Klim — Notable for adventure/touring systems and material innovation; their EICMA 2025 showcase of integrated armor and updated GORE‑TEX lines points to an engineering-first strategy.
- Leatt — A differentiated safety-tech specialist focused on neck and spinal protection, valuable as a potential technology partner or acquisition target for brands seeking instant protective credibility.
- Aerostich and Rukka — Premium touring and weatherproofing stalwarts whose emphasis on durability and lifetime utility appeals to high-value customer cohorts.
- Regional and value players (e.g., Rynox Gears) — Rapidly expanding in local markets, combining cost advantage with improved design, and representing both competitive pressure and potential channel partners for global brands.
Each company profile in the full report includes HQ, distribution footprint, SKU focus, key recent product launches, and an assessment of strategic vulnerability and opportunity. That contextual granularity informs playbooks on whether to compete, collaborate, or acquire.
Recent events that change the risk calculus
- Trade show intelligence (EICMA 2025) : Several participants used EICMA to debut refreshed protection systems and sustainable product lines — a clear signal that trade-show ROI is shifting toward functional prototype exposure and pre-order funnels rather than pure brand theatre.
- Regulatory actions (Jan–Feb 2026) : Government recalls focused on helmet impact-protection compliance have immediate implications for product testing regimes, supplier audits, and warranty provisioning. Firms must reassess acceptance criteria for inbound helmets and document chain-of-custody.
- Sustainability and materials cost pressure : Demand for recycled membranes and biobased textiles is growing, yet these materials introduce both cost and supply-chain complexity; our cost-stack models quantify break-even points for premium pass-through versus margin compression.
How to use this report in 2026 decision cycles
Executives will find three immediate use cases:
- Investment prioritization — Use our sensitivity-tested revenue and margin scenarios to allocate R&D, inventory, and marketing spend with defensible ROI thresholds over a 24–36 month horizon.
- Regulatory & product safety remediation — Adopt the report’s compliance playbook, which maps testing protocols, audit checklists, and customer-communications templates proven to reduce time-to-market disruption.
- M&A and partnership screening — Apply the acquisition scorecards and synergy calculators to shortlist targets that accelerate tech competencies (e.g., armor systems, sustainable textiles) without undermining channel relationships.
Recommendations — the strategic checklist for 2026
- Re-center product development on verifiable safety metrics and modular protective systems; factor certification timelines into each SKU roadmap.
- Segregate capital for sustainability initiatives that can be monetized through premium pricing or loyalty-driven repeat purchase economics.
- Rebalance inventory strategies from blanket discounting to targeted campaigns that preserve full-price sell-through for newly differentiated SKUs.
- Execute supplier audits and develop a two-tier sourcing strategy to insulate critical components from single-source disruption.
- Invest in digital direct-to-consumer capabilities that both capture higher margin and provide first-party data for ongoing product optimization.
- Use M&A selectively to acquire capability gaps (protective technology, certification labs, or unique material supply) rather than merely scale volume.
Next step — why read the full PW Consulting report
This introduction outlines the strategic context and the high-level levers available to executives in 2026. The full Motorcycle Gear Market report provides the underlying quantitative architecture — including our verified historical time series, scenario-based forecasts across 2026–2032, company-level capability matrices, and actionable templates for compliance, sourcing, and commercialization. Crucially, the detailed segmentation, regional channel breakdowns, and company financial proxies are intentionally reserved for the full report to ensure you have the depth required to act with conviction.
Contact PW Consulting to access the full study and the Excel-based toolkit that will enable your leadership team to convert the 5.6% CAGR opportunity and the post-2025 market recovery into measurable business outcomes.
For detailed analysis of this topic, please visit the official page: Motorcycle Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Niobium Carbide Market to Reach USD 62.43M in 2026, 5.1% CAGR — PW Consulting
By pmarketresearch, 2026-07-23
Niobium Carbide Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our forthcoming Niobium Carbide Market study. This briefing translates rigorous market modelling into clear implications for executives preparing for 2026 — showing where value and risk are concentrated, how competitive dynamics are reshaping supplier choice, and which regulatory and feedstock trends will determine margin capture. The purpose here is to demonstrate the report’s evidence‑based depth while deliberately reserving granular segment tables and proprietary model outputs for the full report.
Niobium Carbide Market
Market snapshot (what the numbers tell us)
Using 2025 as the base year and a historical window covering 2020–2025, our model quantifies a steady expansion of the Niobium Carbide market. The market recorded low‑double‑digit growth between 2020 and 2025 and, based on our forecast envelope for 2026–2032, follows a compound annual growth rate (CAGR) of approximately 5.1% (USD, revenue unit: Million). In concrete terms: the industry moves from a mid‑tens‑of‑millions USD footprint in the early 2020s to a materially larger, high‑tens to low‑hundreds million USD opportunity by the early 2030s under a central case. These macro metrics validate continued commercial relevance — but they also mask diverging dynamics within purity grades, forms, and end‑use channels that will drive winner‑take‑most economics in pockets of the value chain.
Niobium Carbide Market
Why this matters for 2026 planning
- Budgeting and CapEx: A predictable, mid‑single‑digit CAGR allows capital planners to prioritize modular capacity expansions over large, lumpy greenfield investments, unless pursuing vertical integration or domestic feedstock security.
- Supply risk & sourcing: Regulatory shifts and critical‑mineral policies are raising the value of near‑term supplier certainty — firms should re‑evaluate sourcing strategy and contract tenure now, not later.
- Product strategy: Performance differentiation increasingly stems from material purity, grain size control and form (powder vs. target vs. flakes). R&D and quality assurance investments yield disproportionate returns in aerospace, defense and advanced coatings segments.
Key demand and supply dynamics
Drivers: Niobium Carbide’s demand profile is anchored in industrial tooling, advanced coatings, cermet and aerospace applications. Technical trends — such as finer grain hardmetals for higher cutting speeds, sputtering targets for electronic thin films, and tailored purity grades for defense/aerospace — are elevating the price‑per‑unit opportunity for premium NbC products.
Niobium Carbide Market
Feedstock & cost structure: Niobium oxide remains the primary feedstock for NbC production. Fluctuations in oxide availability and upstream niobium pricing transmit directly to downstream margins. Manufacturers with secured oxide streams, integrated processing, or recycling pathways gain both margin stability and commercial optionality.
Regulatory & policy environment: Governments are increasingly treating niobium as a strategic input. Recent designations and export controls in key jurisdictions introduce non‑price barriers and create localized demand for domestically compliant supplies. Additionally, chemical registration regimes require manufacturers to maintain product registrations and compliance dossiers — a nontrivial fixed cost that favors established suppliers.
Regulatory signals executives cannot ignore
- Critical mineral status and defense funding are accelerating domestic exploration and processing programs in the United States — an important factor for firms considering onshore partners or greenfield projects.
- Export control listings in certain countries increase transaction friction for strategic applications and encourage sourcing diversification.
- ITAR (for defense/aerospace applications) and TSCA (for U.S. chemical registration) create compliance hurdles that impact time‑to‑market and supplier eligibility; firms must budget for certification and audit cycles when qualifying suppliers.
Competitive landscape — what the incumbents signal
The market exhibits moderate concentration at the top: the three‑firm and five‑firm concentration ratios indicate that a small group of vendors account for a meaningful portion of global supply, while a long tail of specialist and regional suppliers addresses niche requirements. That structure produces four strategic implications: pricing power for high‑quality producers, opportunity for niche entrants that can match technical specs, M&A utility for buyers seeking scale, and supplier risk for large OEMs dependent on a limited number of certified sources.
Profiles of strategic players (select observations):
- H.C. Starck Tungsten Powders (Goslar, Germany): A technical leader in high‑purity NbC and mixed Ta/Nb carbides with finely controlled grain sizes. Their product positioning is oriented toward cutting tools and grain‑growth control applications — making them a natural partner for hardmetals manufacturers seeking performance consistency.
- CBMM (Araxá, Brazil): A primary producer with recent product innovation; the company’s 2025 launch of a new high‑purity NbC grade underscores its intent to serve aerospace and defense segments where material traceability and purity command premium pricing.
- China Molybdenum Co., Ltd. (Beijing): Offers NbC tailored to electronics and high‑performance end‑uses — a strategic foothold given the scale of regional electronics manufacturing and localized supply chains.
- NioCorp Developments (Elk Creek, Nebraska): An upstream value‑chain play focused on integrated processing; projects that link critical mineral extraction to downstream compound production change the supply equation for U.S. OEMs when they come online.
- American Elements (Santa Clara), Materion (Ohio), Edgetech Industries (Florida), Ottokemi (India): These firms represent differentiated supply models — from broad purity ranges and ultra‑fine powders to commodity, high‑melting‑point NbC powders and export‑oriented production. They collectively highlight the range of options buyers can pursue, from bespoke high‑value grades to cost‑focused commodities.
What the full PW Consulting report contains (actionable, practitioner‑oriented)
- Bottom‑up market sizing and a transparent forecasting model (2026–2032) calibrated to both macro demand signals and technical diffusion curves for key applications. The report provides downloadable model inputs for scenario stress‑testing.
- Value‑chain mapping: feedstock flows (niobium oxide), conversion routes, typical yield/loss factors, and cost drivers at each conversion step that define margin pools.
- Regulatory matrix: jurisdictional compliance requirements (including defense classification, export controls, and chemical registration) mapped to supplier and buyer obligations, with pragmatic timelines for certification and audit readiness.
- Supplier diligence playbook: a templated RFP and technical qualification checklist for NbC sourcing across purity grades and forms, plus recommended contract clauses for supply continuity and quality guarantees.
- Competitive intelligence: structured profiles of incumbent and challenger suppliers, recent product launches, capacity developments, and a short‑list of likely M&A targets by strategic archetype.
- Demand segmentation and pricing set: while the report documents market splits across regions, purity grades, forms and applications, granular segment tables and price decks are available in the subscriber download to support commercial negotiations and internal forecasting.
- Strategic roadmaps and investment cases: prioritized options for defensive and offensive moves — from long‑lead strategic partnerships and JV structures to small‑scale pilot investments in recycling and purification.
Practical recommendations for 2026 decision cycles
The following actions are prioritized for executives who must translate market insight into decisions in 2026:
- Supply security first: Initiate or expand multi‑year offtake agreements with at least two technically qualified suppliers, and where feasible, secure a clause for preferential allocation during supply tightness. For defense/aerospace OEMs, prioritize domestically compliant sources taking into account ITAR and critical‑mineral incentives.
- Qualify alternatives: Fast‑track technical audits of non‑traditional suppliers that can meet purity and grain specifications; use short trials to create contingency pools without committing to full contracts.
- Invest in certification: Allocate budget to achieve any required registrations or export/defense certifications (TSCA, ITAR readiness, and jurisdictional export compliance) to avoid losing competitive deals to certified incumbents.
- Product & margin playbook: Differentiate on material performance (tailored purity grades, controlled grain size) rather than commodity pricing alone — price realization is strongest where performance is mission‑critical (aerospace, defense, advanced coatings).
- R&D and vertical options: Consider capex for downstream processing steps (purification, carburation control, sputtering target fabrication) or near‑term partnerships with upstream projects that offer feedstock security and cost advantage.
- M&A & partnerships: Target bolt‑on acquisitions that provide certified capacity or specialty grades rather than broad, low‑quality volume plays. Smaller strategic acquisitions can de‑risk supply and accelerate route‑to‑market for premium products.
- Scenario planning & pricing governance: Implement a periodic scenario review (quarterly) with triggers tied to feedstock price moves, regulatory changes, and capacity announcements to adjust procurement, pricing, and inventory policies.
Closing: how PW Consulting helps you act on this insight
This preview highlights the levers that will matter most in 2026: supply security, regulatory compliance, technical differentiation and selective vertical integration. Our full Niobium Carbide Market report contains the complete dataset, downloadable forecasting model, supplier scorecards, and negotiation templates needed to convert these strategic priorities into executable plans.
For decision‑grade access to the full report — including the detailed segment tables, price decks, and model inputs referenced above — visit PW Consulting’s Niobium Carbide Market research page or contact your PW Consulting account lead. The full deliverable is designed to support procurement RFQ readiness, product development prioritization, and M&A screening exercises for the 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Niobium Carbide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Bus Market to grow at 14.2% CAGR to USD 51.21M by 2032
By pmarketresearch, 2026-07-23
Electric Bus Market 2026: Strategic Imperatives for Executive Decision-Making
As cities and transit authorities accelerate the transition to zero-emission mobility, corporate leaders face a compressed window to translate regulatory momentum, falling battery costs and evolving fleet economics into durable competitive advantage. PW Consulting’s new Electric Bus Market study — built on a 2025 base year, a 2020–2025 historical series and a 2026–2032 forecast horizon — quantifies that transition and converts it into actionable guidance. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 14.2% through the forecast period; in plain terms, market scale more than doubles from the mid‑2020s to the early 2030s under even conservative assumptions. For decision‑makers planning 2026 budgets, capex authorizations and strategic partnerships, this report is designed to be the playbook that connects policy, procurement and profitable execution.
Electric Bus Market
Why this matters in 2026
-
Regulatory inflection points are tightening procurement timelines. The European Union’s Fit for 55 package and intensified national incentive programs are creating concrete windows for fleet electrification decisions; delays materially increase the risk of missing grant and rebate cycles.
Electric Bus Market -
Technology and cost inflections are reshaping fleet economics. Global battery pack prices have moved to new lows (with industry reporting a meaningful step down in average pack costs by late 2024), and available BEB ranges have improved substantially — changing depot charging strategies and total cost of ownership (TCO) calculations across urban and regional services.
Electric Bus Market -
Competition is consolidating around scale, service networks and integrated charging solutions. A relatively concentrated set of OEMs and drivetrain suppliers now determines delivery lead times, warranty frameworks and the aftermarket experience for fleets worldwide.
What the report delivers — practical, transaction‑ready intelligence
-
Market sizing and a transparent forecast model (2026–2032) that you can stress‑test with alternative policy, battery price and financing scenarios.
-
Fleet procurement playbooks: procurement timelines, specification templates, risk allocation clauses, and charging‑infrastructure procurement phasing options to align capital and grid readiness.
-
Commercial and financial models: TCO templates including energy, maintenance, battery replacement and residual value assumptions; scenario outputs tied to financing structures and grant capture scenarios.
-
Supply‑chain and raw‑material risk assessments, with sensitivities to battery-pack price variance and lead‑time disruptions.
-
Competitive landscapes and supplier scorecards: assessment of OEMs, drive‑train providers, charging‑system vendors and fleet integrators to support sourcing and partnership decisions.
-
Operational readiness diagnostics: depot conversion sequences, grid interface options (smart‑charging, V2G readiness), and workforce upskilling roadmaps.
-
Investment and M&A filters for private equity and strategic buyers, including greenfield manufacturing location analysis and capex payback windows under multiple demand scenarios.
Competitive landscape — who matters and why
The market leaders sit at the intersection of manufacturing scale, breadth of product portfolio and aftermarket capability. Global OEMs with established bus platforms, integrated battery or driveline partnerships, and international service networks are best positioned to win large municipal and regional tenders. At the same time, specialized manufacturers with strong regional footprints and those that offer proprietary battery or charging solutions are carving defensible niches.
-
BYD: A high‑volume global manufacturer with a broad lineup of battery-electric models and an expanding international footprint — a primary counterparty for large public tenders and cross-border export programs.
-
Volvo Buses: Focused on zero‑emission technologies and higher‑range models; strong in markets where brand reputation and whole‑life performance are procurement priorities.
-
Daimler Truck / Mercedes‑Benz: Brings integrated vehicle systems and extensive OEM service capabilities, important for operators seeking long warranties and standardized fleet operations.
-
Solaris, New Flyer, Yutong, Zhongtong: Regional and global players offering a mix of tailored specifications, local manufacturing and export scale — essential suppliers where delivery timing and local content matter.
-
Proterra, Gillig, Blue Bird: North American‑centric companies that combine drivetrain and battery expertise with deep relationships across transit and school bus procurement channels.
Recent market activity through mid‑2026 reinforces strategic themes we highlight in the study: localized order flows and facility investments, modular drivetrain launches from system suppliers, and targeted working capital measures to support delivery obligations. These developments underscore that winners will be those who can simultaneously manage orderbook execution, capital efficiency and rapid product iteration.
Key dynamics shaping the next 12–36 months
-
Policy incentives and grant programs remain a primary accelerant. Large public rebate programs and targeted grants for school and transit fleets materially lower the short‑term payback hurdle for electrification and create concentrated demand windows that suppliers must be ready to serve.
-
Battery economics and performance improvements are reconfiguring depot and route planning. Real‑world range improvements and lower pack prices reduce the need for extreme on‑route charging in many use cases, enabling depot‑centred charging architectures for a larger share of services.
-
Modular electrified drivetrains and scalable charging platforms are shifting competitive advantage towards firms that can deliver systems, not just vehicles.
-
Procurement complexity will increase as fleets require integrated contracts that blend vehicles, chargers, energy management, financing and performance guarantees.
Strategic imperatives for 2026 — a five‑point checklist
-
Lock in phased procurement aligned to grant cycles: Time tenders and capital approvals to capture incentives, while building contingency for longer lead times.
-
Prioritize depot electrification and grid partnerships: Invest early in grid assessments and smart‑charging pilots to reduce operating risk and manage peak demand charges.
-
Hedge battery & supply‑chain exposure: Use multi‑sourcing, indexed contract terms and inventory strategies to mitigate pack price volatility and component shortages.
-
Design contracts for whole‑life outcomes: Move from vehicle purchase to performance‑based contracting that aligns OEM incentives with uptime, energy efficiency and residual value protection.
-
Align R&D and product roadmaps to operational realities: Emphasize durability, battery lifecycle services and digital fleet management — areas where premium pricing and recurring revenue models converge.
How PW Consulting’s study supports boardroom decisions
Executives need concise, defensible inputs when approving multi‑year capital and procurement plans. Our study provides that input in three ways: validated quantitative forecasts (with scenario and sensitivity variants), transaction‑level playbooks (from tender design to acceptance and warranty execution), and supplier due‑diligence that’s focused on execution risk rather than marketing claims. The report’s forecast — anchored on a 2025 base and extended through 2032 at a 14.2% CAGR under PW’s central scenario — is complemented by upside and downside cases for policy, battery price and macroeconomic shocks so that boards can visualize risk‑adjusted returns before committing capital.
What we are intentionally not publishing here
This preview deliberately omits the granular segmentation tables and the proprietary supplier share calculations that are included in the full report. Those elements — regional and application splits, exact market shares and detailed contract benchmarking — are the core, gated assets in our research offering and are essential for procurement-level decisioning. If your 2026 planning requires line‑item procurement timelines, detailed supplier cost curves or the full interactive forecast workbook, PW Consulting offers direct access to the complete dataset and tailored briefings.
Next steps
For executives leading procurement, infrastructure planning, or corporate strategy, the window to act is now. PW Consulting can provide an executive briefing to map the report’s insights to your specific operating regions, fleet composition and balance‑sheet constraints. Reach out to schedule a tailored walkthrough of the forecast model, scenario outputs and procurement playbooks — so your 2026 decisions are informed, defensible and execution‑ready.
For detailed analysis of this topic, please visit the official page: Electric Bus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Body Composition Analyzers Market to Reach USD 847.35M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-23
Body Composition Analyzers Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, high‑signal briefing on the Body Composition Analyzers market that frames the strategic decisions organizations must take in 2026. This preview synthesizes our latest research — built on a 2025 base year, five years of historical tracking, and a forward forecast through 2032 — to clarify where value is forming, what risk vectors to mitigate, and which capabilities will differentiate winners. Think of this as a trailer: it demonstrates our analytical depth and the practical frameworks you need, while intentionally reserving the granular splits and proprietary scorecards for the full report.
Body Composition Analyzers Market
Market snapshot: the macro trajectory
The market for body composition analyzers has moved beyond niche clinical instrumentation to a multi‑channel industry serving hospitals, diagnostics labs, sports medicine, fitness/wellness centers, research institutions, and home users. Our base year assessment (2025) places the global market at approximately USD 536 million. From a recovery and growth phase that began in the early 2020s, the market is projected to expand at a compound annual growth rate (CAGR) of roughly 6.98% during the 2026–2032 forecast window, reaching an estimated market scale in the high‑800 million USD range by 2032.
Body Composition Analyzers Market
Two observations arise from these macro numbers: first, the sector presents steady, mid‑single‑digit expansion that favors long‑term capability investments (clinical validation, connectivity, service footprint). Second, growth is uneven by channel and technology — a dynamic that creates both pockets of rapid monetization and areas where incumbents are vulnerable to disruption.
Body Composition Analyzers Market
Why this research matters for 2026 strategic choices
-
Investment prioritization: With constrained capital budgets across healthcare and wellness organizations, leaders need a clear line of sight on which product types and go‑to‑market approaches produce durable returns. Our study translates macro growth into actionable priority areas for R&D, M&A, and sales deployment.
-
Procurement clarity for providers: Hospitals and clinics increasingly demand device reproducibility, regulatory provenance, interoperability with electronic records, and lifecycle service guarantees. Our frameworks enable procurement teams to evaluate devices not just on up‑front cost but on total cost of ownership and clinical utility.
-
Channel & business model design for vendors: As adoption shifts across clinical, fitness, research, and home settings, vendors must refine pricing, subscription, and partnership models to capture adjacent revenue streams (software analytics, managed services, consumables).
-
Regulatory and reimbursement positioning: Device approval status and code‑based reimbursement remain leading determinants of commercial traction. We map regulatory events and reimbursement levers against commercialization timelines so executives can sequence trials and market entries for maximal impact.
What the full report delivers (practical, operational content)
-
Robust market sizing and validated forecasts (2020–2032) with scenario analysis that isolates base‑case, upside, and downside outcomes — each accompanied by sensitivity drivers and break‑even timelines for new product introductions.
-
Granular segmentation by region, product type (e.g., bioimpedance analyzers, DXA systems, skinfold calipers, and others), and application channel (clinical/diagnostic, fitness/wellness, research/academic, home). The public preview omits the granular numeric splits; the report contains those tables and underlying model files for licensed users.
-
Competitive benchmarking with vendor scorecards — assessing product portfolio breadth, regulatory clearances, clinical evidence base, service network density, software ecosystems, and channel partnerships.
-
Go‑to‑market playbooks for manufacturers and distributors that include pricing band analysis, channel margin models, and 12‑ to 36‑month roll‑out calendars aligned to regulatory gates and reimbursement timing.
-
A regulatory and reimbursement playbook mapping device classifications, notable approvals, and payer coding opportunities with step‑by‑step recommendations for obtaining clinical acceptance and reimbursement coverage.
-
Acquisition and partnership target lists with rationale, valuation heuristics, and integration risks — oriented to both strategic acquirers and financial investors.
Competitive landscape: the players you must evaluate
The market exhibits moderate concentration, with the top three vendors representing a meaningful share and the top five increasing that concentration further. This structure produces a dual dynamic: dominant players can leverage scale to invest in clinical trials and global service, while midsize specialists can outmaneuver incumbents through niche clinical positioning and rapid product iteration.
-
Tanita Corporation (Itabashi‑ku, Tokyo) — A recognized name for FDA‑cleared, professional multi‑frequency BIA segmental analyzers targeted at clinical and fitness users. Tanita’s strength is regulatory equity combined with broad clinician recognition.
-
InBody Co., Ltd. (Seoul) — Noted for a range of professional BIA analyzers with strong reproducibility and a deep presence in hospitals and sports organizations. InBody’s repeatability and clinical adoption are key purchase drivers.
-
Hologic, Inc. (Marlborough, Massachusetts) — A leader in DXA‑based whole‑body composition and bone density systems, Hologic’s Horizon DXA is a standard in many clinical settings where high precision is required.
-
OMRON Corporation (Kyoto) — Focused on Bluetooth‑enabled body composition monitors that bridge consumer wellness and clinical applications; OMRON’s distribution footprint in retail and home markets is a competitive advantage.
-
Seca GmbH & Co. KG (Hamburg) — Known for its medical BIA mBCA series, Seca combines precision hardware with integrated anthropometry tools targeted to hospitals and clinics.
-
Bodystat Ltd. (Isle of Man) — A specialist in portable BIS/BIA analyzers, Bodystat competes on device portability and speed of measurement for both medical and fitness use cases.
-
RJL Systems, Inc. (Clinton Township, Michigan) — Offers clinically validated BIA instrumentation, with a focus on whole‑body and segmental analysis and a legacy in clinical research settings.
Our full profiles identify each vendor’s technical differentiators, regulatory pathway status, service footprint, and commercial strengths — enabling competitive response and partnership evaluation. The report also contains a vendor matrix linking feature‑sets to application scenarios and procurement checklists.
Regulatory & reimbursement developments shaping 2026 actions
-
Regulatory density: Our analysts track hundreds of registered devices and active clearances in the U.S. alone. As of our latest review, over 400 body composition devices are registered with the U.S. FDA — a signal of both market maturity and ongoing regulatory activity.
-
Reimbursement levers: CPT code availability for whole‑body bioelectrical impedance assessment remains a material commercial enabler for clinical adoption; organizations that align clinical studies and coding submissions can accelerate hospital uptake.
-
Recent approvals: Clinical trust is reinforced by new clearances and conformity markings. Examples include notified clearances and CE approvals for leading systems — each of which shortens sales cycles in regulated markets and influences procurement decisions.
Strategic recommendations for 2026 (executive checklist)
-
For manufacturers: Prioritize clinical validation and regulatory sequencing in target geographies. Invest in interoperable software and cloud analytics to convert device sales into recurring revenue streams. Consider selective partnerships with electronic health record vendors to embed body composition outputs into care pathways.
-
For healthcare providers: Evaluate devices on reproducibility and integration, not just sticker price. Adopt a lifecycle procurement approach that includes warranty, calibration, and training. Leverage reimbursement codes with evidence‑based protocols to offset acquisition costs.
-
For investors and M&A teams: Target companies with proprietary clinical datasets, regulatory approvals in place, and differentiated software platforms. Expect consolidation among device manufacturers as scale becomes critical for global service and clinical trial support.
-
For fitness and consumer wellness operators: Focus on continuity of care — devices that feed longitudinal analytics and enable coaching monetization outperform stand‑alone hardware in retention and ARPU metrics.
How to use this preview
This preview demonstrates the strategic lenses we apply: rigorous market sizing, vendor benchmarking, regulatory mapping, and executable go‑to‑market playbooks. If your team needs to underwrite a product launch, prioritize an acquisition, or restructure sales and service territories for 2026, the full PW Consulting Body Composition Analyzers report provides the models, vendor scorecards, and step‑by‑step implementation tools required to convert insight into measurable outcomes.
To preserve the value of the work for our clients, we have intentionally withheld the granular regional and application numeric splits, the full vendor share table, and the downloadable financial model from this public preview. These deliverables are included in the licensed report and are designed to plug directly into corporate planning workflows.
Next steps
-
Request the full report to obtain the detailed segmentation tables, interactive forecast model, and vendor scorecards.
-
Book a briefing with our advisory team to align the report findings to your 2026 planning cycle and to receive a tailored action plan for product, market, or investment initiatives.
PW Consulting’s Body Composition Analyzers research equips executives with the analytical clarity and operational tools necessary to make confident, high‑impact decisions in 2026. For organizations seeking to move from observation to execution, the full report is where the roadmap and the implementation templates live.
For detailed analysis of this topic, please visit the official page: Body Composition Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dental Autoclave Market to Reach USD 399.1M by 2032 at 3.69% CAGR - PW Consulting
By pmarketresearch, 2026-07-23
Dental Autoclave Market — Strategic Imperatives for 2026
Executive preview
As PW Consulting’s lead industry analyst, I present a concise strategic briefing that distills the most consequential trends, competitive moves, and regulatory inflection points shaping the global dental autoclave market as companies set priorities for 2026. This briefing is a “trailer” — designed to demonstrate the analytical depth and operational relevance of our full market study while intentionally withholding detailed sub‑segment tables and granular regional splits. Those proprietary breakouts and supplier scorecards are available in the full PW Consulting report.
Dental Autoclave Market
Market snapshot: what the numbers tell us
The dental autoclave market has shown steady expansion through the first half of the decade, rising from a mid‑two‑hundreds base (USD Million) in 2020 to an estimated USD 309.0 Million in the base year 2025. Our forecast through 2032 sees continued modest growth, driven by regulatory tightening, replacement cycles, and uptake of higher‑value automated and digitally integrated systems: the market is projected to reach approximately USD 399.1 Million by 2032, reflecting a compound annual growth rate (CAGR) of ~3.7% over the forecast horizon.
Dental Autoclave Market
Interpreting these macro figures matters for near‑term capital allocation: growth is positive but not explosive. Vendors, investors, and channel partners must therefore prioritize margin expansion, lifecycle revenues, and regulatory differentiation rather than banking on rapid top‑line scale alone.
Dental Autoclave Market
Regulatory and clinical dynamics — the accelerants
- New baseline for validation and traceability: Regulatory actions recognized in 2024–2026 have raised the bar for documented cycle validation and end‑to‑end traceability. Notable steps include formal recognition of international sterilization standards and Quality Management System updates that emphasize traceability across device lifecycles. These changes transform sterilizers from “utility” equipment into regulated clinical assets that must support auditable, digital records.
- Operational audits are changing purchase criteria: Infection control audits and field surveillance (including published findings of inconsistent spore test results in dental practices) have created demand for automated verification, user‑independent cycles, and auto‑reporting features. Buyers increasingly value equipment that demonstrably reduces operator variability in sterilization outcomes.
- Harmonization nudges product convergence: European and international standard updates are aligning expectations for small steam sterilizers used in outpatient settings, compressing acceptable performance bands and accelerating adoption of features once reserved for hospital‑grade units.
Technology and product trends — where the value is migrating
- Digital traceability and cloud services: Smart cycle logging, cloud dashboards, and remote alerts have shifted from “nice to have” to procurement considerations. Recent product introductions emphasize cloud integration and remote predictive service, enabling vendors to monetize data and improve uptime.
- Automation meets energy/water efficiency: Innovations combine faster validated cycles with sustainable utility consumption; lifecycle operating cost is becoming a primary differentiator for institutional buyers and multi‑site groups.
- Segment blurring: The functional gap between tabletop and higher‑capacity systems is narrowing as manufacturers incorporate pre/post vacuum cycles, closed‑door drying, and modular scaling options into smaller footprints.
Competitive landscape — tactical read for 2026
Market concentration is moderate: the top three players collectively represent roughly one third of the market, and the top five account for under two‑fifths. This structure creates room for focused differentiation and for nimble challengers to capture share through innovation, superior service models, or targeted channel strategies.
- Tuttnauer (Yavne, Israel): Strengths lie in robust tabletop and bench‑top offerings with B‑class cycles and flexible fill/service options. Their continual upgrades to cycle versatility and sterilization tracking make them a go‑to for clinics prioritizing operator convenience and validated processes.
- MELAG (Stutensee, Germany): Known for fully automated, higher‑capacity sterilizers and an explicit focus on energy/water efficiency and digital monitoring. Their positioning appeals to multi‑chair practices and groups that value sustainability and centralized instrument processing.
- Dentsply Sirona (Charlotte, NC, USA): Integration into instrument workflow and compatibility with broader dental equipment ecosystems give them an advantage when buyers seek vendor consolidation and integrated sterilization workflows.
- Dürr Dental and W&H Dentalwerk (Germany & Austria): Both emphasize reliability and digital integration; W&H’s cloud push and Dürr’s high‑volume tabletop designs target high‑throughput practices and networks.
- Flight Dental Systems, Mocom, Tomy Seiko, Hirayama, Kenz, Eschmann, Biobase: These players form a diverse competitive set — from high‑capacity steam sterilizers and cloud‑enabled bench‑tops to cost‑effective basic units. Recent product launches (e.g., Flight’s large‑capacity Clave45+, W&H’s Lina Smart Edition, Mocom’s cloud‑enabled B Classic+, and Tuttnauer’s Elara11) underscore a race to combine throughput, automation, and connectivity.
Implications for strategic action in 2026
For boards, product leaders, and business development teams preparing 2026 plans, the following strategic imperatives should guide allocation of capital and management attention:
- Prioritize regulated feature sets: Design and certify products to deliver audit‑ready cycle validation and traceability. Compliance is a market entry requirement in many institutional channels and a de facto premium feature for multi‑site groups.
- Monetize services and software: Build subscription models for cloud logs, predictive maintenance, and compliance reporting. Aftermarket revenue will increasingly offset the modest pace of hardware growth.
- Elevate lifecycle cost messaging: Sales playbooks must quantify water, energy, maintenance, and management time savings, not just purchase price or cycle time. Demonstrated TCO advantages shorten procurement cycles in budget‑constrained buyers.
- Target channel segmentation: Differentiate offerings for solo clinics, group practices, and dental laboratories. A single SKU strategy is less effective than modular platforms that allow upsell to automation and cloud capabilities.
- Invest selectively in capacity and supply resilience: The market’s steady growth does not warrant aggressive global capacity builds, but distributors and vendors should shore up critical components and service parts availability to protect uptime promises.
- Consider M&A for capability gaps: Bolt‑on acquisitions that bring digital traceability, LIMS interoperability, or service network scale can be more value‑accretive than greenfield R&D given compressed organic growth.
- Embed validation support in go‑to‑market: Offer validation packages, spore test management, and on‑site commissioning as part of procurement to reduce buyer risk and increase switching costs.
What PW Consulting’s full report delivers
The complete Dental Autoclave Market study is designed to convert these strategic directions into executable plans. Key practical deliverables include:
- Multi‑year market model (historical 2020–2025 base; forecast 2026–2032) with scenario stress tests aligned to regulatory timelines.
- Segment and regional demand matrices (proprietary splits and growth levers) — note: these granular cells are intentionally omitted from this preview and provided only in the full report.
- Competitive scorecards and product benchmarking across performance, digital features, service ecosystem, and lifecycle cost.
- Commercial playbooks for vendors and distributors: pricing elasticity tests, channel economics, and buyer persona playbooks for clinics, hospitals, and lab customers.
- Regulatory readiness checklist and validation templates aligned to the latest standardizations and Quality Management System updates.
- M&A target shortlist methodology and diligence templates focused on software, maintenance platforms, and capacity optimization.
- Implementation roadmaps for moving from product sales to recurring revenue through SaaS and managed services for traceability and compliance.
Why this matters for 2026 decision cycles
With the market growing at a steady mid‑single digit CAGR and regulatory timelines compressing validation requirements, 2026 is a pivot year for firms that have delayed investments in digital traceability and service operations. The window to differentiate on compliance and lifecycle economics is narrow: buyers will favor equipment that reduces audit risk and provides verifiable clinical outcomes. Firms that move early to operationalize data, demonstrate compliance, and package lifecycle services will win higher margins and deeper customer relationships.
Next steps
If your 2026 planning must reconcile constrained capital with the need to meet new regulatory and buyer expectations, PW Consulting’s full report supplies the detailed segmentation, supplier scorecards, and scenario models to inform board‑level decisions. For access to the proprietary breakouts, actionable templates, and our vendor diligence annex, please refer to the full Dental Autoclave Market study on our website.
PW Consulting — we translate market data into strategic action. Contact our advisory desk to schedule a briefing tailored to your strategic priorities.
For detailed analysis of this topic, please visit the official page: Dental Autoclave Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com