

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Niobium Carbide Market to Reach USD 62.43M in 2026, 5.1% CAGR — PW Consulting

Niobium Carbide Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our forthcoming Niobium Carbide Market study. This briefing translates rigorous market modelling into clear implications for executives preparing for 2026 — showing where value and risk are concentrated, how competitive dynamics are reshaping supplier choice, and which regulatory and feedstock trends will determine margin capture. The purpose here is to demonstrate the report’s evidence‑based depth while deliberately reserving granular segment tables and proprietary model outputs for the full report.
Niobium Carbide Market
Market snapshot (what the numbers tell us)
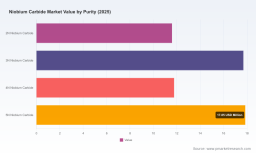
Using 2025 as the base year and a historical window covering 2020–2025, our model quantifies a steady expansion of the Niobium Carbide market. The market recorded low‑double‑digit growth between 2020 and 2025 and, based on our forecast envelope for 2026–2032, follows a compound annual growth rate (CAGR) of approximately 5.1% (USD, revenue unit: Million). In concrete terms: the industry moves from a mid‑tens‑of‑millions USD footprint in the early 2020s to a materially larger, high‑tens to low‑hundreds million USD opportunity by the early 2030s under a central case. These macro metrics validate continued commercial relevance — but they also mask diverging dynamics within purity grades, forms, and end‑use channels that will drive winner‑take‑most economics in pockets of the value chain.
Niobium Carbide Market
Why this matters for 2026 planning
- Budgeting and CapEx: A predictable, mid‑single‑digit CAGR allows capital planners to prioritize modular capacity expansions over large, lumpy greenfield investments, unless pursuing vertical integration or domestic feedstock security.
- Supply risk & sourcing: Regulatory shifts and critical‑mineral policies are raising the value of near‑term supplier certainty — firms should re‑evaluate sourcing strategy and contract tenure now, not later.
- Product strategy: Performance differentiation increasingly stems from material purity, grain size control and form (powder vs. target vs. flakes). R&D and quality assurance investments yield disproportionate returns in aerospace, defense and advanced coatings segments.
Key demand and supply dynamics
Drivers: Niobium Carbide’s demand profile is anchored in industrial tooling, advanced coatings, cermet and aerospace applications. Technical trends — such as finer grain hardmetals for higher cutting speeds, sputtering targets for electronic thin films, and tailored purity grades for defense/aerospace — are elevating the price‑per‑unit opportunity for premium NbC products.
Niobium Carbide Market
Feedstock & cost structure: Niobium oxide remains the primary feedstock for NbC production. Fluctuations in oxide availability and upstream niobium pricing transmit directly to downstream margins. Manufacturers with secured oxide streams, integrated processing, or recycling pathways gain both margin stability and commercial optionality.
Regulatory & policy environment: Governments are increasingly treating niobium as a strategic input. Recent designations and export controls in key jurisdictions introduce non‑price barriers and create localized demand for domestically compliant supplies. Additionally, chemical registration regimes require manufacturers to maintain product registrations and compliance dossiers — a nontrivial fixed cost that favors established suppliers.
Regulatory signals executives cannot ignore
- Critical mineral status and defense funding are accelerating domestic exploration and processing programs in the United States — an important factor for firms considering onshore partners or greenfield projects.
- Export control listings in certain countries increase transaction friction for strategic applications and encourage sourcing diversification.
- ITAR (for defense/aerospace applications) and TSCA (for U.S. chemical registration) create compliance hurdles that impact time‑to‑market and supplier eligibility; firms must budget for certification and audit cycles when qualifying suppliers.
Competitive landscape — what the incumbents signal
The market exhibits moderate concentration at the top: the three‑firm and five‑firm concentration ratios indicate that a small group of vendors account for a meaningful portion of global supply, while a long tail of specialist and regional suppliers addresses niche requirements. That structure produces four strategic implications: pricing power for high‑quality producers, opportunity for niche entrants that can match technical specs, M&A utility for buyers seeking scale, and supplier risk for large OEMs dependent on a limited number of certified sources.
Profiles of strategic players (select observations):
- H.C. Starck Tungsten Powders (Goslar, Germany): A technical leader in high‑purity NbC and mixed Ta/Nb carbides with finely controlled grain sizes. Their product positioning is oriented toward cutting tools and grain‑growth control applications — making them a natural partner for hardmetals manufacturers seeking performance consistency.
- CBMM (Araxá, Brazil): A primary producer with recent product innovation; the company’s 2025 launch of a new high‑purity NbC grade underscores its intent to serve aerospace and defense segments where material traceability and purity command premium pricing.
- China Molybdenum Co., Ltd. (Beijing): Offers NbC tailored to electronics and high‑performance end‑uses — a strategic foothold given the scale of regional electronics manufacturing and localized supply chains.
- NioCorp Developments (Elk Creek, Nebraska): An upstream value‑chain play focused on integrated processing; projects that link critical mineral extraction to downstream compound production change the supply equation for U.S. OEMs when they come online.
- American Elements (Santa Clara), Materion (Ohio), Edgetech Industries (Florida), Ottokemi (India): These firms represent differentiated supply models — from broad purity ranges and ultra‑fine powders to commodity, high‑melting‑point NbC powders and export‑oriented production. They collectively highlight the range of options buyers can pursue, from bespoke high‑value grades to cost‑focused commodities.
What the full PW Consulting report contains (actionable, practitioner‑oriented)
- Bottom‑up market sizing and a transparent forecasting model (2026–2032) calibrated to both macro demand signals and technical diffusion curves for key applications. The report provides downloadable model inputs for scenario stress‑testing.
- Value‑chain mapping: feedstock flows (niobium oxide), conversion routes, typical yield/loss factors, and cost drivers at each conversion step that define margin pools.
- Regulatory matrix: jurisdictional compliance requirements (including defense classification, export controls, and chemical registration) mapped to supplier and buyer obligations, with pragmatic timelines for certification and audit readiness.
- Supplier diligence playbook: a templated RFP and technical qualification checklist for NbC sourcing across purity grades and forms, plus recommended contract clauses for supply continuity and quality guarantees.
- Competitive intelligence: structured profiles of incumbent and challenger suppliers, recent product launches, capacity developments, and a short‑list of likely M&A targets by strategic archetype.
- Demand segmentation and pricing set: while the report documents market splits across regions, purity grades, forms and applications, granular segment tables and price decks are available in the subscriber download to support commercial negotiations and internal forecasting.
- Strategic roadmaps and investment cases: prioritized options for defensive and offensive moves — from long‑lead strategic partnerships and JV structures to small‑scale pilot investments in recycling and purification.
Practical recommendations for 2026 decision cycles
The following actions are prioritized for executives who must translate market insight into decisions in 2026:
- Supply security first: Initiate or expand multi‑year offtake agreements with at least two technically qualified suppliers, and where feasible, secure a clause for preferential allocation during supply tightness. For defense/aerospace OEMs, prioritize domestically compliant sources taking into account ITAR and critical‑mineral incentives.
- Qualify alternatives: Fast‑track technical audits of non‑traditional suppliers that can meet purity and grain specifications; use short trials to create contingency pools without committing to full contracts.
- Invest in certification: Allocate budget to achieve any required registrations or export/defense certifications (TSCA, ITAR readiness, and jurisdictional export compliance) to avoid losing competitive deals to certified incumbents.
- Product & margin playbook: Differentiate on material performance (tailored purity grades, controlled grain size) rather than commodity pricing alone — price realization is strongest where performance is mission‑critical (aerospace, defense, advanced coatings).
- R&D and vertical options: Consider capex for downstream processing steps (purification, carburation control, sputtering target fabrication) or near‑term partnerships with upstream projects that offer feedstock security and cost advantage.
- M&A & partnerships: Target bolt‑on acquisitions that provide certified capacity or specialty grades rather than broad, low‑quality volume plays. Smaller strategic acquisitions can de‑risk supply and accelerate route‑to‑market for premium products.
- Scenario planning & pricing governance: Implement a periodic scenario review (quarterly) with triggers tied to feedstock price moves, regulatory changes, and capacity announcements to adjust procurement, pricing, and inventory policies.
Closing: how PW Consulting helps you act on this insight
This preview highlights the levers that will matter most in 2026: supply security, regulatory compliance, technical differentiation and selective vertical integration. Our full Niobium Carbide Market report contains the complete dataset, downloadable forecasting model, supplier scorecards, and negotiation templates needed to convert these strategic priorities into executable plans.
For decision‑grade access to the full report — including the detailed segment tables, price decks, and model inputs referenced above — visit PW Consulting’s Niobium Carbide Market research page or contact your PW Consulting account lead. The full deliverable is designed to support procurement RFQ readiness, product development prioritization, and M&A screening exercises for the 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Niobium Carbide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com