

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
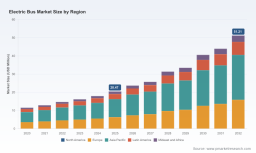
PW Consulting: Electric Bus Market to grow at 14.2% CAGR to USD 51.21M by 2032

Electric Bus Market 2026: Strategic Imperatives for Executive Decision-Making
As cities and transit authorities accelerate the transition to zero-emission mobility, corporate leaders face a compressed window to translate regulatory momentum, falling battery costs and evolving fleet economics into durable competitive advantage. PW Consulting’s new Electric Bus Market study — built on a 2025 base year, a 2020–2025 historical series and a 2026–2032 forecast horizon — quantifies that transition and converts it into actionable guidance. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 14.2% through the forecast period; in plain terms, market scale more than doubles from the mid‑2020s to the early 2030s under even conservative assumptions. For decision‑makers planning 2026 budgets, capex authorizations and strategic partnerships, this report is designed to be the playbook that connects policy, procurement and profitable execution.
Electric Bus Market
Why this matters in 2026
-
Regulatory inflection points are tightening procurement timelines. The European Union’s Fit for 55 package and intensified national incentive programs are creating concrete windows for fleet electrification decisions; delays materially increase the risk of missing grant and rebate cycles.
Electric Bus Market -
Technology and cost inflections are reshaping fleet economics. Global battery pack prices have moved to new lows (with industry reporting a meaningful step down in average pack costs by late 2024), and available BEB ranges have improved substantially — changing depot charging strategies and total cost of ownership (TCO) calculations across urban and regional services.
Electric Bus Market -
Competition is consolidating around scale, service networks and integrated charging solutions. A relatively concentrated set of OEMs and drivetrain suppliers now determines delivery lead times, warranty frameworks and the aftermarket experience for fleets worldwide.
What the report delivers — practical, transaction‑ready intelligence
-
Market sizing and a transparent forecast model (2026–2032) that you can stress‑test with alternative policy, battery price and financing scenarios.
-
Fleet procurement playbooks: procurement timelines, specification templates, risk allocation clauses, and charging‑infrastructure procurement phasing options to align capital and grid readiness.
-
Commercial and financial models: TCO templates including energy, maintenance, battery replacement and residual value assumptions; scenario outputs tied to financing structures and grant capture scenarios.
-
Supply‑chain and raw‑material risk assessments, with sensitivities to battery-pack price variance and lead‑time disruptions.
-
Competitive landscapes and supplier scorecards: assessment of OEMs, drive‑train providers, charging‑system vendors and fleet integrators to support sourcing and partnership decisions.
-
Operational readiness diagnostics: depot conversion sequences, grid interface options (smart‑charging, V2G readiness), and workforce upskilling roadmaps.
-
Investment and M&A filters for private equity and strategic buyers, including greenfield manufacturing location analysis and capex payback windows under multiple demand scenarios.
Competitive landscape — who matters and why
The market leaders sit at the intersection of manufacturing scale, breadth of product portfolio and aftermarket capability. Global OEMs with established bus platforms, integrated battery or driveline partnerships, and international service networks are best positioned to win large municipal and regional tenders. At the same time, specialized manufacturers with strong regional footprints and those that offer proprietary battery or charging solutions are carving defensible niches.
-
BYD: A high‑volume global manufacturer with a broad lineup of battery-electric models and an expanding international footprint — a primary counterparty for large public tenders and cross-border export programs.
-
Volvo Buses: Focused on zero‑emission technologies and higher‑range models; strong in markets where brand reputation and whole‑life performance are procurement priorities.
-
Daimler Truck / Mercedes‑Benz: Brings integrated vehicle systems and extensive OEM service capabilities, important for operators seeking long warranties and standardized fleet operations.
-
Solaris, New Flyer, Yutong, Zhongtong: Regional and global players offering a mix of tailored specifications, local manufacturing and export scale — essential suppliers where delivery timing and local content matter.
-
Proterra, Gillig, Blue Bird: North American‑centric companies that combine drivetrain and battery expertise with deep relationships across transit and school bus procurement channels.
Recent market activity through mid‑2026 reinforces strategic themes we highlight in the study: localized order flows and facility investments, modular drivetrain launches from system suppliers, and targeted working capital measures to support delivery obligations. These developments underscore that winners will be those who can simultaneously manage orderbook execution, capital efficiency and rapid product iteration.
Key dynamics shaping the next 12–36 months
-
Policy incentives and grant programs remain a primary accelerant. Large public rebate programs and targeted grants for school and transit fleets materially lower the short‑term payback hurdle for electrification and create concentrated demand windows that suppliers must be ready to serve.
-
Battery economics and performance improvements are reconfiguring depot and route planning. Real‑world range improvements and lower pack prices reduce the need for extreme on‑route charging in many use cases, enabling depot‑centred charging architectures for a larger share of services.
-
Modular electrified drivetrains and scalable charging platforms are shifting competitive advantage towards firms that can deliver systems, not just vehicles.
-
Procurement complexity will increase as fleets require integrated contracts that blend vehicles, chargers, energy management, financing and performance guarantees.
Strategic imperatives for 2026 — a five‑point checklist
-
Lock in phased procurement aligned to grant cycles: Time tenders and capital approvals to capture incentives, while building contingency for longer lead times.
-
Prioritize depot electrification and grid partnerships: Invest early in grid assessments and smart‑charging pilots to reduce operating risk and manage peak demand charges.
-
Hedge battery & supply‑chain exposure: Use multi‑sourcing, indexed contract terms and inventory strategies to mitigate pack price volatility and component shortages.
-
Design contracts for whole‑life outcomes: Move from vehicle purchase to performance‑based contracting that aligns OEM incentives with uptime, energy efficiency and residual value protection.
-
Align R&D and product roadmaps to operational realities: Emphasize durability, battery lifecycle services and digital fleet management — areas where premium pricing and recurring revenue models converge.
How PW Consulting’s study supports boardroom decisions
Executives need concise, defensible inputs when approving multi‑year capital and procurement plans. Our study provides that input in three ways: validated quantitative forecasts (with scenario and sensitivity variants), transaction‑level playbooks (from tender design to acceptance and warranty execution), and supplier due‑diligence that’s focused on execution risk rather than marketing claims. The report’s forecast — anchored on a 2025 base and extended through 2032 at a 14.2% CAGR under PW’s central scenario — is complemented by upside and downside cases for policy, battery price and macroeconomic shocks so that boards can visualize risk‑adjusted returns before committing capital.
What we are intentionally not publishing here
This preview deliberately omits the granular segmentation tables and the proprietary supplier share calculations that are included in the full report. Those elements — regional and application splits, exact market shares and detailed contract benchmarking — are the core, gated assets in our research offering and are essential for procurement-level decisioning. If your 2026 planning requires line‑item procurement timelines, detailed supplier cost curves or the full interactive forecast workbook, PW Consulting offers direct access to the complete dataset and tailored briefings.
Next steps
For executives leading procurement, infrastructure planning, or corporate strategy, the window to act is now. PW Consulting can provide an executive briefing to map the report’s insights to your specific operating regions, fleet composition and balance‑sheet constraints. Reach out to schedule a tailored walkthrough of the forecast model, scenario outputs and procurement playbooks — so your 2026 decisions are informed, defensible and execution‑ready.
For detailed analysis of this topic, please visit the official page: Electric Bus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com