

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Office Storage to Rise from USD 3.15B (2025) to USD 5.34B by 2032 at 7.9% CAGR

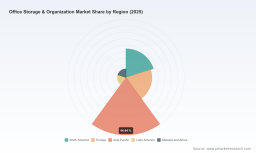
Office Storage & Organization Market 2026: Strategic Imperatives for Corporate Decision-Makers
As organizations recalibrate workplace strategies for a hybrid, cost-sensitive era, the Office Storage & Organization market has moved from a back-office procurement item to a strategic lever for productivity, space optimization and capital allocation. PW Consulting’s latest market study—anchored to a 2025 base year and projecting through 2032—maps that trajectory with rigorous scenario modeling: the global market reached approximately USD 3.15 Billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 7.9% over the coming cycle, finishing the forecast horizon materially larger by 2032. For executives planning capex, workplace redesigns, or supplier consolidation in 2026, the report translates these macro dynamics into actionable choices.
Office Storage & Organization Market
Why this research matters for 2026 decisions
-
Timing and scale: The sector’s near-term momentum and sustained mid-term growth mean procurement windows and roll-out schedules have different payoffs depending on whether organizations pursue rapid retrofit projects or phased modular investments. Our study quantifies the trade-offs and identifies inflection points where cost-of-delay exceeds the benefits of waiting for price normalization.
Office Storage & Organization Market -
Risk-adjusted sourcing: With raw-material and labor-cost volatility continuing to bite, buyers who align purchase timing, warranty terms and supplier risk-sharing structures will preserve margins. The research provides practical sourcing structures and contract templates tailored to present market stressors.
Office Storage & Organization Market -
Productivity ROI: Storage and organization decisions now influence real estate utilization, employee experience and records/compliance management. Our economic models tie storage choices to measurable productivity and space-savings outcomes, enabling finance teams to evaluate investments with enterprise-grade rigor.
Market snapshot — what the numbers tell us (high level)
After a resilient recovery in the early 2020s, demand for office storage and organizational solutions has resumed steady expansion. The market’s compound growth reflects several converging forces: continued investment in office modernization, a rise in remote/home-office needs that reshapes product mixes, and renewed spending in sectors prioritizing secure records and asset management. While macro headwinds—most notably cost pressures on inputs and labor—temper margin expansion for manufacturers and distributors, the net demand trajectory remains positive, offering multiple routes to capture value.
Report scope: practical outputs for operators and investors
PW Consulting’s study is designed to be a working tool for decision-makers, not just a reference. Key deliverables include:
- Market sizing and validated forecast models (2020–2032) with scenario sensitivity to input-cost, labor, and regulation shifts.
- Procurement playbooks for different buyer archetypes (corporate real estate teams, facilities managers, small-business consolidators), including RFP templates and supplier scorecards.
- Capex vs. Opex analysis for modular and high-density storage investments, with break-even horizons modeled under multiple occupancy scenarios.
- Compliance and safety checklists referencing current occupational-load and fire-resistance standards, with supplier certification matrices.
- Competitive benchmarking and vendor selection frameworks that map technology, scale, and channel strengths to buyer requirements.
- Implementation roadmaps and change-management guidance to ensure adoption and measurable productivity gains post-deployment.
Competitive landscape — strategic takeaways
The market exhibits a mix of specialized manufacturers, integrated furniture conglomerates, and retail/channel players. Rather than a winner-takes-all dynamic, the landscape favors companies that combine product innovation, distribution agility and services that remove total-cost-of-ownership friction.
-
Office Furniture EZ (Colorado Springs, USA) — A hybrid distributor with showroom and e-commerce capabilities. Their 2026 product catalog release signals a continued focus on omnichannel sales and curated solutions for small-to-mid enterprises. Strategic implication: competitors that lack an integrated online-to-showroom experience will struggle to match their conversion economics among SMB buyers.
-
SHUTER (Taiwan) — A manufacturer emphasizing innovation and durability in modern cabinets and organizational systems. Recent cataloging suggests an iterative product development cadence geared to export markets. Strategic implication: their engineering depth makes them a logical partner or acquisition target for regional distributors seeking differentiated product lines.
-
Livinbox (Taiwan) — Known for stylish, modular solutions for home and office environments; product showcases in global trade events underline a push into lifestyle-oriented office storage. Strategic implication: brands that bridge home-office aesthetics with enterprise standards can open new channel opportunities in corporate gifting, remote-work stipends and employee onboarding kits.
-
HNI Corporation (Muscadine, USA) — An incumbent with integrated workplace furniture and high-density storage capabilities. Their scale and integrated offerings position them well for large corporate and contract clients. Strategic implication: expect continued competition on bundled furniture + storage solutions, with price-pressure on standalone storage vendors.
-
Spacesaver Corporation (Fort Atkinson, USA) and Montel Inc. (Montreal, Canada) — Specialists in high-density and mobile storage systems. Their technical differentiation makes them preferred suppliers where space optimization and archival access are critical. Strategic implication: these players will dominate projects where space-per-staff economics are measured in single-digit percentages.
-
The Container Store (Dallas, USA) and Ikea (Sweden) — Retailers that drive accessibility and price competition, particularly for home-office and small-business channels. Strategic implication: they compress the low-end margin pool but also expand market penetration, creating volume opportunities for suppliers that can cost-effectively serve retail programs.
Recent industry movements and what they mean
-
Product catalog and showcase activity from several vendors in 2025–2026 signals that manufacturers are prioritizing refreshed portfolios to capture hybrid-work demand. Buyers should evaluate product life-cycles and availability lead times when planning 2026 roll-outs.
-
Market noise on labor and raw-material costs is not temporary background: the wood office-furniture PPI indexed near 295.7 in mid-2025, and steel/plastics volatility persists. These inputs are compressing manufacturer margins and prompting tiered pricing and longer lead times—factors that materially affect procurement strategies.
-
Regulatory tightening on load-bearing and fire-resistance standards increases supplier validation requirements. Teams should bake compliance verification into supplier selection rather than treating it as post-hoc diligence.
Risks, headwinds and mitigation strategies
-
Input-cost inflation: Adopt indexed pricing clauses, multi-sourcing strategies and inventory hedging where appropriate.
-
Regulatory compliance risk: Shift to certified suppliers, demand third-party testing documentation, and include warranty and liability protections in contracts.
-
Channel disruption: Retail entrants and direct-to-consumer brands compress margins—differentiate by packaging services (installation, asset tagging, maintenance) rather than competing on headline unit cost.
Investment, financing and procurement levers for 2026
For capital planners, two practical levers deserve attention. First, financing programs—such as long-term small-business loans available in some jurisdictions—can shift high-cost capex into structured, predictable repayments and accelerate deployment where ROI is front-loaded. Second, supplier partnership models that include performance-based rebates and lifecycle service bundles can convert purchase price into a managed-operating cost, smoothing budget impact and tying payoffs to realized space/utilization gains. PW Consulting’s report includes sample financial structures and sensitivity analyses tailored to common corporate procurement policies.
Opportunities to watch
-
High-density, mobile shelving and modular systems that enable flexible space repurposing will command premium consideration among space-constrained occupiers.
-
Product lines that combine aesthetic appeal with enterprise-grade safety and security (e.g., lockable, fire-rated modular cabinets) create cross-segment demand from corporate HQs to remote-office programs.
-
Sustainability credentials—recycled-content panels, cradle-to-grave takeback programs—are increasingly procurement decision criteria in RFPs and ESG reporting frameworks.
How to use PW Consulting’s full study
Consider the report your operational playbook for 2026: use the included supplier scorecards to shortlist vendors, the procurement templates to run compliant and competitive RFPs, and the ROI models to secure capex approvals. For investors, the competitive landscape analysis highlights consolidation targets and margin-lever opportunities; for corporate real estate and facilities teams, the implementation roadmaps convert strategic intent into milestones and KPIs.
Conclusion — a path to action
The Office Storage & Organization market in 2026 is neither a commodity space nor a boutique niche—it’s a configurable capability whose design and supply-chain choices ripple across occupancy economics, employee productivity and compliance risk. PW Consulting’s market research translates the sector’s steady growth and structural shifts into pragmatic, executable strategies. To access the complete dataset, granular segment analysis, and downloadable procurement tools that underpin these recommendations, consult the full report on our website—our trailer here shows the direction; the detailed intelligence is available in the source material for practitioners who need to act in 2026.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com