

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Capsule Filling Machines Market to Hit USD 344.8M by 2032 (6.98% CAGR)
By pmarketresearch, 2026-07-23
Capsule Filling Machines Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Industry Analyst, I present a concise, decision‑focused preview of our new market study on Capsule Filling Machines. This briefing is designed as a “trailer”: it demonstrates the analytical depth and practical utility embedded in the full report while intentionally withholding granular segmentation tables and proprietary model outputs. If you are evaluating capital expenditure, supplier selection, or M&A moves in 2026, the perspectives and frameworks below will help you prioritize where to dig deeper.
Capsule Filling Machines Market
Market snapshot and trajectory
The global capsule filling machines market is at an inflection point. With a 2025 base year market size of approximately USD 215 million and a compounded annual growth rate (CAGR) of about 6.98% projected through 2032, the industry is expected to approach the mid‑hundreds of millions by the end of the forecast window. This growth is not uniform: it is being driven by a combination of accelerating demand from pharmaceutical and nutraceutical producers, greater automation adoption across contract manufacturers, and expansion of small‑batch / personalized dosing applications. The dynamics create simultaneous opportunities for high‑throughput OEMs and for agile suppliers focused on flexibility and compliance services.
Capsule Filling Machines Market
Why this report matters for 2026 decisions
- CapEx prioritization: Equipments acquired in 2026 must balance throughput, validation effort, and future regulatory expectations—our economic models show typical payback windows and sensitivity to product mix and OEE (overall equipment effectiveness).
- Supplier selection & qualification: Beyond unit cost, regulatory pedigree (cGMP/CE), local service footprint, and spare‑parts certainty will determine long‑term TCO.
- M&A and partnership screening: Fragmentation plus bolt‑on service opportunities create windows for strategic acquisitions—our acquisition filter highlights targets that materially improve scale, aftermarket margin, or regulatory access.
- Product and R&D roadmaps: Firms must choose whether to invest in ultra‑high throughput automation, human‑centric modularity for small runs, or hybrid solutions. We map the risk/reward for each pathway.
- Regulatory readiness: With ongoing enforcement of cGMP, ISO standards, and mandatory reporting regimes, the report provides compliance checklists that reduce project delay risk.
What’s in the full report (practical deliverables)
- Proprietary market model (2020–2032) with scenario runs (base, upside, downside) and an interactive sensitivity layer for pricing, utilization, and SKU mix. Note: detailed regional and application splits are part of the paid dataset.
- CapEx/Opex templates and three bankable financial models for buyers, contract manufacturers, and OEMs—each includes IRR, NPV, and payback based on realistic OEE assumptions.
- Supplier scorecards and procurement RFP/RFQ language calibrated to regulatory and aftermarket needs.
- Operational playbooks: validation & qualification workflows (IQ/OQ/PQ), sanitation regimes consistent with FDA cGMP and ISO guidance, and maintenance schedules tied to MTBF/MTTR benchmarks.
- Service and aftermarket blueprints showing how spare parts, consumables, and remote diagnostics drive recurring revenue and margin uplift.
- Risk heatmaps covering supply‑chain concentration, single‑source components, critical raw material exposures, and regulatory enforcement hotspots.
- Competitive benchmarking and M&A screening tool that ranks targets on technology, regulatory approvals, installed base, and aftermarket revenue potential.
Competitive landscape — strategic read on key OEMs
The market is characterized by a handful of global OEMs with strong engineering pedigrees, a larger tail of regional suppliers, and specialized niche players. Market concentration metrics indicate a fragmented landscape (CR3 and CR5 are both modest, reflecting limited dominance by the largest vendors), which creates both competitive intensity and acquisition opportunities.
Capsule Filling Machines Market
- Syntegon Technology (Heidelberg, Germany) — Strength: high‑volume platform engineering and process integration. Strategic implication: ideal partner for CMOs pursuing highly automated, validated lines where throughput and precision dosing are priority.
- IMA Group (Bologna, Italy) — Strength: rotary/suction bowl technologies with extreme dosing flexibility. Strategic implication: suits customers balancing speed and variety; attractive for firms pursuing global scale in pharma and nutraceuticals.
- MG2 S.r.l. (Milan, Italy) — Strength: modularity and multi‑modal dosing across powders, pellets, and capsule‑in‑capsule formats. Strategic implication: differentiated value for specialty drug forms and customers emphasizing rapid changeover.
- ACG Worldwide (Mumbai, India) — Strength: integrated mid‑market systems with strong cost/benefit tradeoffs and service networks in emerging markets. Strategic implication: strong option for firms expanding production in cost‑sensitive geographies.
- Harro Höfliger (Oberschleißheim, Germany) — Strength: integrated packaging and filling systems optimized for pharmaceutical lines. Strategic implication: attractive to end‑to‑end line integrators and CMOs consolidating vendors.
- Qualicaps (Tokyo, Japan) — Strength: capsule and encapsulation tech with emphasis on compatibility and regulatory documentation. Strategic implication: appeals where capsule chemistry or novel capsule formats are constraints.
- Capsugel (Lonza Group) — Strength: longstanding capsule systems expertise aligned with drug‑delivery science. Strategic implication: premium partner for regulated pharma launches and complex formulations.
- Regional and cost‑competitive suppliers (Torpac, Dott Bonapace, Finetech, Index Capsule Fillers, Feton, etc.) — Strength: flexible offerings, rapid delivery, and favorable price points. Strategic implication: suitable for contract manufacturers, nutraceutical producers, and markets with lower regulatory friction.
Recent product activity illustrates two concurrent innovation vectors: (1) high‑throughput engineering improvements that push the envelope on dosing accuracy and throughput, and (2) human‑centered modular machines optimized for multi‑fill capability and quick changeovers. Examples from late‑2025 product releases point to more integrated weight control systems, enhanced dosing combinations, and a sharpened focus on operator ergonomics—each with direct implications for validation time and service requirements.
Regulatory and compliance dynamics that shape commercial choices
- FDA cGMP enforcement (21 CFR Parts 210 & 211 for pharmaceuticals, 21 CFR Part 111 for dietary supplements) means machines must be sanitary, maintainable, and designed for routine calibration and inspection. Procurement decisions must explicitly budget for validation time and documentation.
- ISO 9001 and ISO 22000 continue to be baseline requirements for manufacturers serving both pharmaceutical and nutraceutical markets; OEM certification status is a gating criterion for many regulated customers.
- DEA reporting requirements and mandated electronic transaction disclosures are non‑negotiable for certain flows—buyers and sellers need controls and IT systems that simplify compliance.
- CE marking and cGMP compliance are essential for market access in regulated regions; equipment without this pedigree increases time‑to‑market and risk of remediation.
Strategic recommendations for executives (short, medium, long term)
- Next 12 months (tactical): Prioritize supplier audits that validate cGMP documentation and spare‑parts SLAs; require factory acceptance tests (FAT) and documented OQ/PQ plans as part of procurement contracts. Consider pilot investments in remote monitoring to reduce unplanned downtime.
- 12–36 months (portfolio optimization): Adopt a two‑track equipment strategy: standardize on high‑efficiency, validated platforms for core SKUs while procuring modular, low‑volume equipment for personalized or niche products. Evaluate bolt‑on acquisitions to secure aftermarket revenue and local service capabilities.
- 36+ months (competitive positioning): Build or partner to deliver integrated line solutions (filling → encapsulation → packaging → serialization) to capture higher margin system sales. Invest in digital twins and predictive maintenance to convert machines into recurring revenue engines.
How PW Consulting helps
Our full Capsule Filling Machines Market report combines an audited market model, validated supplier due diligence, and executable playbooks. For purchasing managers, product heads, and corporate strategists evaluating moves in 2026, we provide the decision‑support tools to: reduce procurement risk, optimize asset allocation, prioritize integrations, and surface high‑ROI M&A candidates. This preview shows the frameworks; the full dataset and granular segmentation that underpin financial models are available through the PW Consulting portal.
To convert industry signals into 2026 actions—whether you are locking capital expenditure, sizing the service business, or screening acquisition targets—access the full report for complete data tables, region‑application breakdowns, and the proprietary M&A screening tool that we intentionally withhold here to preserve actionable exclusivity.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Long-term Care Software Market to Reach USD 642.7M by 2032 (8.0% CAGR)
By pmarketresearch, 2026-07-23
Long-term Care Software Market: Strategic Outlook for 2026 Decision-Makers
As healthcare providers confront accelerating regulatory complexity, labour constraints and a faster-than-expected adoption of AI-enhanced workflows, the economics and competitive dynamics of long-term care (LTC) software are materially shifting. Our latest PW Consulting long-form market study — with a base year of 2025 — quantifies that shift: the global LTC software market reached approximately US$376.8 million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of roughly 8.0%, reaching an estimated US$642.7 million by 2032. This briefing distils the strategic implications of those headline numbers for leaders making critical product, M&A, and compliance choices in 2026, while intentionally withholding detailed sub-segment tables to invite licensed access to the full report.
Long-term Care Software Market
Why this research is a 2026 must-read
-
Decision clarity under regulatory flux: The interplay between reimbursement updates, coding tool changes, and tightened security rules means software capability is now a gating factor for facility revenue and risk management. Executives who factor software compliance road maps into 2026 budgets avoid operational surprises.
Long-term Care Software Market -
Timing for technology bets: With the market growing at a mid-single-digit CAGR and leading vendors rapidly embedding AI, 2026 is the inflection window for ROI on ambient documentation, clinician decision support, and automated case-mix optimization.
Long-term Care Software Market -
M&A and partnership arbitrage: Moderate concentration among incumbents creates roll-up and specialty-aggregation opportunities; strategic acquirers can capture cross-sell value if they move before integration costs and regulatory requirements rise further.
-
Procurement and total cost of ownership (TCO): As adoption shifts from facility-centric EHRs toward hybrid facility-plus-home-care solutions, procurement teams must re-evaluate vendor lock-in, integration cost, and multi-year support models.
What the full PW Consulting report delivers (practical, actionable content)
-
Top-line market sizing and scenario-validated forecasts (2026–2032) with sensitivity bands calibrated to reimbursement and AI adoption trajectories.
-
Go-to-market playbooks for vendors and system integrators: buyer personas, procurement timelines, proof-of-value milestones, and recommended pricing frames for SaaS and managed-service models.
-
Regulatory compliance toolkit: a mapping of FY2026 policy changes to software capability requirements, implementation checklists, and a prioritized remediation roadmap for vendors and providers.
-
Vendor selection and RFP templates, plus a technology interoperability scorecard focused on APIs, HIE participation, and real-world integration costs.
-
M&A playbook and valuation sensitives: consolidation scenarios, integration risk matrices, and a short-list of capability gaps that drive premium valuations (e.g., ambient AI, advanced case-mix tools, home-health scheduling).
-
Operational playbooks for provider organizations: clinician workflow redesign templates, project timelines for PHI security hardening, and KPI dashboards that tie software adoption to revenue cycle and quality metrics.
Market dynamics shaping vendor and buyer strategy
-
Regulatory and reimbursement drivers. FY2026 brought several material rule changes that directly affect LTC software requirements. Notably, CMS released a PDPM ICD‑10 mapping update with multiple changes effective October 1, 2025, which alters MDS/RAI coding and reimbursement calculations — immediate software support for accurate mapping is essential to protect facility revenues. In parallel, the FY2026 Skilled Nursing Facility PPS final rule updated quality reporting and case-mix requirements; vendors that fail to operationalize these changes into automated workflows increase adoption friction for customers.
-
Security and operational risk. HHS amendments to the HIPAA Security Rule effective in 2026 require compressed breach reporting windows and more frequent vulnerability scanning for in-scope EHR systems. These obligations create compliance costs and force software architects to prioritize secure-by-design deployments and managed detection capabilities.
-
AI and clinician productivity. The combination of labour shortages and reimbursement pressure is accelerating interest in AI features that reduce documentation burden and detect clinical risk. Vendors embedding ambient scribing, intelligent triage, and coding-assist modules are demonstrating near-term productivity gains that translate into measurable ROI for buyers.
-
Shift to hybrid care models. Demand is migrating toward integrated solutions that span skilled nursing, assisted living and home health. Vendors that offer seamless transitions-of-care and billing continuity across settings are positioned to win multi-year contracts.
Competitive landscape — strategic implications for incumbents and challengers
-
PointClickCare (Chicago, IL, USA — https://pointclickcare.com/) : The company’s AI-powered EHR for skilled nursing and senior living is rapidly evolving to include ambient scribing and workflow automation. Recent launches (notably a next-generation EHR with AI-driven workflows) indicate a strategy of deepening clinician-facing automation to reduce administrative burden and to lock-in clients through productivity gains. For competitors, matching value requires equivalent clinical NLP and coder-assist features plus strong migration services.
-
MatrixCare (Bloomington, MN, USA — https://matrixcare.com/) : MatrixCare’s strength remains in integrated EHR and home health solutions with a focus on MDS/RAI, billing and quality reporting. The company benefits from breadth across care settings; challengers should focus on niche differentiation (e.g., specialized analytics, faster implementations) to displace entrenched customers.
-
WellSky (Overland Park, KS, USA — https://wellsky.com/) : WellSky’s expansion of its SkySense AI into long-term care underscores a platform play: operational efficiency, documentation quality, and clinician productivity. The vendor’s approach highlights the importance of embedding AI into core workflows rather than as bolt-on tools. For buyers, evaluate how AI features map to documented time- and cost-savings rather than vendor promise alone.
-
Netsmart Technologies (Cleveland, OH, USA — https://www.ntst.com/) : With platforms that span post-acute and long-term care, Netsmart competes on care coordination and value-based care enablement. Its positioning favors providers seeking integrated population health capabilities; standalone EHR vendors must show compelling integration strategies to remain relevant in coordinated-care contracts.
-
American HealthTech (Ridgeland, MS, USA — https://www.healthtech.net/) : Now part of consolidation flows after acquisition activity, American HealthTech’s legacy strengths in MDS/RAI automation and reimbursement tools illustrate why vertical capabilities remain valuable acquisition targets. Acquirers should anticipate integration costs and the need to harmonize clinical models quickly.
-
Optimus EMR (USA — https://www.optimusemr.com/) and HealthMEDX (USA — https://healthmedx.com/) : These cloud-native and specialized EHR providers supply competition in the skilled nursing niche. Their relative agility and lower migration friction can appeal to mid-market providers; however, scale and regulatory feature parity remain barriers to winning larger enterprise contracts.
-
Market concentration note: The market exhibits moderate concentration with leading vendors holding meaningful share; consolidation and platform expansions are expected to continue through 2026 as incumbents chase adjacent capabilities and data-driven services.
Practical implications and recommended 2026 playbook
-
Fast-track compliance engineering. Providers and vendors must prioritize implementation of PDPM ICD‑10 mapping fixes and HIPAA-required vulnerability scanning within 1–2 quarters; delayed compliance risks immediate revenue and regulatory penalties.
-
Build ROI-first AI pilots. Run tightly scoped pilots for ambient scribing and coder-assist that measure time-savings, documentation completeness and reimbursement accuracy. Vendors should offer “pilot-to-scale” pricing that mitigates buyer risk and shortens procurement cycles.
-
Re-evaluate contract structures. Buyers should negotiate outcome‑linked SLAs and migration support, while vendors should price integrations and data migration as modular services to lower procurement friction.
-
Prepare M&A and partnership playbooks. Strategic acquirers should prioritize targets that bring capability gaps (e.g., advanced AI, home-health scheduling, specialized billing engines) and realistic integration roadmaps.
-
Operationalize security. Technical teams must adopt managed vulnerability scanning and incident response runbooks to comply with the new short breach-reporting windows; expect increased demand for SOC-as-a-service among cautious providers.
How PW Consulting’s study helps you act in 2026
Our study combines quantitative forecasting with executable toolkits, vendor scorecards, and regulatory impact assessments designed for senior executives, product leaders, and corporate development teams. It translates the headline growth trajectory (CAGR ~8.0%) into concrete action items — from prioritizing engineering sprints for updated ICD‑10 mappings to structuring AI pilots that deliver measurable financial upside within 6–12 months.
This article is a strategic trailer: we’ve outlined the major forces, vendor positions, and immediate actions that will determine winners and losers in 2026. For access to our full modeling, vendor benchmarking matrices, downloadable RFP templates, and the step-by-step compliance playbook, please consult the PW Consulting report page and licensed deliverables. The detailed sub-segment tables, regional breakdowns and proprietary scenario models are available exclusively in the full report to support procurement, M&A due diligence, and product-roadmap decisions.
Author: Senior Strategy Advisor & Chief Industry Analyst, PW Consulting — specializing in health IT and long-term care technology strategy.
For detailed analysis of this topic, please visit the official page: Long-term Care Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Material-Based 3D Printing to Expand at 20% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
Metal Material Based 3D Printing Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
Between 2020 and 2025 the metal-material-based 3D printing market shifted from a nascent production technology into a commercially materialized industrial platform. Our report uses 2025 as the base year, captures the 2020–2025 historical arc and projects through a 2026–2032 forecast window. At the market level the sector is expanding rapidly — underpinned by a sustained compound annual growth rate of 20% — and the model points to a multi-fold increase in total market value by the end of the forecast horizon. For 2026, this inflection creates a narrow window where choices made by OEMs, material suppliers, integrators and end-users will determine competitive positioning for the remainder of the decade.
Metal Material Based 3D Printing Market
Why this research matters for 2026 strategic planning
-
Decision acceleration: Firms that translate growth trajectories into concrete capacity, qualification and commercialization plans in 2026 will capture disproportionate share during the high-growth phase.
Metal Material Based 3D Printing Market -
Risk prioritization: Rapid expansion amplifies supply chain, certification and technology risks. Our analysis converts those abstract risks into prioritized mitigation paths to protect revenue and time-to-market.
Metal Material Based 3D Printing Market -
Investment discipline: With capital allocation decisions running against a 20% sector CAGR, the report equips boards and corporate development teams to evaluate opportunities with consistent valuation and scenario frameworks.
Market trajectory — what the numbers imply (without spoiling the segmentation)
The market exhibited steady growth in the historical window, accelerating toward the base year as industrial applications moved from prototyping to qualified production. Projecting forward under conservative, base-case and aggressive adoption scenarios, the market continues to compound at roughly 20% annually across 2026–2032. Practically, this dynamic means that supply and qualification capacity that looks sufficient in early 2026 can become a binding constraint within 18–36 months unless addressed proactively.
Key takeaways from the trajectory modeling:
-
Short lead times for equipment and materials will be a competitive asset; lead-time delta translates directly into production share.
-
Qualification-and-compliance investments pay back faster in heavily regulated verticals where traditional supply chains yield to certified additive solutions.
-
Scenario sensitivity to raw-material bottlenecks and certification cycles is material; executives must stress-test procurement, inventory and certification pathways.
Report contents — what executives and practitioners will find
This study is built to be operational rather than purely descriptive. Highlights include:
-
Methodology and transparent assumptions: detailed market sizing algorithms, data sources and modeling logic for reproducibility.
-
Technology-and-material taxonomy: mapping of process families (LPBF, EBM, DED, etc.) to metal feedstocks and performance trade-offs.
-
Go-to-market playbooks: commercialization trajectories for equipment makers, powder suppliers and service bureaus, including pricing dynamics and aftermarket strategies.
-
Supply chain maps and vulnerability assessment: near-term pinch points, strategic inventory levers, and contract structures to de-risk throughput.
-
Regulatory and certification roadmap: step-by-step checklists for ISO/Nadcap compliance and aerospace/defense qualification, with timing estimates and cost-band guidance.
-
Buyer personas and adoption curves: decision-maker profiles across aerospace, medical, industrial and specialty verticals and scenario-based adoption timing.
-
Financial and valuation frameworks: investment case templates, unit-economics models and sensitivity analyses customized for manufacturers, powder producers and service providers.
-
Competitive benchmark appendix: strategic profiles and capability matrices for principal vendors, with relative positioning across scale, materials expertise and software ecosystems.
Competitive landscape — who matters and why
The market concentration metrics indicate a moderate level of aggregation at the top. The largest three suppliers collectively command a meaningful share, and the top five widen that control — an important context when evaluating channel strategies and partnership opportunities.
Core industrial players profiled in the report include established equipment manufacturers, legacy metal producers that are vertically integrating into powders, and specialist system vendors. Briefly:
-
EOS GmbH (Krailling, Germany): A leader in LPBF hardware and an expanding materials portfolio. EOS’s continued material launches and regional investments signal a strategy of vertical breadth and reduced delivery friction.
-
Nikon SLM Solutions (Lübeck, Germany): Focused on large-format LPBF systems for aerospace and defense use cases, with recent software investments to strengthen data-prep and production workflows.
-
Renishaw plc (United Kingdom): Strong in precision systems for aerospace and medical applications; recognized for tight process control and material-system coupling.
-
3D Systems Corporation (United States): Offers a broad portfolio including DMP and ProX series systems and industrial powders, positioning it across prototyping and scaled production.
-
Colibrium Additive (GE Additive) (United States): Integrates EBM and LPBF capabilities, targeting high-performance alloy applications and leveraging GE’s industrial relationships.
-
Material specialists: Höganäs, Carpenter Technology, Sandvik, ATI Powder Metals and others are shifting from upstream metal production toward finer-grained, AM-optimized powders and integrated services.
Recent events captured in the report illustrate strategic moves to secure technology, materials and regional presence. Examples include new material introductions, system orders for naval applications, regional production capacity investments, and next-generation software rollouts — each a signal of directions the market is consolidating around.
Regulation, qualification and certification — the hidden runway
One of the most actionable sections addresses regulatory cadence and qualification pathways. Industrial adoption is now gated less by machine capability and more by material/process qualification frameworks. New ISO standards and Nadcap expectations are creating a turning point: firms that embed certification roadmaps into product development and supply-chain agreements will unlock rate-of-production advantages.
For defense-linked projects, procurement requirements and qualification cycles demand long lead-time planning; the military printing segment is growing at a materially higher CAGR than commercial averages. The implication for 2026 strategies is clear — prioritize certification investments where contract pipelines and margin dynamics justify the upfront effort.
Materials and supply chain — titanium, powders and vertical integration
Titanium feedstock remains a dominant demand driver across aerospace and medical verticals due to its specific strength and biocompatibility. At the same time, metal powder suppliers are expanding capacity and pursuing vertical integration to capture value upstream. Our supply-chain diagnostics identify which raw-material dependencies are most likely to create price or delivery shocks, and outline contractual and inventory approaches to mitigate those shocks.
-
Inventory strategies: recommended buffer levels by risk class, contract clause language samples and alternative-sourcing playbooks.
-
Qualification-as-a-service: how service providers can convert certification expertise into recurring revenue streams.
-
MRO and aftermarket implications: component repair and spare-parts economics for regulated fleets.
Investment, M&A and partnership signals
With a high-compounding growth profile, the sector is ripe for strategic M&A that fills capability gaps (materials, software, qualification services) and extends geographic reach. The report provides action-oriented templates for target screening, valuation premia for certified supply assets, and integration playbooks that anticipate cultural and technical friction points.
How to use this study in a 2026 decision cycle
-
For CEOs and boards: prioritize certification and capacity decisions using the report’s scenario models to avoid late-mover disadvantages.
-
For heads of supply chain: deploy the supply vulnerability index and procurement templates to lock in critical feedstock and reduce lead-time risk.
-
For product and engineering leaders: adopt the technology-material matrix and qualification roadmap to compress validation timelines while preserving compliance.
-
For investors and corporate development: use the M&A playbooks and valuation frameworks to size deals and quantify synergies across the equipment-to-powder stack.
Call to action — the contained value
This briefing surfaces the strategic contours and operational levers that matter in 2026, while protecting the granular segmentation and proprietary scenarios that drive tactical execution. The full report contains the detailed segmentation tables, scenario spreadsheets, vendor scorecards and certification checklists that practitioners need to convert insight into action. Access to the full dataset and appendices will materially shorten your path from decision to deployment.
PW Consulting’s Metal Material Based 3D Printing Market study is designed to be the decision-ready input for corporate planning cycles in 2026. For teams preparing budgets, supply contracts or acquisition screens this quarter, the report provides the empirical backbone and turnkey playbooks necessary to move from strategy to measurable outcomes.
For detailed analysis of this topic, please visit the official page: Metal Material Based 3D Printing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radar Level Transmitters Market Poised for 5.69% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
Radar Level Transmitters Market — Strategic Preview for 2026 Decision-Makers
Introduction
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise strategic preview of our Radar Level Transmitters Market study — a toolkit designed to inform capital allocation, procurement, R&D, and M&A decisions in 2026. The industrial measurement sector is entering a phase where new regulatory regimes, sensor-technology maturation and W-band scale economics intersect to reshape supplier economics and customer requirements. This preview surfaces the high‑impact conclusions and strategic implications while intentionally holding back the granular segmentation tables and scorecards — the premium intelligence our full report delivers.
Radar Level Transmitters Market
Executive snapshot
-
Market trajectory: The radar level transmitters market expanded from a baseline of USD 425 million in 2020 to USD 606.11 million (base year 2025), and is forecast to continue growth under the study’s scenarios, reaching roughly USD 894.0 million by 2032.
Radar Level Transmitters Market -
Growth rate: Our forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of 5.69% — a pace driven by regulatory upgrades, technology substitution (notably 80 GHz solutions), and steady industrial automation demand.
Radar Level Transmitters Market -
Market structure: Concentration is meaningful but not insurmountable — the top three vendors account for under one-third of market revenues (CR3 ≈ 28.5%), while the top five control a majority (CR5 ≈ 53.4%). This dynamic preserves scale advantages for incumbents while leaving clear openings for well‑funded challengers and niche specialists.
Why this study matters to 2026 strategic choices
-
Regulatory inflection points are creating procurement urgency. New European overfill-protection mandates, methane-emission tank-gauging requirements, and certification expectations for water and hazardous applications are converting tentative upgrade cycles into near-term projects for many operators.
-
Technology is consolidating around W‑band (roughly 76–81 GHz) and high-frequency FMCW architectures. These architectures offer measurable accuracy gains, reduced environmental sensitivity, and in many cases lower lifecycle cost — while recent regulatory approvals have accelerated their commercial viability.
-
Scale economics are re-pricing the premium for 80 GHz and W‑band devices. As certification and clearance broaden, price differentials that historically insulated legacy players are shrinking; procurement teams should expect more aggressive commercial terms from manufacturers competing on volume.
-
Connectivity and diagnostics are becoming table stakes. Wireless, Bluetooth, and cloud-enabled diagnostic features (for remote commissioning, predictive maintenance and digital twins) are differentiators for buyers targeting OPEX reductions and uptime improvements.
What the PW Consulting report delivers — practical outputs
Our full study is organized to support direct action. Core deliverables include:
-
Robust market sizing and scenario-based forecasts (2026–2032) with methodology transparency and sensitivity testing to fuel capex planning and ROI analysis.
-
Segmentation frameworks by device architecture (guided‑wave vs. pulsed vs. FMCW), by application (liquids, slurries, interfaces, solids), and by commercial geography — presented as decision-ready dashboards rather than static charts.
-
Competitive benchmarking: vendor scorecards, product feature matrices, channel maps and recent development timelines to inform vendor shortlists and preferred‑supplier negotiations.
-
Regulatory & certification heatmaps that map regions and verticals to certification requirements, enforcement risk and likely early-adopter cohorts.
-
Go‑to‑market playbooks for vendors and procurement playbooks for end‑users — including pilot design templates, total cost of ownership models, and contract clauses to protect against performance drift.
-
M&A and partnership intelligence: target lists and valuation heuristics for roll-up strategies, technology acquisitions and distribution partnerships.
-
Interactive datasets and Excel models that allow scenario adjustments by price, deployment volume, retrofit vs. greenfield mix, and certification time-to-market.
Competitive landscape — strategic observations
The vendor field includes a mix of global systems integrators, instrumentation specialists and focused niche suppliers. Key players analyzed in the report include Emerson, Endress+Hauser, Siemens, ABB, VEGA, KROHNE, Honeywell, Yokogawa, Ametek (Magnetrol), Schneider Electric and several regional specialists. Our analysis identifies three supplier archetypes and their implications for procurement and partnership strategy:
-
Global integrators (e.g., Emerson, Siemens, ABB, Honeywell): Offer broad automation portfolios and strong channel reach. Strengths include system-level integration, large installed bases and bundled service offerings. Watch their tradeoffs: higher TCO for standalone sensing vs. superior lifecycle service contracts and integration risk mitigation.
-
Instrumentation specialists (e.g., Endress+Hauser, VEGA, KROHNE, Yokogawa): Lead on sensing innovation (80 GHz FMCW, hygienic approvals, advanced diagnostics). They are typically first to market on certifications and niche features, making them attractive partners for quality- and compliance‑driven buyers.
-
Niche and regional players (e.g., Magnetrol/Ametek, Nivelco, Kobold, APG): Compete on price, specialized product variants (explosion-proof pulse radar) and rapid local service. These firms are often the source of product-level disruption in regional tenders or in verticals with idiosyncratic needs.
Recent vendor moves reinforce these dynamics: product introductions (new 80 GHz lines from multiple vendors), enhanced certifications for water and hazardous use, and the launch of wireless/non‑contact compact transmitters designed for simplified commissioning. These developments accelerate the substitution of older ultrasonic and legacy radar devices.
Regulation, certification and technology: the nexus for 2026 strategy
Regulation is the single greatest accelerant to near-term demand. Across Europe, tighter overfill-protection and methane-monitoring rules are driving immediate upgrade programs in storage and utilities. Certification milestones — MCERTS, WRAS, ATEX/Ex ia, SIL2/3 — are becoming procurement filters rather than optional marketing badges. On the technology side, FMCW and high‑frequency radar are the instruments of choice for operators seeking accuracy and repeatability in difficult process conditions (foam, dust, interfaces).
Implications:
-
For vendors: Prioritize certification roadmaps and test investments; a validated certification path can unlock entire verticals (e.g., potable water, hazardous petrochemical tanks).
-
For buyers: Reassess retrofit windows — regulatory deadlines create profitable windows for staged upgrades that realize regulatory compliance while optimizing CAPEX schedules.
-
For investors: Look for vendors that combine certification velocity with manufacturing scalability — these firms are best positioned to capture market share as W‑band adoption normalizes.
Actionable recommendations for 2026
-
Start with a regulatory gap analysis. Map assets against applicable overfill, methane and potable-water rules to prioritize retrofit candidates that deliver both compliance and measurable OPEX savings.
-
Favor vendor shortlists that demonstrate both certifiable product roadmaps and digital diagnostics — immediate value accrues from reduced commissioning time and predictive maintenance capabilities.
-
Use staged pilots to de‑risk scale rollout. Pilot in representative process conditions (interface layers, solids handling, foam-prone vessels) and validate vendor diagnostics vs. independent verification.
-
Negotiate lifecycle terms, not only price. Given concentration dynamics, total cost of ownership (service SLAs, spare parts logistics, cloud compatibility) will separate winners from losers.
-
For vendors, prioritize channel partnerships that accelerate certification acceptance in regulated verticals and pursue product modularity to address retrofit complexities.
-
For corporate development teams, monitor mid‑tier specialists with strong certification credentials — these often represent high-value acquisition targets for larger systems integrators seeking to close capability gaps.
How to use this preview
This brief is a strategic précis meant to surface the most consequential forces shaping supplier economics and buyer priorities in 2026. If your team is planning procurement cycles, R&D roadmaps, or M&A pipelines this year, the full PW Consulting Radar Level Transmitters Market study provides the operational detail (segmentation tables, vendor scorecards, contract language templates, and interactive financial models) to convert these strategic directions into executable programs.
To access the full dataset, vendor benchmarking, and actionable playbooks that underpin the conclusions above, consult the PW Consulting market report page and the accompanying interactive workbook. The granular segmentation and vendor scoring — intentionally omitted here — are provided only within the full subscription deliverable to preserve the integrity of the source intelligence and to equip your team with decision-ready materials for 2026 deployments.
For detailed analysis of this topic, please visit the official page: Radar Level Transmitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Pressure Transducers Market to hit USD 535M by 2032 (6.5% CAGR)
By pmarketresearch, 2026-07-23
Medical Pressure Transducers Market — Strategic Preview for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a focused strategic briefing on the Medical Pressure Transducers market intended to orient executive decision-making for 2026. This preview synthesizes our new market study’s most consequential signals — macro growth, regulatory pressure points, supplier dynamics, and competitive moves — while preserving the full, segment-level intelligence for clients who access the complete report.
Medical Pressure Transducers Market
Market snapshot: steady growth, concentrated strategic choices
Between 2020 and 2025 the global Medical Pressure Transducers market expanded from a modest base to an established multi-hundred-million dollar market. By our base year (2025) the market reached approximately USD 360 million (revenue unit: Million USD). Our forecasts through 2032 model a compound annual growth rate (CAGR) of roughly 6.5%, with total market value expected to surpass half a billion dollars by the end of the forecast horizon.
Medical Pressure Transducers Market
The implication is straightforward: this is a stable, predictable category with sufficient tailwinds to justify near-term investment, but not a runaway high-growth opportunity. That combination creates distinct strategic imperatives — optimize cost and distribution, shore up regulatory and quality assurance capabilities, and look for incremental share gains via product differentiation or adjacency plays.
Medical Pressure Transducers Market
Why this study matters for 2026 strategy
- Actionable revenue planning: With credible base-year data and a transparent forecasting engine, leadership teams can align 2026 P&L and capex planning to a realistic demand curve rather than aspirational targets.
- Regulatory and procurement timing: Our timing models translate regulatory lead times and hospital procurement cycles into actionable go/no-go gates for product launches, contract renewals, and inventory provisioning.
- M&A and partnership prioritization: The market’s moderate concentration and clear supplier archetypes create identifiable targets for bolt-on acquisitions, channel partnerships, or OEM agreements — but timing and valuation hinge on robust segment-level visibility (available in the full report).
- Supply-chain resiliency: Given the category’s reliance on specialty materials and single-sourced subcomponents, tactical inventory and supplier strategies derived from our scenario analysis materially reduce service interruption risk.
Key market dynamics informing 2026 choices
- Regulatory tightening and certification delay: The EU MDR re-certification timeline has lengthened materially over 2021–2025, with associated costs rising significantly. In practice this means new product launches and EU entry strategies require earlier investment and contingency planning for certification delays.
- FDA Class II governance remains foundational: The regulatory baseline for hemodynamic and invasive blood pressure transducers remains rigorous, with biocompatibility, calibration accuracy, and human factors under close scrutiny. Manufacturers must plan regulatory cycles into product roadmaps and supplier qualification timelines.
- Standards and calibration variability: ISO 80601-2-34 sets performance expectations, but calibration practices vary across hospitals, clinicians, and manufacturers. This creates an opportunity for vendors that can deliver demonstrable, audit-ready calibration processes and training packages as part of their value proposition.
- Materials and sourcing pressure: The bill-of-materials for transducers includes silicon, stainless steels, specialty alloys and medical-grade plastics. Our supplier risk matrix highlights single- and low-source exposures that can produce lead-time spikes and cost inflation during demand surges.
- Compatibility and commoditization risks: Recent product clearances that expand adapter and compatibility options have the potential to commoditize certain transducer accessories, intensifying margin pressure for incumbents who rely on proprietary lock-in.
Competitive landscape — what incumbents and challengers are signaling
The vendor ecosystem is dominated by a mix of established medical device firms and specialized suppliers. The market exhibits a moderate level of concentration: several leading suppliers control meaningful, but not overwhelming, shares — leaving room for disruption and share-shift through commercial excellence or differentiated technology.
- Edwards Lifesciences (Irvine, CA) — Known for the TruWave disposable pressure transducer family focused on invasive hemodynamic monitoring. The product is a clinical staple, but recent adverse-event reporting underscores how quality incidents can rapidly become procurement and reputational risks. Buyers and investors should expect heightened post-market surveillance and possible mitigation costs.
- Smiths Medical (Minneapolis, MN) — Market presence with the TranStar disposable transducer systems; a strong hospital-facing commercial model provides sticky relationships but also exposes Smiths to contract renegotiation pressure as buyers seek cost-efficiencies.
- ICU Medical (San Clemente, CA) — Offers integrated and disposable Transpac systems for critical care; strength lies in integrated solutions and service bundles that span consumables and monitoring platforms.
- Merit Medical Systems (South Jordan, UT) — Meritrans products and disposable systems position Merit as a competitively priced supplier with clinical penetrations in interventional suites; success depends on supply-chain scale and targeted account growth.
- Argon Medical Devices (Plano, TX) — Supplies pressure monitoring lines and transducer kits tailored to interventional procedures; their solutions play well with procedural specialties and create natural adjacency opportunities with catheter-based disposables.
Recent events to factor into 2026 strategy: an FDA MAUDE adverse-event report related to a leading disposable transducer late in 2025 has catalyzed purchasing reviews at several health systems; and a September 2025 510(k) clearance for an IBP transducer adapter cable that is broadly compatible with multiple major brands increases interoperability and potential price competition. Both developments change how procurement teams evaluate vendor risk and total cost of ownership.
What the full PW Consulting report delivers (practical contents)
- Comprehensive market model (historical 2020–2025, base year 2025, forecast 2026–2032) with transparent assumptions and sensitivity toggles.
- Segment-level demand drivers and elasticities (by product archetype and clinical use case) — modeled scenarios for reimbursement, hospital capex cycles, and pandemic-like stresses.
- Regulatory timeline playbook: EU and US clearance paths, expected timelines, estimated costs, and certification gating milestones for 2026 launches.
- Supplier and raw-material risk maps with mitigation checklists (dual-sourcing strategies, contract clauses, inventory policy recommendations).
- Vendor scorecards and commercial benchmarking against clinical adoption metrics and procurement KPIs.
- Transaction-ready diligence templates for M&A (valuation sensitivity tables, integration checklists, and synergy capture pathways).
- Actionable go-to-market modules: pricing elasticity tables, account segmentation frameworks, and sample contracting language to protect margins in interoperable accessory markets.
- Data annex with regulatory events, MAUDE extractions, selected 510(k) logs, and the underlying interview transcripts (anonymized).
How executives should use these findings in 2026
- CEOs and corporate strategists: Use the market model to stress-test M&A targets and to set three-year product roadmaps. Prioritize targets that help mitigate raw-material exposures or add service-driven revenue.
- VPs of product and R&D: Accelerate investments in calibration assurance, human factors, and interoperability; these reduce procurement objections and shorten sales cycles.
- Heads of procurement: Translate the competitive events noted above into RFP clauses that require compatibility, post-market surveillance commitments, and recall/incident response guarantees.
- Finance leaders: Adjust working capital and inventory policies to buffer certification-driven delays and supplier lead-time volatility; model downside scenarios at 1.5–2x the historical lead-time to prepare for regulatory extension risks.
Risk map — prioritized
- Regulatory delay risk: High — EU recertification and nuanced FDA expectations can stall launches and reduce addressable market in the short term.
- Quality & post-market events: Medium-High — Adverse-event disclosures materially affect purchasing decisions, reimbursement support, and brand premium.
- Materials and supplier concentration: Medium — Single-source components create periodic spikes in lead-times and cost; hedging strategies reduce this exposure.
- Commoditization through interoperability: Medium — Cross-vendor adapters and accessories pressure margins for legacy players reliant on proprietary consumables.
Final recommendations — near-term playbook
- Immediately audit supplier exposure for silicon and specialty alloys; implement alternative sourcing pilots with contract provisions linked to lead-time SLAs.
- Prioritize regulatory backlog: if launching in or selling into EU markets, accelerate MDR re-submission plans now to avoid 12–18 month certification slippage.
- Enhance post-market surveillance and clinician-facing calibration support as a commercial differentiator; document training and calibration processes as sale-enablers.
- Evaluate selective interoperability strategies — offer certified adapter bundles to lock-in account penetration while preserving margin through service and training contracts.
- Use the report’s M&A diligence templates to screen targets that either consolidate distribution channels or add control over critical consumable supply chains.
PW Consulting’s full Medical Pressure Transducers Market report provides the granular, segment-level data, country and channel breakdowns, and downloadable modelling workbooks needed to operationalize the playbook above. This preview highlights the signals that should influence 2026 decisions; the complete report contains the actionable datasets and vendor-level intelligence executives require to convert those signals into reliable outcomes.
To access the full datasets, vendor scorecards, and transaction-ready templates, visit the PW Consulting report page or contact your PW Consulting advisor for a confidential walkthrough and tailored scenario analysis.
For detailed analysis of this topic, please visit the official page: Medical Pressure Transducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Water Meters Market to Reach USD 16.29M by 2032 at 9.6% CAGR
By pmarketresearch, 2026-07-23
Smart Water Meters Market: Strategic Briefing for 2026 Decision-Making
Executive overview
As utilities, technology vendors, and investors sharpen their focus on decarbonization, resilience and digital transformation, smart water metering has moved from a niche pilot activity to a mainstream infrastructure priority. Our latest PW Consulting market study — anchored on a 2025 base year with a historical window of 2020–2025 and a forecast horizon of 2026–2032 — synthesizes macro trends, vendor positioning, deployment economics and regulatory catalysts that will determine winners and laggards over the next investment cycle. The market exhibits mid-single-digit to high-single-digit expansion dynamics, with a compound annual growth rate of 9.6% across the forecast period, reflecting steady adoption of AMI/AMR, communications layer maturation, and the monetization of meter-generated telemetry.
Smart Water Meters Market
Market trajectory at a glance
Between 2020 and 2024 the market scaled noticeably, reflecting a growing wave of municipal and utility upgrades. The dataset used in this study captures both the pre-2025 deployment momentum and a recalibration in 2025, followed by a re-acceleration through 2032. Our top-line forecast shows the addressable market growing through the late 2020s as digital communications, analytics and finance models converge to lower the total cost of ownership for utilities and end customers.
Smart Water Meters Market
Why this study matters for 2026 strategic choices
2026 is a pivotal year: program budgets set now will influence procurement cycles, partnership contracts, and asset renewal timelines that span a decade. PW Consulting’s Smart Water Meters Market study provides the kind of decision-grade intelligence that boards, utility CFOs and product chiefs need:
Smart Water Meters Market
- Clear short-term signal versus long-term structural growth — the report reconciles near-term program variability with a structural CAGR outlook of 9.6% (2026–2032), enabling finance and procurement teams to stress-test investment cases against realistic adoption curves.
- Tactical procurement frameworks — detailed playbooks for RFx design, supplier evaluation and OPEX vs CAPEX modeling reduce procurement risk and accelerate time-to-value for municipal projects.
- Technology roadmaps for interoperability — the study maps communications stacks (cellular, LPWAN, RF, 5G) against utility needs, showing which modalities best balance reach, lifecycle cost, and analytics enablement in 2026 deployments.
- Regulatory and funding levers — our analysis highlights how public programs and grant mechanisms are materially changing feasibility on a project-by-project basis.
Actionable intelligence included in the report
The PW Consulting study was designed as a pragmatic toolkit for decision-makers. Key deliverables inside the report include:
- Executive dashboards: scenario-based market sizing for 2026–2032 to support board-level capital allocation and M&A prioritization.
- Vendor scorecards: comparative matrices that synthesize product breadth, communications options, analytics capability, deployment track record, and integration maturity.
- Procurement templates: standardized RFx language, acceptance test criteria for field devices and communications, and contract clauses to mitigate obsolescence risk.
- Deployment playbooks: step-by-step guides for pilot-to-rollout sequencing, workforce planning, and community engagement to minimize customer friction and maximize meter-read accuracy.
- Financial models: total cost of ownership (TCO) and payback calculators that account for labor savings, leak reduction, non-revenue water impacts, and incremental analytics monetization.
- Risk heatmaps: cybersecurity, supply-chain and regulatory risks scored by likelihood and impact, with mitigations prioritized for 2026 adoption windows.
Competitive landscape — who matters and why
The vendor ecosystem remains a mix of global platform providers, specialized meter manufacturers and regional systems integrators. Market concentration is modest: the top three vendors account for under one-third of the market and the top five players capture well under forty percent, indicating a fragmented battleground where product differentiation and service excellence win contracts as often as price.
Highlights from our vendor analysis:
- Technology incumbents with platform depth: Companies with integrated AMI platforms and strong analytics stacks tend to win larger municipal and utility contracts because they can deliver end-to-end SLAs. Their strengths include advanced metering infrastructure, cloud analytics and proven integration with billing systems.
- Specialist meter manufacturers: Ultrasonic and electromagnetic meter specialists have converted accuracy and low-maintenance narratives into compelling total-cost-of-ownership cases for utilities prioritizing leak detection and long life cycles.
- Communications-first entrants: Vendors that provide flexible connectivity (cellular, LPWAN, and RF hybrids) are capitalizing on utilities’ desire to avoid single-vendor lock-in on the communications layer.
- Regional players and certification advantages: Local vendors with relevant ISO/MID certifications and localized field support remain competitive in procurement processes where local sourcing and O&M economics matter.
The full report contains vendor profiles, strengths/weaknesses/opportunity/threat summaries, and procurement playbooks mapped to each supplier archetype — a valuable asset for sourcing teams building their short-lists in 2026.
Regulatory, funding and program-level dynamics
Policy and grant programs have become decisive levers influencing adoption. Public grants and projects continue to underwrite deployment costs, especially in water-stressed or federally funded regions. For example, grant-funded initiatives that resumed or accelerated in early 2026 illustrate how public financing can convert stalled programs into large-scale rollouts. Similarly, pan-European programs supporting smart water networks are creating technology roadmaps and interoperability requirements that will reshape procurement specifications across jurisdictions.
Regulatory trends to watch in 2026:
- Interoperability mandates from regional bodies and funders that push utilities toward open AMI architectures.
- Incentive programs and grants that lower the capital barrier for meter replacement and payback-sensitive municipal budgets.
- Data governance and privacy expectations that increase contractual obligations for meter vendors and analytics providers.
Recent signals from the field — why they matter now
Field-level developments in 2025–2026 provide concrete evidence of momentum and priorities. Multiple U.S. utilities completed or launched major upgrades to AMI systems that deliver hourly reads, leak alerts and customer portals. Some districts redeployed federal grants to accelerate replacements, and utilities increasingly reference AI-driven analytics for leakage prevention in their operational playbooks. Separately, announcements of 5G-enabled metering and growing use of LoRaWAN and cellular hybrids underscore the market’s heterogeneous technology choices. For buyers and vendors alike, these signals are less about technology fetish and more about proof points: successful deployments demonstrate measurable labor reductions, faster detection of non-revenue water, and tangible customer service improvements — outcomes that directly feed procurement ROI templates.
Strategic priorities for each stakeholder group in 2026
- Utilities / Municipalities: Prioritize interoperable architectures, align grant applications with multi-year upgrade windows, and build internal analytics competency to extract value from meter telemetry.
- Vendors / OEMs: Differentiate through integration partnerships (cloud, billing, analytics), support flexible financing models (OPEX options, managed services), and demonstrate field-proven TCO advantages.
- Investors / Private Equity: Target consolidation opportunities in a fragmented market, focusing on bolt-on technologies that deepen analytics or communications capability and improve customer retention.
- System Integrators: Build standardized migration paths for legacy meter replacement, and develop cybersecurity-as-a-service offerings tailored to small- and mid-sized utilities.
How PW Consulting’s study will accelerate your 2026 agenda
The full Smart Water Meters Market report is intentionally pragmatic: it does not merely describe trends but equips delivery teams with templates, playbooks, and decision models to shorten procurement cycles and de-risk rollouts. For executives setting 2026 budgets, the study translates macro growth (9.6% CAGR across 2026–2032) into actionable scenarios, aligning investment size with program maturity, regulatory context, and supplier readiness.
Next steps — a focused call to action
If you are preparing to issue RfPs, negotiate vendor partnerships, or evaluate acquisition targets in 2026, begin with three steps:
- Obtain the full PW Consulting dataset and vendor scorecards to align your sourcing shortlist with both short-term feasibility and long-term upgrade flexibility.
- Run a 0–3 year financial model from our report against your meter replacement schedule to identify funding gaps and grant opportunities that can change project viability.
- Conduct a vendor integration stress test for your billing and outage-management systems to validate interoperability claims before committing to large-scale rollouts.
Closing perspective
Smart water metering is now a core element of utility modernization rather than an optional enhancement. The market’s growth trajectory and fragmentation present opportunities for disciplined buyers and agile vendors to capture disproportionate value. Our study delivers the market intelligence and playbooks necessary to turn meter telemetry into measurable operational and financial outcomes. For boards and executives planning 2026 programs, the choice is straightforward: anchor decisions in rigorous scenario planning, leverage funding and interoperability trends, and use targeted vendor validation to lock in outcomes — the full PW Consulting report provides the data and tools to do exactly that.
For detailed analysis of this topic, please visit the official page: Smart Water Meters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Greenhouse Soil Market Set to Expand at 5.5% CAGR Through 2032
By pmarketresearch, 2026-07-23
Greenhouse Soil Market — Strategic Outlook for 2026: A PW Consulting Preview
Executive teaser
Between 2020 and 2025 the global greenhouse soil market expanded materially, rising from roughly USD 3.64 billion to about USD 4.71 billion as commercial greenhouse adoption and premium substrate demand accelerated. Our 2026–2032 forecast models a steady compound annual growth rate (CAGR) of 5.5%, with the market trajectory pointing to an expected total in the high single‑digit billions by 2032. This preview distills the strategic imperatives we believe every executive in the sector must address in 2026. It demonstrates the depth of our market work while intentionally withholding the granular segmentation tables and proprietary unit economics that appear in the full PW Consulting report.
Greenhouse Soil Market
Why this study is strategically valuable for 2026 decision-making
- Capital allocation under regulatory stress: As peat restrictions and peat‑reduction policies become normative in key markets, capital planning cannot rely on historical raw‑material cost structures. Companies need scenario-backed CAPEX and OPEX projections to prioritize manufacturing flexibility and substrate R&D.
- Sourcing and supply‑chain risk management: Fuel, transport and labor cost inflation has increased the effective landed cost of traditional components. Procurement strategies must shift from spot buying to structured offtake and supplier partnerships.
- Product and channel differentiation: Consumers and professional growers are increasingly paying for verifiable sustainability and performance. Tactical product playbooks will determine who captures margin in premium, organic and climate‑smart segments.
- M&A and partnership timing: With market concentration modest (CR3 ≈ 25.2%, CR5 ≈ 28.4%), the landscape still favors acquisitive scale plays and bolt‑on investments in alternative substrate technologies and distribution networks.
What the full report delivers — practical, decision-ready assets
- Transparent market‑sizing methodology and interactive forecast model (2026–2032) allowing client‑side scenario inputs (raw‑material price shocks, regulatory timelines, and channel mix shifts).
- Segment‑level growth drivers and margin benchmarks for greenhouse‑focused products (including premium potting blends and professional‑grade mixes), with sensitivity matrices for key input costs.
- Supply‑chain heat maps that identify geographic and logistic pinch points for peat, coir, wood fiber, perlite and additives; supplier concentration and counterparty risk scores for contract negotiation.
- Regulatory impact assessments with phased implementation scenarios (short, medium and long timelines) and compliance cost estimates for markets that are already constraining peat use.
- Go‑to‑market playbooks for B2B (commercial greenhouse chains and plant nurseries) and B2C (retail and direct‑to‑consumer) channels, including pricing ladders, packaging recommendations and trade promotion templates.
- Innovation blueprints for peat‑reduction and peat‑free formulations, with R&D roadmaps, pilot designs and KPIs to measure agronomic performance vs. incumbent mixes.
- M&A playbook and target screen: strategic rationale for horizontal consolidation, capability buys (e.g., substrate technology, logistics) and distribution platform rollups.
- Operator checklists and sample RFP language for contract growers, private label agreements and sustainability claims verification.
Competitive landscape: how incumbents and challengers are positioning
The greenhouse soil market is characterized by a mix of large brand names with broad distribution and a long tail of specialized regional suppliers. Several global players dominate headline attention due to their scale, product portfolios and distribution footprints, while numerous regional specialists retain strong relationships with commercial growers.
Greenhouse Soil Market
- Scale and branding leaders: Firms with broad product suites and national retail reach have doubled down on dual strategies — defend commodity potting mixes while investing in premium and organic lines to protect margin. These players benefit from channel leverage but must retrofit product portfolios to satisfy new peat‑related regulations.
- Specialist growers and substrate innovators: Companies focused on high‑performance substrates and alternative fibers are the most attractive acquirers or partners for larger firms seeking to accelerate peat reduction. Their value resides in proprietary formulations, performance data and niche channel access.
- Distribution and partnership activity: Recent distributor agreements and product launches demonstrate active channel reconfiguration. Strategic distributor partnerships can materially shorten time‑to‑market for newly formulated substrates and provide immediate national retail footprint.
For executives benchmarking competitors, the strategic implications are clear: invest in product differentiation and channel orchestration now, or cede margin and customer relationships to those that do.
Greenhouse Soil Market
Regulation, raw materials and cost pressures — dynamics that will define winners
- Regulatory acceleration: Several markets have enacted aggressive peat‑use restrictions for hobby and professional segments. These policies are compressing available supply choices and accelerating commercial demand for alternative substrates.
- Input substitution is not plug‑and‑play: Wood fiber, coir and engineered cellulose substrates are emerging as credible alternatives, but each brings distinct agronomic, handling and cost considerations. Successful substitution requires product re‑engineering, grower education and adjusted logistics.
- Cost and logistics squeeze: Rising fuel and transport costs have increased the effective cost of blended mixes. This dynamic favors local manufacturing, flexible batching systems and vertical integration with feedstock suppliers.
- Policy incentives: In some jurisdictions, climate and agricultural subsidies under recent programs incentivize practices and products that demonstrably reduce emissions or increase soil carbon. These incentives both lower transition costs for growers and create new commercial propositions for suppliers.
Commercial playbook — recommended moves for 2026
Executives should adopt a staged approach that balances quick wins with medium‑term capability building:
- Immediate (0–12 months): Conduct a supplier risk audit and secure multi‑year offtake or contingency agreements for critical feedstocks; launch 1–2 peat‑reduction pilot SKUs with key commercial customers; capture available subsidy funding for pilot projects.
- Near term (12–36 months): Scale successful peat‑reduced formulations, invest in local batching/packaging to cut freight intensity, and negotiate distribution partnerships to accelerate shelf presence. Begin targeted M&A for substrate innovators or regional logistics assets.
- Medium to long term (36+ months): Build modular manufacturing capacity that can switch feedstocks, institutionalize sustainability claims through third‑party verification, and expand into adjacent channels (e.g., professional horticulture services, soil carbon products).
Metrics to track and dashboard priorities
- Feedstock mix by percentage of volume (peat vs alternatives) measured quarterly.
- Gross margin by SKU family and channel with rolling 12‑month view.
- Customer retention and replacement rates following SKU transitions.
- Cost‑to‑serve by distribution lane and packaging format.
- Regulatory compliance exposure by jurisdiction and year.
Where uncertainty creates opportunity
Price volatility, regulatory timelines and raw‑material substitution all increase short‑term uncertainty — and with it, opportunity. Companies that move quickly to secure feedstock diversity, invest in validated alternative substrates, and build flexible logistics will capture disproportionate share of the next growth wave. The market concentration metrics indicate fragmented competition at scale, leaving room for disciplined consolidation and capability buys that can create defensible margin expansion.
How PW Consulting can accelerate your 2026 program
- Custom scenario runs using our interactive 2026–2032 model tailored to your sourcing gaps and product mix.
- Due diligence support for acquisition targets and acceleration plans for post‑merger integration of substrate technologies.
- Operational playbooks for localized batching, quality control for alternative substrates, and distributor negotiation templates.
Final note — this is a strategic preview
This article is designed as a “trailer”: it surfaces the structural forces, competitive dynamics and clear, actionable strategic moves that will matter for 2026 while omitting proprietary segmentation tables, granular regional and application breakouts, and the full set of vendor‑level unit economics contained in our paid study. For executives preparing budgets, negotiating supplier contracts, or evaluating M&A in the greenhouse soil sector, the complete PW Consulting Greenhouse Soil Market report provides the granular data sets, market maps and executable templates needed to translate these insights into measurable outcomes.
Contact PW Consulting or visit our Greenhouse Soil Market study page to access the full dataset, interactive models and practitioner toolkits that support rigorous 2026 decision‑making.
For detailed analysis of this topic, please visit the official page: Greenhouse Soil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EVs for Construction, Agriculture & Mining Poised for 18.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
Electric Vehicles for Construction, Agriculture and Mining: Strategic Preview for 2026 Decisions
Executive snapshot
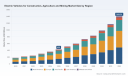
PW Consulting’s market model shows the electrification of heavy off-highway vehicles moving from pilot projects to scalable deployment. The global market for electric vehicles serving construction, agriculture and mining recorded rapid expansion through 2020–2025, rising from approximately USD 181.6 Million in 2020 to USD 428.0 Million in 2025. Driven by regulatory pressure, falling battery costs and OEM product launches, we forecast continued rapid growth through our model horizon: a compound annual growth rate of 18.5% across the 2026–2032 forecast period, taking the market toward roughly USD 1.40 Billion by 2032.
Electric Vehicles for Construction, Agriculture and Mining Market
Why this matters for corporate decision‑makers in 2026
- Capital allocation: The accelerating market growth and defined regulatory windows require firms to decide between early-scale investments (in products, charging and service networks) and staged rollouts to preserve optionality.
- Product strategy: OEMs must reconcile battery vs. fuel‑cell architectures, modularity, and retrofit pathways in product roadmaps to match differing adoption curves across construction, agriculture and mining segments.
- Go‑to‑market and aftersales: Electrified equipment changes dealer economics, spare‑parts mix, and skills requirements. Executives who structure dealer incentives and training in 2026 will gain a multi‑year service advantage.
- Partnerships and energy contracts: Winning customers increasingly depends on bundled energy solutions — charging infrastructure, onsite energy management and power procurement — not just the machine itself.
- Regulatory compliance and procurement readiness: Public and large private buyers are already updating tender specifications for zero‑emission equipment; suppliers without clear compliance strategies will be excluded from key tenders.
Key dynamics shaping 2026 strategy
Several interlocking dynamics will define winners and laggards over the next 24 months. Executives need to understand how each driver alters economics, scaling pace, and competitive behavior.
Electric Vehicles for Construction, Agriculture and Mining Market
- Regulatory push and public procurement
Stringent emissions requirements in Europe and the UK, together with national green procurement targets and standards such as ISO 14001, are moving electrification from voluntary sustainability programs to procurement mandates in many jurisdictions. Project timelines and fleet upgrade cycles must be aligned to these regulatory inflection points.
Electric Vehicles for Construction, Agriculture and Mining Market - Product and production inflection
Large OEMs are transitioning from demonstrators to serial products. High‑profile launches and announced production ramps in 2025–2026 are converting future optionality into near‑term order pipelines. Expect production capacity, battery supply agreements and manufacturing readiness to be decisive for market share in the early scaling phase.
- Battery and charging economics
Battery systems and charging infrastructure remain the primary cost drivers for electric off‑highway vehicles. Total cost of ownership (TCO) comparisons against diesel are now dominated by mid‑life battery replacement assumptions, energy pricing and duty‑cycle matching. Procurement teams who insist on transparent TCO models will capture cost savings and lower operational risk.
- Concentration and competitive pressure
The market exhibits significant concentration at the top: the leading manufacturers command a large share of market value, with high CR3 and CR5 metrics indicating a cluster of incumbents and deep pockets that can accelerate electrification through product, service and capital. New entrants and niche specialists can win in defined use cases but must partner or scale quickly to challenge incumbents economically.
- Infrastructure and grid integration
Charging strategy is both an operational and strategic issue. Sites with constrained grid capacity need integrated solutions — onsite storage, demand management and renewable dispatch. Vendors that offer holistic site solutions will be preferred for large fleet conversions.
Competitive landscape — what matters to investors and OEMs
The competitive map is multi‑layered. Large OEMs with global dealer networks and recent product launches are positioned to win enterprise fleets; regional champions are rapidly electrifying core product lines; specialist manufacturers and startups focus on battery‑native designs and niche use cases. Several practical implications follow:
- Incumbent OEMs
Global players with broad product portfolios and established service networks can leverage production scale and customer relationships to accelerate adoption. Their key strengths are manufacturing depth, aftersales reach and ability to absorb battery supply volatility. However, their incumbent cost structures and distribution models need adaptation for electric models (different spare parts, training and sales cycles).
- Regional and volume players
Manufacturers headquartered in fast‑growing markets are moving early on battery trucks and excavators to protect share in high‑growth domestic demand. They will be important partners for local deployment and can compete on cost and proximity.
- Pure‑play electrification specialists
Smaller, battery‑native firms are advancing product-level efficiency and software ecosystems. These players are often acquisition targets for larger OEMs seeking tech, control software or regional footholds.
- Service and energy partners
Partnerships with energy technology firms and grid operators are becoming standard. Those who can bundle charging, microgrid solutions and financing will redefine value capture beyond the vehicle sale.
Recent industry moves underscore these dynamics: serial production announcements and new electric articulated haulers entering production schedules, mid‑size loader and excavator launches, and strategic partnerships to accelerate charging deployment all signal that 2026 is a decisive year for translating prototypes into recurring revenue.
What PW Consulting’s full report provides (actionable deliverables)
Our market study is structured to support immediate decision cycles in 2026 and beyond. The deliverables are designed for commercial, product and investment teams seeking executable plans rather than high‑level summaries.
- Proprietary market model (base year 2025) with historical time series (2020–2025) and detailed scenario forecasts for 2026–2032 aligned to multiple adoption pathways.
- Transparent methodology and assumptions workbook that lets clients re‑run forecasts under alternate battery cost, energy price and regulatory scenarios.
- Segment‑specific TCO templates and use‑case calculators (fleet transition, retrofit vs. new purchase, battery leasing options) to evaluate payback windows at the site level.
- Regulatory and procurement matrix mapping current policies and future policy risk across major markets, including tender impacts and compliance timelines.
- Commercial playbooks for OEMs and suppliers: GTM segmentation, pricing strategies, dealer incentives, and aftersales transformation roadmaps.
- Supplier and partner scorecards (battery suppliers, power systems, telematics providers), plus an investment horizon for strategic sourcing.
- Competitive profiles and monitoring tracker capturing product launches, production ramps, partnerships and testing programs announced through 2026.
- Risk register and mitigation toolkit covering raw‑material volatility, grid constraints, skills shortages and regulatory shifts.
To preserve commercial value for purchasers, we deliberately omit the detailed regional and application‑level splits from this preview. Subscribers to the full report receive the complete datasets, downloadable models and the raw assumptions behind the headline forecasts.
Practical recommendations for leadership teams in 2026
- Move from pilots to structured scale pilots: define clear KPIs (uptime, TCO, refuelling time, operator training hours) and a two‑year roadmap to evaluate serial product readiness.
- Lock early partnerships for charging and energy management: prioritize partners who can offer site integration (storage, demand response) and capital solutions to smooth adoption costs.
- Recalibrate procurement specs around operational outcomes, not product attributes, to encourage innovative vendor solutions and avoid specification lock‑in to legacy diesel performance metrics.
- Invest in dealer networks and workforce reskilling now; service capability is the silent determinant of customer retention in electric fleets.
- Pursue modular battery and financing models to lower upfront barriers for customers and protect residual value through warranties and second‑life strategies.
- Monitor consolidation and M&A opportunities: specialist electrification firms and energy integrators will be attractive bolt‑ons for OEMs seeking faster capability build‑out.
- Integrate scenario planning into capital budgets using our 18.5% CAGR baseline and downside/upside cases — capital plans should be adjustable to policy and battery price shocks.
Conclusion — the strategic window for 2026
2026 represents a strategic inflection point. Momentum is no longer theoretical: macro policy, OEM production commitments and commercial pilots are converging into real order flows. Firms that combine product readiness with energy partnerships and dealer transformation will capture outsized value as the market scales from mid‑single digits in 2020s revenues to the billion‑dollar opportunity our forecast identifies by 2032.
PW Consulting’s full Electric Vehicles for Construction, Agriculture and Mining Market report contains the datasets, models and operational playbooks required to convert these insights into executable strategies. For clients preparing procurement cycles, product roadmaps or investment cases in 2026, access to the complete dataset and interactive model is the fastest route from insight to implementation.
For detailed analysis of this topic, please visit the official page: Electric Vehicles for Construction, Agriculture and Mining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com