

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Capsule Filling Machines Market to Hit USD 344.8M by 2032 (6.98% CAGR)

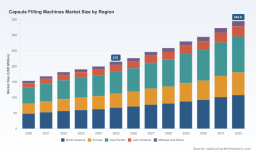
Capsule Filling Machines Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Industry Analyst, I present a concise, decision‑focused preview of our new market study on Capsule Filling Machines. This briefing is designed as a “trailer”: it demonstrates the analytical depth and practical utility embedded in the full report while intentionally withholding granular segmentation tables and proprietary model outputs. If you are evaluating capital expenditure, supplier selection, or M&A moves in 2026, the perspectives and frameworks below will help you prioritize where to dig deeper.
Capsule Filling Machines Market
Market snapshot and trajectory
The global capsule filling machines market is at an inflection point. With a 2025 base year market size of approximately USD 215 million and a compounded annual growth rate (CAGR) of about 6.98% projected through 2032, the industry is expected to approach the mid‑hundreds of millions by the end of the forecast window. This growth is not uniform: it is being driven by a combination of accelerating demand from pharmaceutical and nutraceutical producers, greater automation adoption across contract manufacturers, and expansion of small‑batch / personalized dosing applications. The dynamics create simultaneous opportunities for high‑throughput OEMs and for agile suppliers focused on flexibility and compliance services.
Capsule Filling Machines Market
Why this report matters for 2026 decisions
- CapEx prioritization: Equipments acquired in 2026 must balance throughput, validation effort, and future regulatory expectations—our economic models show typical payback windows and sensitivity to product mix and OEE (overall equipment effectiveness).
- Supplier selection & qualification: Beyond unit cost, regulatory pedigree (cGMP/CE), local service footprint, and spare‑parts certainty will determine long‑term TCO.
- M&A and partnership screening: Fragmentation plus bolt‑on service opportunities create windows for strategic acquisitions—our acquisition filter highlights targets that materially improve scale, aftermarket margin, or regulatory access.
- Product and R&D roadmaps: Firms must choose whether to invest in ultra‑high throughput automation, human‑centric modularity for small runs, or hybrid solutions. We map the risk/reward for each pathway.
- Regulatory readiness: With ongoing enforcement of cGMP, ISO standards, and mandatory reporting regimes, the report provides compliance checklists that reduce project delay risk.
What’s in the full report (practical deliverables)
- Proprietary market model (2020–2032) with scenario runs (base, upside, downside) and an interactive sensitivity layer for pricing, utilization, and SKU mix. Note: detailed regional and application splits are part of the paid dataset.
- CapEx/Opex templates and three bankable financial models for buyers, contract manufacturers, and OEMs—each includes IRR, NPV, and payback based on realistic OEE assumptions.
- Supplier scorecards and procurement RFP/RFQ language calibrated to regulatory and aftermarket needs.
- Operational playbooks: validation & qualification workflows (IQ/OQ/PQ), sanitation regimes consistent with FDA cGMP and ISO guidance, and maintenance schedules tied to MTBF/MTTR benchmarks.
- Service and aftermarket blueprints showing how spare parts, consumables, and remote diagnostics drive recurring revenue and margin uplift.
- Risk heatmaps covering supply‑chain concentration, single‑source components, critical raw material exposures, and regulatory enforcement hotspots.
- Competitive benchmarking and M&A screening tool that ranks targets on technology, regulatory approvals, installed base, and aftermarket revenue potential.
Competitive landscape — strategic read on key OEMs
The market is characterized by a handful of global OEMs with strong engineering pedigrees, a larger tail of regional suppliers, and specialized niche players. Market concentration metrics indicate a fragmented landscape (CR3 and CR5 are both modest, reflecting limited dominance by the largest vendors), which creates both competitive intensity and acquisition opportunities.
Capsule Filling Machines Market
- Syntegon Technology (Heidelberg, Germany) — Strength: high‑volume platform engineering and process integration. Strategic implication: ideal partner for CMOs pursuing highly automated, validated lines where throughput and precision dosing are priority.
- IMA Group (Bologna, Italy) — Strength: rotary/suction bowl technologies with extreme dosing flexibility. Strategic implication: suits customers balancing speed and variety; attractive for firms pursuing global scale in pharma and nutraceuticals.
- MG2 S.r.l. (Milan, Italy) — Strength: modularity and multi‑modal dosing across powders, pellets, and capsule‑in‑capsule formats. Strategic implication: differentiated value for specialty drug forms and customers emphasizing rapid changeover.
- ACG Worldwide (Mumbai, India) — Strength: integrated mid‑market systems with strong cost/benefit tradeoffs and service networks in emerging markets. Strategic implication: strong option for firms expanding production in cost‑sensitive geographies.
- Harro Höfliger (Oberschleißheim, Germany) — Strength: integrated packaging and filling systems optimized for pharmaceutical lines. Strategic implication: attractive to end‑to‑end line integrators and CMOs consolidating vendors.
- Qualicaps (Tokyo, Japan) — Strength: capsule and encapsulation tech with emphasis on compatibility and regulatory documentation. Strategic implication: appeals where capsule chemistry or novel capsule formats are constraints.
- Capsugel (Lonza Group) — Strength: longstanding capsule systems expertise aligned with drug‑delivery science. Strategic implication: premium partner for regulated pharma launches and complex formulations.
- Regional and cost‑competitive suppliers (Torpac, Dott Bonapace, Finetech, Index Capsule Fillers, Feton, etc.) — Strength: flexible offerings, rapid delivery, and favorable price points. Strategic implication: suitable for contract manufacturers, nutraceutical producers, and markets with lower regulatory friction.
Recent product activity illustrates two concurrent innovation vectors: (1) high‑throughput engineering improvements that push the envelope on dosing accuracy and throughput, and (2) human‑centered modular machines optimized for multi‑fill capability and quick changeovers. Examples from late‑2025 product releases point to more integrated weight control systems, enhanced dosing combinations, and a sharpened focus on operator ergonomics—each with direct implications for validation time and service requirements.
Regulatory and compliance dynamics that shape commercial choices
- FDA cGMP enforcement (21 CFR Parts 210 & 211 for pharmaceuticals, 21 CFR Part 111 for dietary supplements) means machines must be sanitary, maintainable, and designed for routine calibration and inspection. Procurement decisions must explicitly budget for validation time and documentation.
- ISO 9001 and ISO 22000 continue to be baseline requirements for manufacturers serving both pharmaceutical and nutraceutical markets; OEM certification status is a gating criterion for many regulated customers.
- DEA reporting requirements and mandated electronic transaction disclosures are non‑negotiable for certain flows—buyers and sellers need controls and IT systems that simplify compliance.
- CE marking and cGMP compliance are essential for market access in regulated regions; equipment without this pedigree increases time‑to‑market and risk of remediation.
Strategic recommendations for executives (short, medium, long term)
- Next 12 months (tactical): Prioritize supplier audits that validate cGMP documentation and spare‑parts SLAs; require factory acceptance tests (FAT) and documented OQ/PQ plans as part of procurement contracts. Consider pilot investments in remote monitoring to reduce unplanned downtime.
- 12–36 months (portfolio optimization): Adopt a two‑track equipment strategy: standardize on high‑efficiency, validated platforms for core SKUs while procuring modular, low‑volume equipment for personalized or niche products. Evaluate bolt‑on acquisitions to secure aftermarket revenue and local service capabilities.
- 36+ months (competitive positioning): Build or partner to deliver integrated line solutions (filling → encapsulation → packaging → serialization) to capture higher margin system sales. Invest in digital twins and predictive maintenance to convert machines into recurring revenue engines.
How PW Consulting helps
Our full Capsule Filling Machines Market report combines an audited market model, validated supplier due diligence, and executable playbooks. For purchasing managers, product heads, and corporate strategists evaluating moves in 2026, we provide the decision‑support tools to: reduce procurement risk, optimize asset allocation, prioritize integrations, and surface high‑ROI M&A candidates. This preview shows the frameworks; the full dataset and granular segmentation that underpin financial models are available through the PW Consulting portal.
To convert industry signals into 2026 actions—whether you are locking capital expenditure, sizing the service business, or screening acquisition targets—access the full report for complete data tables, region‑application breakdowns, and the proprietary M&A screening tool that we intentionally withhold here to preserve actionable exclusivity.
For detailed analysis of this topic, please visit the official page: Capsule Filling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com