

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Radar Level Transmitters Market Poised for 5.69% CAGR (2026–2032)

Radar Level Transmitters Market — Strategic Preview for 2026 Decision-Makers
Introduction
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise strategic preview of our Radar Level Transmitters Market study — a toolkit designed to inform capital allocation, procurement, R&D, and M&A decisions in 2026. The industrial measurement sector is entering a phase where new regulatory regimes, sensor-technology maturation and W-band scale economics intersect to reshape supplier economics and customer requirements. This preview surfaces the high‑impact conclusions and strategic implications while intentionally holding back the granular segmentation tables and scorecards — the premium intelligence our full report delivers.
Radar Level Transmitters Market
Executive snapshot
-
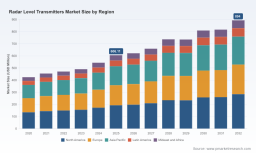
Market trajectory: The radar level transmitters market expanded from a baseline of USD 425 million in 2020 to USD 606.11 million (base year 2025), and is forecast to continue growth under the study’s scenarios, reaching roughly USD 894.0 million by 2032.
Radar Level Transmitters Market -
Growth rate: Our forecast period (2026–2032) assumes a compound annual growth rate (CAGR) of 5.69% — a pace driven by regulatory upgrades, technology substitution (notably 80 GHz solutions), and steady industrial automation demand.
Radar Level Transmitters Market -
Market structure: Concentration is meaningful but not insurmountable — the top three vendors account for under one-third of market revenues (CR3 ≈ 28.5%), while the top five control a majority (CR5 ≈ 53.4%). This dynamic preserves scale advantages for incumbents while leaving clear openings for well‑funded challengers and niche specialists.
Why this study matters to 2026 strategic choices
-
Regulatory inflection points are creating procurement urgency. New European overfill-protection mandates, methane-emission tank-gauging requirements, and certification expectations for water and hazardous applications are converting tentative upgrade cycles into near-term projects for many operators.
-
Technology is consolidating around W‑band (roughly 76–81 GHz) and high-frequency FMCW architectures. These architectures offer measurable accuracy gains, reduced environmental sensitivity, and in many cases lower lifecycle cost — while recent regulatory approvals have accelerated their commercial viability.
-
Scale economics are re-pricing the premium for 80 GHz and W‑band devices. As certification and clearance broaden, price differentials that historically insulated legacy players are shrinking; procurement teams should expect more aggressive commercial terms from manufacturers competing on volume.
-
Connectivity and diagnostics are becoming table stakes. Wireless, Bluetooth, and cloud-enabled diagnostic features (for remote commissioning, predictive maintenance and digital twins) are differentiators for buyers targeting OPEX reductions and uptime improvements.
What the PW Consulting report delivers — practical outputs
Our full study is organized to support direct action. Core deliverables include:
-
Robust market sizing and scenario-based forecasts (2026–2032) with methodology transparency and sensitivity testing to fuel capex planning and ROI analysis.
-
Segmentation frameworks by device architecture (guided‑wave vs. pulsed vs. FMCW), by application (liquids, slurries, interfaces, solids), and by commercial geography — presented as decision-ready dashboards rather than static charts.
-
Competitive benchmarking: vendor scorecards, product feature matrices, channel maps and recent development timelines to inform vendor shortlists and preferred‑supplier negotiations.
-
Regulatory & certification heatmaps that map regions and verticals to certification requirements, enforcement risk and likely early-adopter cohorts.
-
Go‑to‑market playbooks for vendors and procurement playbooks for end‑users — including pilot design templates, total cost of ownership models, and contract clauses to protect against performance drift.
-
M&A and partnership intelligence: target lists and valuation heuristics for roll-up strategies, technology acquisitions and distribution partnerships.
-
Interactive datasets and Excel models that allow scenario adjustments by price, deployment volume, retrofit vs. greenfield mix, and certification time-to-market.
Competitive landscape — strategic observations
The vendor field includes a mix of global systems integrators, instrumentation specialists and focused niche suppliers. Key players analyzed in the report include Emerson, Endress+Hauser, Siemens, ABB, VEGA, KROHNE, Honeywell, Yokogawa, Ametek (Magnetrol), Schneider Electric and several regional specialists. Our analysis identifies three supplier archetypes and their implications for procurement and partnership strategy:
-
Global integrators (e.g., Emerson, Siemens, ABB, Honeywell): Offer broad automation portfolios and strong channel reach. Strengths include system-level integration, large installed bases and bundled service offerings. Watch their tradeoffs: higher TCO for standalone sensing vs. superior lifecycle service contracts and integration risk mitigation.
-
Instrumentation specialists (e.g., Endress+Hauser, VEGA, KROHNE, Yokogawa): Lead on sensing innovation (80 GHz FMCW, hygienic approvals, advanced diagnostics). They are typically first to market on certifications and niche features, making them attractive partners for quality- and compliance‑driven buyers.
-
Niche and regional players (e.g., Magnetrol/Ametek, Nivelco, Kobold, APG): Compete on price, specialized product variants (explosion-proof pulse radar) and rapid local service. These firms are often the source of product-level disruption in regional tenders or in verticals with idiosyncratic needs.
Recent vendor moves reinforce these dynamics: product introductions (new 80 GHz lines from multiple vendors), enhanced certifications for water and hazardous use, and the launch of wireless/non‑contact compact transmitters designed for simplified commissioning. These developments accelerate the substitution of older ultrasonic and legacy radar devices.
Regulation, certification and technology: the nexus for 2026 strategy
Regulation is the single greatest accelerant to near-term demand. Across Europe, tighter overfill-protection and methane-monitoring rules are driving immediate upgrade programs in storage and utilities. Certification milestones — MCERTS, WRAS, ATEX/Ex ia, SIL2/3 — are becoming procurement filters rather than optional marketing badges. On the technology side, FMCW and high‑frequency radar are the instruments of choice for operators seeking accuracy and repeatability in difficult process conditions (foam, dust, interfaces).
Implications:
-
For vendors: Prioritize certification roadmaps and test investments; a validated certification path can unlock entire verticals (e.g., potable water, hazardous petrochemical tanks).
-
For buyers: Reassess retrofit windows — regulatory deadlines create profitable windows for staged upgrades that realize regulatory compliance while optimizing CAPEX schedules.
-
For investors: Look for vendors that combine certification velocity with manufacturing scalability — these firms are best positioned to capture market share as W‑band adoption normalizes.
Actionable recommendations for 2026
-
Start with a regulatory gap analysis. Map assets against applicable overfill, methane and potable-water rules to prioritize retrofit candidates that deliver both compliance and measurable OPEX savings.
-
Favor vendor shortlists that demonstrate both certifiable product roadmaps and digital diagnostics — immediate value accrues from reduced commissioning time and predictive maintenance capabilities.
-
Use staged pilots to de‑risk scale rollout. Pilot in representative process conditions (interface layers, solids handling, foam-prone vessels) and validate vendor diagnostics vs. independent verification.
-
Negotiate lifecycle terms, not only price. Given concentration dynamics, total cost of ownership (service SLAs, spare parts logistics, cloud compatibility) will separate winners from losers.
-
For vendors, prioritize channel partnerships that accelerate certification acceptance in regulated verticals and pursue product modularity to address retrofit complexities.
-
For corporate development teams, monitor mid‑tier specialists with strong certification credentials — these often represent high-value acquisition targets for larger systems integrators seeking to close capability gaps.
How to use this preview
This brief is a strategic précis meant to surface the most consequential forces shaping supplier economics and buyer priorities in 2026. If your team is planning procurement cycles, R&D roadmaps, or M&A pipelines this year, the full PW Consulting Radar Level Transmitters Market study provides the operational detail (segmentation tables, vendor scorecards, contract language templates, and interactive financial models) to convert these strategic directions into executable programs.
To access the full dataset, vendor benchmarking, and actionable playbooks that underpin the conclusions above, consult the PW Consulting market report page and the accompanying interactive workbook. The granular segmentation and vendor scoring — intentionally omitted here — are provided only within the full subscription deliverable to preserve the integrity of the source intelligence and to equip your team with decision-ready materials for 2026 deployments.
For detailed analysis of this topic, please visit the official page: Radar Level Transmitters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com