

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Pressure Transducers Market to hit USD 535M by 2032 (6.5% CAGR)

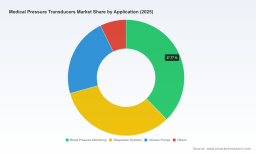
Medical Pressure Transducers Market — Strategic Preview for 2026 Decisions
As PW Consulting’s lead industry analyst, I present a focused strategic briefing on the Medical Pressure Transducers market intended to orient executive decision-making for 2026. This preview synthesizes our new market study’s most consequential signals — macro growth, regulatory pressure points, supplier dynamics, and competitive moves — while preserving the full, segment-level intelligence for clients who access the complete report.
Medical Pressure Transducers Market
Market snapshot: steady growth, concentrated strategic choices
Between 2020 and 2025 the global Medical Pressure Transducers market expanded from a modest base to an established multi-hundred-million dollar market. By our base year (2025) the market reached approximately USD 360 million (revenue unit: Million USD). Our forecasts through 2032 model a compound annual growth rate (CAGR) of roughly 6.5%, with total market value expected to surpass half a billion dollars by the end of the forecast horizon.
Medical Pressure Transducers Market
The implication is straightforward: this is a stable, predictable category with sufficient tailwinds to justify near-term investment, but not a runaway high-growth opportunity. That combination creates distinct strategic imperatives — optimize cost and distribution, shore up regulatory and quality assurance capabilities, and look for incremental share gains via product differentiation or adjacency plays.
Medical Pressure Transducers Market
Why this study matters for 2026 strategy
- Actionable revenue planning: With credible base-year data and a transparent forecasting engine, leadership teams can align 2026 P&L and capex planning to a realistic demand curve rather than aspirational targets.
- Regulatory and procurement timing: Our timing models translate regulatory lead times and hospital procurement cycles into actionable go/no-go gates for product launches, contract renewals, and inventory provisioning.
- M&A and partnership prioritization: The market’s moderate concentration and clear supplier archetypes create identifiable targets for bolt-on acquisitions, channel partnerships, or OEM agreements — but timing and valuation hinge on robust segment-level visibility (available in the full report).
- Supply-chain resiliency: Given the category’s reliance on specialty materials and single-sourced subcomponents, tactical inventory and supplier strategies derived from our scenario analysis materially reduce service interruption risk.
Key market dynamics informing 2026 choices
- Regulatory tightening and certification delay: The EU MDR re-certification timeline has lengthened materially over 2021–2025, with associated costs rising significantly. In practice this means new product launches and EU entry strategies require earlier investment and contingency planning for certification delays.
- FDA Class II governance remains foundational: The regulatory baseline for hemodynamic and invasive blood pressure transducers remains rigorous, with biocompatibility, calibration accuracy, and human factors under close scrutiny. Manufacturers must plan regulatory cycles into product roadmaps and supplier qualification timelines.
- Standards and calibration variability: ISO 80601-2-34 sets performance expectations, but calibration practices vary across hospitals, clinicians, and manufacturers. This creates an opportunity for vendors that can deliver demonstrable, audit-ready calibration processes and training packages as part of their value proposition.
- Materials and sourcing pressure: The bill-of-materials for transducers includes silicon, stainless steels, specialty alloys and medical-grade plastics. Our supplier risk matrix highlights single- and low-source exposures that can produce lead-time spikes and cost inflation during demand surges.
- Compatibility and commoditization risks: Recent product clearances that expand adapter and compatibility options have the potential to commoditize certain transducer accessories, intensifying margin pressure for incumbents who rely on proprietary lock-in.
Competitive landscape — what incumbents and challengers are signaling
The vendor ecosystem is dominated by a mix of established medical device firms and specialized suppliers. The market exhibits a moderate level of concentration: several leading suppliers control meaningful, but not overwhelming, shares — leaving room for disruption and share-shift through commercial excellence or differentiated technology.
- Edwards Lifesciences (Irvine, CA) — Known for the TruWave disposable pressure transducer family focused on invasive hemodynamic monitoring. The product is a clinical staple, but recent adverse-event reporting underscores how quality incidents can rapidly become procurement and reputational risks. Buyers and investors should expect heightened post-market surveillance and possible mitigation costs.
- Smiths Medical (Minneapolis, MN) — Market presence with the TranStar disposable transducer systems; a strong hospital-facing commercial model provides sticky relationships but also exposes Smiths to contract renegotiation pressure as buyers seek cost-efficiencies.
- ICU Medical (San Clemente, CA) — Offers integrated and disposable Transpac systems for critical care; strength lies in integrated solutions and service bundles that span consumables and monitoring platforms.
- Merit Medical Systems (South Jordan, UT) — Meritrans products and disposable systems position Merit as a competitively priced supplier with clinical penetrations in interventional suites; success depends on supply-chain scale and targeted account growth.
- Argon Medical Devices (Plano, TX) — Supplies pressure monitoring lines and transducer kits tailored to interventional procedures; their solutions play well with procedural specialties and create natural adjacency opportunities with catheter-based disposables.
Recent events to factor into 2026 strategy: an FDA MAUDE adverse-event report related to a leading disposable transducer late in 2025 has catalyzed purchasing reviews at several health systems; and a September 2025 510(k) clearance for an IBP transducer adapter cable that is broadly compatible with multiple major brands increases interoperability and potential price competition. Both developments change how procurement teams evaluate vendor risk and total cost of ownership.
What the full PW Consulting report delivers (practical contents)
- Comprehensive market model (historical 2020–2025, base year 2025, forecast 2026–2032) with transparent assumptions and sensitivity toggles.
- Segment-level demand drivers and elasticities (by product archetype and clinical use case) — modeled scenarios for reimbursement, hospital capex cycles, and pandemic-like stresses.
- Regulatory timeline playbook: EU and US clearance paths, expected timelines, estimated costs, and certification gating milestones for 2026 launches.
- Supplier and raw-material risk maps with mitigation checklists (dual-sourcing strategies, contract clauses, inventory policy recommendations).
- Vendor scorecards and commercial benchmarking against clinical adoption metrics and procurement KPIs.
- Transaction-ready diligence templates for M&A (valuation sensitivity tables, integration checklists, and synergy capture pathways).
- Actionable go-to-market modules: pricing elasticity tables, account segmentation frameworks, and sample contracting language to protect margins in interoperable accessory markets.
- Data annex with regulatory events, MAUDE extractions, selected 510(k) logs, and the underlying interview transcripts (anonymized).
How executives should use these findings in 2026
- CEOs and corporate strategists: Use the market model to stress-test M&A targets and to set three-year product roadmaps. Prioritize targets that help mitigate raw-material exposures or add service-driven revenue.
- VPs of product and R&D: Accelerate investments in calibration assurance, human factors, and interoperability; these reduce procurement objections and shorten sales cycles.
- Heads of procurement: Translate the competitive events noted above into RFP clauses that require compatibility, post-market surveillance commitments, and recall/incident response guarantees.
- Finance leaders: Adjust working capital and inventory policies to buffer certification-driven delays and supplier lead-time volatility; model downside scenarios at 1.5–2x the historical lead-time to prepare for regulatory extension risks.
Risk map — prioritized
- Regulatory delay risk: High — EU recertification and nuanced FDA expectations can stall launches and reduce addressable market in the short term.
- Quality & post-market events: Medium-High — Adverse-event disclosures materially affect purchasing decisions, reimbursement support, and brand premium.
- Materials and supplier concentration: Medium — Single-source components create periodic spikes in lead-times and cost; hedging strategies reduce this exposure.
- Commoditization through interoperability: Medium — Cross-vendor adapters and accessories pressure margins for legacy players reliant on proprietary consumables.
Final recommendations — near-term playbook
- Immediately audit supplier exposure for silicon and specialty alloys; implement alternative sourcing pilots with contract provisions linked to lead-time SLAs.
- Prioritize regulatory backlog: if launching in or selling into EU markets, accelerate MDR re-submission plans now to avoid 12–18 month certification slippage.
- Enhance post-market surveillance and clinician-facing calibration support as a commercial differentiator; document training and calibration processes as sale-enablers.
- Evaluate selective interoperability strategies — offer certified adapter bundles to lock-in account penetration while preserving margin through service and training contracts.
- Use the report’s M&A diligence templates to screen targets that either consolidate distribution channels or add control over critical consumable supply chains.
PW Consulting’s full Medical Pressure Transducers Market report provides the granular, segment-level data, country and channel breakdowns, and downloadable modelling workbooks needed to operationalize the playbook above. This preview highlights the signals that should influence 2026 decisions; the complete report contains the actionable datasets and vendor-level intelligence executives require to convert those signals into reliable outcomes.
To access the full datasets, vendor scorecards, and transaction-ready templates, visit the PW Consulting report page or contact your PW Consulting advisor for a confidential walkthrough and tailored scenario analysis.
For detailed analysis of this topic, please visit the official page: Medical Pressure Transducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com