

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metal Material-Based 3D Printing to Expand at 20% CAGR (2026–2032)

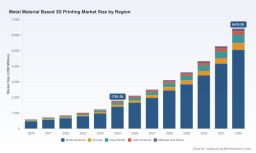
Metal Material Based 3D Printing Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
Between 2020 and 2025 the metal-material-based 3D printing market shifted from a nascent production technology into a commercially materialized industrial platform. Our report uses 2025 as the base year, captures the 2020–2025 historical arc and projects through a 2026–2032 forecast window. At the market level the sector is expanding rapidly — underpinned by a sustained compound annual growth rate of 20% — and the model points to a multi-fold increase in total market value by the end of the forecast horizon. For 2026, this inflection creates a narrow window where choices made by OEMs, material suppliers, integrators and end-users will determine competitive positioning for the remainder of the decade.
Metal Material Based 3D Printing Market
Why this research matters for 2026 strategic planning
-
Decision acceleration: Firms that translate growth trajectories into concrete capacity, qualification and commercialization plans in 2026 will capture disproportionate share during the high-growth phase.
Metal Material Based 3D Printing Market -
Risk prioritization: Rapid expansion amplifies supply chain, certification and technology risks. Our analysis converts those abstract risks into prioritized mitigation paths to protect revenue and time-to-market.
Metal Material Based 3D Printing Market -
Investment discipline: With capital allocation decisions running against a 20% sector CAGR, the report equips boards and corporate development teams to evaluate opportunities with consistent valuation and scenario frameworks.
Market trajectory — what the numbers imply (without spoiling the segmentation)
The market exhibited steady growth in the historical window, accelerating toward the base year as industrial applications moved from prototyping to qualified production. Projecting forward under conservative, base-case and aggressive adoption scenarios, the market continues to compound at roughly 20% annually across 2026–2032. Practically, this dynamic means that supply and qualification capacity that looks sufficient in early 2026 can become a binding constraint within 18–36 months unless addressed proactively.
Key takeaways from the trajectory modeling:
-
Short lead times for equipment and materials will be a competitive asset; lead-time delta translates directly into production share.
-
Qualification-and-compliance investments pay back faster in heavily regulated verticals where traditional supply chains yield to certified additive solutions.
-
Scenario sensitivity to raw-material bottlenecks and certification cycles is material; executives must stress-test procurement, inventory and certification pathways.
Report contents — what executives and practitioners will find
This study is built to be operational rather than purely descriptive. Highlights include:
-
Methodology and transparent assumptions: detailed market sizing algorithms, data sources and modeling logic for reproducibility.
-
Technology-and-material taxonomy: mapping of process families (LPBF, EBM, DED, etc.) to metal feedstocks and performance trade-offs.
-
Go-to-market playbooks: commercialization trajectories for equipment makers, powder suppliers and service bureaus, including pricing dynamics and aftermarket strategies.
-
Supply chain maps and vulnerability assessment: near-term pinch points, strategic inventory levers, and contract structures to de-risk throughput.
-
Regulatory and certification roadmap: step-by-step checklists for ISO/Nadcap compliance and aerospace/defense qualification, with timing estimates and cost-band guidance.
-
Buyer personas and adoption curves: decision-maker profiles across aerospace, medical, industrial and specialty verticals and scenario-based adoption timing.
-
Financial and valuation frameworks: investment case templates, unit-economics models and sensitivity analyses customized for manufacturers, powder producers and service providers.
-
Competitive benchmark appendix: strategic profiles and capability matrices for principal vendors, with relative positioning across scale, materials expertise and software ecosystems.
Competitive landscape — who matters and why
The market concentration metrics indicate a moderate level of aggregation at the top. The largest three suppliers collectively command a meaningful share, and the top five widen that control — an important context when evaluating channel strategies and partnership opportunities.
Core industrial players profiled in the report include established equipment manufacturers, legacy metal producers that are vertically integrating into powders, and specialist system vendors. Briefly:
-
EOS GmbH (Krailling, Germany): A leader in LPBF hardware and an expanding materials portfolio. EOS’s continued material launches and regional investments signal a strategy of vertical breadth and reduced delivery friction.
-
Nikon SLM Solutions (Lübeck, Germany): Focused on large-format LPBF systems for aerospace and defense use cases, with recent software investments to strengthen data-prep and production workflows.
-
Renishaw plc (United Kingdom): Strong in precision systems for aerospace and medical applications; recognized for tight process control and material-system coupling.
-
3D Systems Corporation (United States): Offers a broad portfolio including DMP and ProX series systems and industrial powders, positioning it across prototyping and scaled production.
-
Colibrium Additive (GE Additive) (United States): Integrates EBM and LPBF capabilities, targeting high-performance alloy applications and leveraging GE’s industrial relationships.
-
Material specialists: Höganäs, Carpenter Technology, Sandvik, ATI Powder Metals and others are shifting from upstream metal production toward finer-grained, AM-optimized powders and integrated services.
Recent events captured in the report illustrate strategic moves to secure technology, materials and regional presence. Examples include new material introductions, system orders for naval applications, regional production capacity investments, and next-generation software rollouts — each a signal of directions the market is consolidating around.
Regulation, qualification and certification — the hidden runway
One of the most actionable sections addresses regulatory cadence and qualification pathways. Industrial adoption is now gated less by machine capability and more by material/process qualification frameworks. New ISO standards and Nadcap expectations are creating a turning point: firms that embed certification roadmaps into product development and supply-chain agreements will unlock rate-of-production advantages.
For defense-linked projects, procurement requirements and qualification cycles demand long lead-time planning; the military printing segment is growing at a materially higher CAGR than commercial averages. The implication for 2026 strategies is clear — prioritize certification investments where contract pipelines and margin dynamics justify the upfront effort.
Materials and supply chain — titanium, powders and vertical integration
Titanium feedstock remains a dominant demand driver across aerospace and medical verticals due to its specific strength and biocompatibility. At the same time, metal powder suppliers are expanding capacity and pursuing vertical integration to capture value upstream. Our supply-chain diagnostics identify which raw-material dependencies are most likely to create price or delivery shocks, and outline contractual and inventory approaches to mitigate those shocks.
-
Inventory strategies: recommended buffer levels by risk class, contract clause language samples and alternative-sourcing playbooks.
-
Qualification-as-a-service: how service providers can convert certification expertise into recurring revenue streams.
-
MRO and aftermarket implications: component repair and spare-parts economics for regulated fleets.
Investment, M&A and partnership signals
With a high-compounding growth profile, the sector is ripe for strategic M&A that fills capability gaps (materials, software, qualification services) and extends geographic reach. The report provides action-oriented templates for target screening, valuation premia for certified supply assets, and integration playbooks that anticipate cultural and technical friction points.
How to use this study in a 2026 decision cycle
-
For CEOs and boards: prioritize certification and capacity decisions using the report’s scenario models to avoid late-mover disadvantages.
-
For heads of supply chain: deploy the supply vulnerability index and procurement templates to lock in critical feedstock and reduce lead-time risk.
-
For product and engineering leaders: adopt the technology-material matrix and qualification roadmap to compress validation timelines while preserving compliance.
-
For investors and corporate development: use the M&A playbooks and valuation frameworks to size deals and quantify synergies across the equipment-to-powder stack.
Call to action — the contained value
This briefing surfaces the strategic contours and operational levers that matter in 2026, while protecting the granular segmentation and proprietary scenarios that drive tactical execution. The full report contains the detailed segmentation tables, scenario spreadsheets, vendor scorecards and certification checklists that practitioners need to convert insight into action. Access to the full dataset and appendices will materially shorten your path from decision to deployment.
PW Consulting’s Metal Material Based 3D Printing Market study is designed to be the decision-ready input for corporate planning cycles in 2026. For teams preparing budgets, supply contracts or acquisition screens this quarter, the report provides the empirical backbone and turnkey playbooks necessary to move from strategy to measurable outcomes.
For detailed analysis of this topic, please visit the official page: Metal Material Based 3D Printing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com