

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EVs for Construction, Agriculture & Mining Poised for 18.5% CAGR (2026–2032)

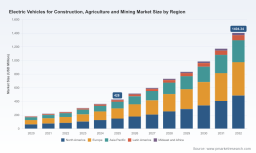
Electric Vehicles for Construction, Agriculture and Mining: Strategic Preview for 2026 Decisions
Executive snapshot
PW Consulting’s market model shows the electrification of heavy off-highway vehicles moving from pilot projects to scalable deployment. The global market for electric vehicles serving construction, agriculture and mining recorded rapid expansion through 2020–2025, rising from approximately USD 181.6 Million in 2020 to USD 428.0 Million in 2025. Driven by regulatory pressure, falling battery costs and OEM product launches, we forecast continued rapid growth through our model horizon: a compound annual growth rate of 18.5% across the 2026–2032 forecast period, taking the market toward roughly USD 1.40 Billion by 2032.
Electric Vehicles for Construction, Agriculture and Mining Market
Why this matters for corporate decision‑makers in 2026
- Capital allocation: The accelerating market growth and defined regulatory windows require firms to decide between early-scale investments (in products, charging and service networks) and staged rollouts to preserve optionality.
- Product strategy: OEMs must reconcile battery vs. fuel‑cell architectures, modularity, and retrofit pathways in product roadmaps to match differing adoption curves across construction, agriculture and mining segments.
- Go‑to‑market and aftersales: Electrified equipment changes dealer economics, spare‑parts mix, and skills requirements. Executives who structure dealer incentives and training in 2026 will gain a multi‑year service advantage.
- Partnerships and energy contracts: Winning customers increasingly depends on bundled energy solutions — charging infrastructure, onsite energy management and power procurement — not just the machine itself.
- Regulatory compliance and procurement readiness: Public and large private buyers are already updating tender specifications for zero‑emission equipment; suppliers without clear compliance strategies will be excluded from key tenders.
Key dynamics shaping 2026 strategy
Several interlocking dynamics will define winners and laggards over the next 24 months. Executives need to understand how each driver alters economics, scaling pace, and competitive behavior.
Electric Vehicles for Construction, Agriculture and Mining Market
- Regulatory push and public procurement
Stringent emissions requirements in Europe and the UK, together with national green procurement targets and standards such as ISO 14001, are moving electrification from voluntary sustainability programs to procurement mandates in many jurisdictions. Project timelines and fleet upgrade cycles must be aligned to these regulatory inflection points.
Electric Vehicles for Construction, Agriculture and Mining Market - Product and production inflection
Large OEMs are transitioning from demonstrators to serial products. High‑profile launches and announced production ramps in 2025–2026 are converting future optionality into near‑term order pipelines. Expect production capacity, battery supply agreements and manufacturing readiness to be decisive for market share in the early scaling phase.
- Battery and charging economics
Battery systems and charging infrastructure remain the primary cost drivers for electric off‑highway vehicles. Total cost of ownership (TCO) comparisons against diesel are now dominated by mid‑life battery replacement assumptions, energy pricing and duty‑cycle matching. Procurement teams who insist on transparent TCO models will capture cost savings and lower operational risk.
- Concentration and competitive pressure
The market exhibits significant concentration at the top: the leading manufacturers command a large share of market value, with high CR3 and CR5 metrics indicating a cluster of incumbents and deep pockets that can accelerate electrification through product, service and capital. New entrants and niche specialists can win in defined use cases but must partner or scale quickly to challenge incumbents economically.
- Infrastructure and grid integration
Charging strategy is both an operational and strategic issue. Sites with constrained grid capacity need integrated solutions — onsite storage, demand management and renewable dispatch. Vendors that offer holistic site solutions will be preferred for large fleet conversions.
Competitive landscape — what matters to investors and OEMs
The competitive map is multi‑layered. Large OEMs with global dealer networks and recent product launches are positioned to win enterprise fleets; regional champions are rapidly electrifying core product lines; specialist manufacturers and startups focus on battery‑native designs and niche use cases. Several practical implications follow:
- Incumbent OEMs
Global players with broad product portfolios and established service networks can leverage production scale and customer relationships to accelerate adoption. Their key strengths are manufacturing depth, aftersales reach and ability to absorb battery supply volatility. However, their incumbent cost structures and distribution models need adaptation for electric models (different spare parts, training and sales cycles).
- Regional and volume players
Manufacturers headquartered in fast‑growing markets are moving early on battery trucks and excavators to protect share in high‑growth domestic demand. They will be important partners for local deployment and can compete on cost and proximity.
- Pure‑play electrification specialists
Smaller, battery‑native firms are advancing product-level efficiency and software ecosystems. These players are often acquisition targets for larger OEMs seeking tech, control software or regional footholds.
- Service and energy partners
Partnerships with energy technology firms and grid operators are becoming standard. Those who can bundle charging, microgrid solutions and financing will redefine value capture beyond the vehicle sale.
Recent industry moves underscore these dynamics: serial production announcements and new electric articulated haulers entering production schedules, mid‑size loader and excavator launches, and strategic partnerships to accelerate charging deployment all signal that 2026 is a decisive year for translating prototypes into recurring revenue.
What PW Consulting’s full report provides (actionable deliverables)
Our market study is structured to support immediate decision cycles in 2026 and beyond. The deliverables are designed for commercial, product and investment teams seeking executable plans rather than high‑level summaries.
- Proprietary market model (base year 2025) with historical time series (2020–2025) and detailed scenario forecasts for 2026–2032 aligned to multiple adoption pathways.
- Transparent methodology and assumptions workbook that lets clients re‑run forecasts under alternate battery cost, energy price and regulatory scenarios.
- Segment‑specific TCO templates and use‑case calculators (fleet transition, retrofit vs. new purchase, battery leasing options) to evaluate payback windows at the site level.
- Regulatory and procurement matrix mapping current policies and future policy risk across major markets, including tender impacts and compliance timelines.
- Commercial playbooks for OEMs and suppliers: GTM segmentation, pricing strategies, dealer incentives, and aftersales transformation roadmaps.
- Supplier and partner scorecards (battery suppliers, power systems, telematics providers), plus an investment horizon for strategic sourcing.
- Competitive profiles and monitoring tracker capturing product launches, production ramps, partnerships and testing programs announced through 2026.
- Risk register and mitigation toolkit covering raw‑material volatility, grid constraints, skills shortages and regulatory shifts.
To preserve commercial value for purchasers, we deliberately omit the detailed regional and application‑level splits from this preview. Subscribers to the full report receive the complete datasets, downloadable models and the raw assumptions behind the headline forecasts.
Practical recommendations for leadership teams in 2026
- Move from pilots to structured scale pilots: define clear KPIs (uptime, TCO, refuelling time, operator training hours) and a two‑year roadmap to evaluate serial product readiness.
- Lock early partnerships for charging and energy management: prioritize partners who can offer site integration (storage, demand response) and capital solutions to smooth adoption costs.
- Recalibrate procurement specs around operational outcomes, not product attributes, to encourage innovative vendor solutions and avoid specification lock‑in to legacy diesel performance metrics.
- Invest in dealer networks and workforce reskilling now; service capability is the silent determinant of customer retention in electric fleets.
- Pursue modular battery and financing models to lower upfront barriers for customers and protect residual value through warranties and second‑life strategies.
- Monitor consolidation and M&A opportunities: specialist electrification firms and energy integrators will be attractive bolt‑ons for OEMs seeking faster capability build‑out.
- Integrate scenario planning into capital budgets using our 18.5% CAGR baseline and downside/upside cases — capital plans should be adjustable to policy and battery price shocks.
Conclusion — the strategic window for 2026
2026 represents a strategic inflection point. Momentum is no longer theoretical: macro policy, OEM production commitments and commercial pilots are converging into real order flows. Firms that combine product readiness with energy partnerships and dealer transformation will capture outsized value as the market scales from mid‑single digits in 2020s revenues to the billion‑dollar opportunity our forecast identifies by 2032.
PW Consulting’s full Electric Vehicles for Construction, Agriculture and Mining Market report contains the datasets, models and operational playbooks required to convert these insights into executable strategies. For clients preparing procurement cycles, product roadmaps or investment cases in 2026, access to the complete dataset and interactive model is the fastest route from insight to implementation.
For detailed analysis of this topic, please visit the official page: Electric Vehicles for Construction, Agriculture and Mining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com