

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Hydraulic Bolt Tensioner Market — USD 211.1M in 2025, 5.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
Hydraulic Bolt Tensioner Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our full Hydraulic Bolt Tensioner Market study. This briefing synthesizes the macro trajectory, competitive posture, regulatory and technical headwinds, and the practical tools procurement, engineering, and corporate development teams will need to act decisively in 2026. The full report contains the granular segmentation, vendor scorecards, and transaction-level scenarios that senior teams require — but this preview intentionally omits those detailed splits to preserve the value of the full intelligence package.
Hydraulic Bolt Tensioner Market
Market trajectory: what the numbers say (and why they matter)
-
The market has demonstrated steady expansion through 2025, rising from approximately USD 163 million in 2020 to about USD 211 million in 2025. Our modeling projects continued growth through the 2026–2032 forecast window, reaching roughly USD 304 million by 2032, at a compound annual growth rate of 5.5%.
Hydraulic Bolt Tensioner Market -
This growth is not uniform; it reflects a combination of steady replacement and aftermarket demand, incremental adoption in wind and power-generation projects, and specialized procurement for subsea and heavy industrial applications. The market’s moderate concentration (CR3 ≈ 35%, CR5 ≈ 45%) signals a mixed competitive environment — established specialist vendors coexist with regional and niche innovators, producing both price and technology differentiation opportunities.
Hydraulic Bolt Tensioner Market -
For 2026 planning, the headline implication is clear: this market is large enough to justify targeted supplier strategies (preferred supplier lists, multi-year contracts, and local stocking), yet fragmented enough to benefit materially from disciplined procurement, technical due diligence, and selective partnerships.
Why this research matters to 2026 corporate decisions
-
Capital allocation: Buyers in oil & gas, wind farm construction, and heavy industry face competing CapEx priorities. Our study converts market dynamics into capital deployment scenarios that demonstrate the total cost of ownership (TCO) trade-offs between single-stage, multi-stage, and subsea-capable tensioners, enabling CFOs to prioritize investments with modeled payback horizons.
-
Procurement & supply continuity: We identify supplier risk vectors (manufacturing concentration, raw-material exposure, and aftersales responsiveness) and provide practical sourcing strategies — e.g., supplier tiering, consignment stocking, and critical-spare pooling — that minimize downtime for high-value flanged joints.
-
Product & service positioning: Product teams and OEMs can use our demand and technology signals to prioritize R&D roadmaps around labor-saving features (spring-return, auto-retract), corrosion-resistant materials for subsea, and modular adapter systems for wind foundations — areas where field efficiency and safety create measurable commercial premiums.
-
M&A and partnership screening: The market’s mid-level concentration presents opportunities for bolt-on acquisitions and joint ventures. We provide a prioritized list of target archetypes — regional manufacturers with aftermarket networks, technology-led specialists in subsea/wind, and service-platform operators — together with valuation multipliers and integration risk heuristics.
Operational contents of the full report (what you’ll get)
-
Transparent market sizing and forecasting methodology with scenario sensitivity (base, upside, downside) mapped to commodity and labor cost swings.
-
Supply chain mapping that traces critical-path components (high-strength stainless fasteners, seals, high-pressure hydraulic components), vendors of record, and single-sourcing risk nodes.
-
Procurement playbooks: RFP templates, SLA clauses, inspection and test plans, spare-parts stocking algorithms, and specification checklists that align with ISO/ASTM compliance requirements.
-
Competitive benchmarking toolkit: vendor capability matrices, win-loss drivers, aftermarket-support scoring, and a repeatable framework for on-site verification of vendor claims.
-
Technical appendix covering tensioning methods, pump interfaces, adapter families, and guidance for integrating tensioners into existing bolting management systems.
-
Regulatory and standards matrix linking product characteristics to compliance points and audit checklists.
-
Executive action templates for M&A diligence, strategic sourcing, and product co-development agreements.
Competitive landscape — strategic read on the core players
Our study profiles the established global specialists and regional challengers shaping competitive dynamics. Below is a high-level synthesis of strategic positioning for the vendors we track (profiles reflect product focus, end-market strength, and strategic implications for buyers).
-
HYTORC (United States) — Deep heritage in hydraulic tensioning with broad adapter interoperability and a strong presence in topside and wind single-stage solutions. Buyers valuing modularity and field-serviceability will find HYTORC’s ecosystem attractive; its product breadth supports integrated service agreements across asset portfolios.
-
TorqLite (United States) — Product portfolio emphasizes return mechanisms (spring-return), wind-specific systems, subsea-ready units with composite seals, and foundation tensioners. TorqLite’s feature-led differentiation reduces onsite labor and safety exposure, making it a compelling supplier for wind operators focused on fast, repeatable foundation bolting.
-
Tritorc (India) — Positioned as a technically rigorous, cost-competitive provider with strong design and documentation updates (recent catalog and technical guides). Their investments in pump performance and load-measurement transparency signal readiness to serve critical oil & gas applications with competitive local manufacturing economics.
-
Atlas Copco (Sweden) — Global OEM strength, breadth across topside, subsea and wind portfolios, and integrated pump systems. Atlas Copco’s strength lies in systems integration and aftermarket service networks — attractive to multinational buyers seeking global single-vendor solutions and predictable lifecycle support.
-
Hydratight (United Kingdom) — Engineering-led supplier with flange-focused series and an emphasis on interchangeable accessories and compliance to established flange standards. Hydratight is well-suited for industrial and energy clients that require engineered, standard-compliant tensioning protocols.
-
Hi-Force (United Kingdom) — Product innovation in subsea quick-fit releases and manual-return safety features. Hi-Force’s product attributes reduce offshore intervention time and align with operators who face high mobilization costs for maintenance campaigns.
-
FPT Fluid Power Technology (Italy) — Strong technical focus on multi-stage solutions for industry-standard flanges. FPT’s serial hydraulic connections and design compliance make it a logical supplier for complex flange geometries and repeatable offshore applications.
-
Technotorc (India) — Specializes in multi-stage tools and high-pressure systems for heavy construction and industrial use; a candidate for partnerships where cost-sensitive projects require robust, high-throughput tensioning.
-
WREN Hydraulics (United States) — Broad bolting portfolio including ultra-high-pressure tensioners, appealing to buyers with extreme-torque and high-precision requirements and those seeking integrated bolting solutions from a single source.
Recent signals and regulatory drivers
-
Vendor innovation is focused on documentation, measurement fidelity, and onsite usability — illustrated by recent catalog and technical updates from regional suppliers that emphasize load-cell accuracy, pump performance, and common faults mitigation.
-
Standards compliance remains a gating factor. ISO 898-1 and ASTM A490M continue to be referenced across product specifications; procurement teams should insist on traceable compliance and test certificates at contract award to avoid field failures and warranty disputes.
-
Materials and labor costs are shaping product selection: stainless and corrosion-resistant builds increase component cost for subsea units, while spring-return and auto-retract designs materially lower onsite labor and safety exposure — two levers with direct P&L consequences for operations-heavy asset owners.
-
Wind foundation projects continue to drive demand for compact single-stage and multi-stage systems that can operate in constrained environments and achieve simultaneous preload on multi-bolt patterns.
Five practical actions for 2026
-
Initiate supplier qualification pilots focused on lifecycle cost not sticker price: include mobilization, spare-parts lead times, and certified inspection intervals in RFPs.
-
Embed standards compliance into payment milestones: condition a portion of supplier payment on delivery of verifiable ISO/ASTM test certificates and witnessed tensioning trials.
-
Prioritize retrofit-friendly adapter systems when standardizing across fleets to reduce future CapEx on tooling and training.
-
Pursue regional manufacturing or stocking partnerships to de-risk subsea and wind projects from long lead times and material-cost volatility.
-
Maintain M&A watchlists of regional OEMs and aftermarket service providers whose local networks and spare-parts inventories can be rapidly integrated to improve service levels.
Closing — how this preview should be used
Think of this briefing as an operational map: it highlights where value is created and where risk concentrates without disclosing the granular segmentation that confers competitive advantage. If you are preparing 2026 budgets, refining your supplier strategy, or assessing M&A targets, the full PW Consulting Hydraulic Bolt Tensioner Market report contains the transactional detail, vendor scorecards, and scenario models required to convert insight into executable decisions.
To unlock the complete dataset, vendor matrices, and procurement-ready templates, please access the full report page or contact PW Consulting’s industry desk for a tailored briefing and data extract optimized for your operating geography and asset mix.
For detailed analysis of this topic, please visit the official page: Hydraulic Bolt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Modular Data Centers Market Poised for 17.11% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
Modular Data Centers Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present this forward-looking introduction to our Modular Data Centers Market study — a decision-ready briefing tailored for C-suite and infrastructure leaders preparing for 2026. The modular data center segment has transitioned from niche tactical deployments to a structural element of enterprise and hyperscale infrastructure strategies. Our study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes market dynamics, competitive positioning, regulatory shifts, and practical playbooks so you can convert market momentum into durable advantage.
Modular Data Centers Market
Market trajectory: what the headline numbers mean
The market has recorded rapid expansion over the past half-decade, rising from approximately USD 16.5 billion in 2020 to roughly USD 36.4 billion in 2025. Looking forward, our model projects continued durable growth through the forecast window to 2032, reaching roughly USD 110 billion. That trajectory implies a compounded annual growth rate of about 17.1% through 2032 — a level that reshapes vendor economics, procurement cadence, and site selection logic for 2026 and beyond.
Modular Data Centers Market
Two immediate strategic implications follow. First, the scale and velocity of this growth mean that modular solutions are no longer an auxiliary option but a primary delivery model for organizations pursuing speed, cost predictability, and scalability. Second, the market concentration profile is meaningful: a moderate-top-tier share by a small number of global suppliers creates both supplier-driven standards and pockets of opportunity for specialized integrators and regional players.
Modular Data Centers Market
Why this research matters to enterprise decision-makers in 2026
- AI and high-density compute as growth multipliers: New high-performance workloads are pushing site-level power and cooling requirements, raising the bar for prefabricated and containerized systems that can be optimized for AI/HPC without prolonged on-site construction cycles.
- Edge proliferation and heterogeneous estates: Enterprises are balancing centralized hyperscale capacity with distributed edge deployments. Modular systems shorten deployment lead times and limit construction risk in geographies with supply-chain or labor constraints.
- Regulatory, safety and standards inflection: Recent updates to standards frameworks and an industry push toward interoperable module designs (including initiatives under major open-hardware projects) mean compliance and standards-readiness are strategic purchasing criteria — not afterthoughts.
- Supply chain and delivery velocity: Prefabrication mitigates some material and schedule risk, but lead times for compute, power and thermal subsystems remain strategic considerations. Strategic sourcing and build partners matter.
What our full report delivers (practical, executable outputs)
- Proprietary market model: multi-scenario forecasts (base, accelerated, conservative) from 2026–2032, with transparent assumptions and sensitivity levers for power density, deployment cadence and regional demand drivers.
- Actionable go-to-market playbooks for buyers and vendors: procurement templates, contracting strategies that preserve flexibility for hardware refresh and modular upgrades, and vendor evaluation matrices.
- TCO and lifecycle modeling tools: CapEx / OpEx tradeoffs for containerized, prefabricated and all-in-one approaches calibrated to typical enterprise and colocation profiles.
- Risk and opportunity heatmaps: site selection criteria, regulatory and standards exposure, supply-chain bottleneck analysis, and mitigation tactics for time-to-market pressure.
- Supplier scorecards and strategic vendor maps: qualitative and quantitative assessment across engineering depth, delivery footprint, integration capability, and aftermarket services.
- Implementation playbooks: deployment sequencing, testing and commissioning checklists, and operational handover templates to reduce time-to-first-workload.
Note: This preview intentionally omits the full detailed breakdowns by region, type and application to preserve the report’s proprietary intelligence. The full dataset, scorecards and downloadable modeling assets are available in the complete PW Consulting report.
Competitive landscape — positioning and practical implications
The market combines global OEMs, systems integrators, and specialist modular fabricators. Three dynamics define competitive moves in 2026: product differentiation around integrated power/cooling/IT modules, speed-to-deployment claims supported by factory-controlled fabrication, and commercial models that align CapEx and OpEx incentives for customers.
- Vertiv: Vertiv’s prefabricated modular solutions target high-performance AI/HPC pockets and large-scale deployments. Their emphasis on integrated power and cooling systems aims to shorten engineering cycles for hyperscalers and service providers.
- Schneider Electric: Schneider’s EcoStruxure approach focuses on adaptable, high-performance modular designs suitable for complex, geographically diverse estates — positioning that favors multinational enterprises and environmentally constrained sites.
- ABB: ABB emphasizes modular scaling for colocation operators, prioritizing repeatable modules that accelerate ROI and simplify capacity expansion for operators seeking fast, bankable deployments.
- Eaton: Eaton’s SmartRack offerings and recent collaboration with Flexnode reflect a tactic of vertically optimizing power and backup subsystems to shave weeks off deployment schedules — a critical differentiator for AI factory projects.
- Flex: Flex positions its AI infrastructure platform as a pre-engineered route to accelerate chassis-to-compute timelines, claiming notable reductions in deployment cycle time via integrated design and assembly practices.
- Dell Technologies: Dell takes a systems-integration stance, modularizing racks and compute to serve edge and high-density environments where standard data center shells are impractical.
- M.C. Dean: With a recent patent covering support rack systems and installation methods, M.C. Dean is moving to protect and scale a differentiated installation approach aimed at campus-style deployments.
- Haskell Modular Solutions: Haskell plays to custom, factory-controlled fabrication, making it attractive where bespoke configurations or fast turnarounds are strategic priorities.
Recent product launches and alliances — including the 2025–2026 spate of product expansions and turnkey edge offerings — underscore a clear market move: vendors are packaging more pre-integrated value (power, cooling, management) to win shorter sales cycles and higher-margin professional services. For buyers, that trend simplifies vendor selection but increases the importance of rigorous vendor due diligence around interoperability, upgrade paths, and lifecycle support.
Regulatory and standards headwinds/opportunities
- Safety and compliance frameworks have been refreshed to address modern prefabricated systems and AI-driven workloads; procurement processes must include compliance verification early in the RFP stage.
- Open-hardware standardization efforts are lowering integration overhead and enabling more modularity across suppliers — a strategic opening for organizations seeking multi-vendor flexibility.
- Patents and proprietary installation methods are becoming differentiators; buyers should balance innovative delivery against lock-in risk.
Strategic recommendations for 2026
- Adopt modular-first sourcing policies for new greenfield and brownfield expansions where speed and repeatability matter; require vendor roadmaps and upgrade pathways in contracts.
- Implement staged pilots for AI/HPC and edge workloads: validate thermal and power management strategies in production-like environments before large rollouts.
- Negotiate service-level contracts that include performance guarantees for integrated power and cooling subsystems, and insist on interoperability clauses tied to open standards where feasible.
- Prioritize partners with factory-controlled manufacturing and proven supply-chain continuity to reduce schedule risk; map critical-path components and create redundancy in procurement plans.
- Use scenario-based TCO models to compare containerized, prefabricated and all-in-one approaches under varying utilization profiles and upgrade cadences.
- Monitor regulatory updates and standards participation (including major open-hardware initiatives) as an input to vendor selection and architecture design.
- For service providers and colocation operators: design modular rolls that support rapid densification and multi-tenant isolation to capture evolving third-party demand.
Use cases shaping buying criteria
Different business objectives imply different modular strategies. Rapidly deployable temporary capacity, edge sites with constrained footprints, AI/HPC facilities requiring dense power/cooling integration, and colocation expansions each place a distinct premium on engineering, factory control, and lifecycle support. Our full report maps these use cases to vendor capabilities and procurement templates to make decision-making operational rather than aspirational.
Concluding perspective — act with speed, but structure for resilience
The modular data center market’s projected near-term scale and high growth rate make 2026 a pivotal year to lock in strategic advantage. The winners will be organizations that treat the modular transition as a systems-design exercise — combining vendor selection rigor, standards alignment, and flexible commercial structures — rather than a one-off procurement. PW Consulting’s full report delivers the quantitative foundations, supplier scorecards, and implementation playbooks needed to convert market momentum into defensible capacity and predictable economics.
This briefing highlights core trends and practical imperatives while withholding the granular segmentation tables, supplier-level metrics, and downloadable forecasting models that our clients rely on for procurement and investment decisions. To access the full dataset, scenario models, and the PW Consulting vendor evaluation toolkit, please visit the report landing page and download the comprehensive Modular Data Centers Market study.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Boat Insurance Market to Reach USD 475 Million by 2032 (CAGR 5.85%)
By pmarketresearch, 2026-07-23
Boat Insurance Market 2026 — Strategic Preview
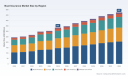
As senior industry analysts at PW Consulting, we present a forward-looking briefing designed to orient executive teams, investors, and insurance strategists as they finalize plans for 2026. The global boat insurance market has demonstrated consistent expansion through the early 2020s, increasing from a measured base in 2020 to an estimated USD 335.0 Million in our base year (2025), and is projected to reach approximately USD 475.0 Million by 2032. Our forecast window (2026–2032) embeds a compound annual growth rate (CAGR) assumption of 5.85% and reflects the combined influence of rising recreational participation, evolving regulatory regimes, and reinsurance market dynamics.
Boat Insurance Market
Why this briefing matters for 2026 decision-making
- Timing: 2026 represents an inflection point where premium adequacy, digital distribution investments, and regulatory compliance choices crystallize into durable competitive advantage.
- Capital allocation: Insurers and reinsurers must decide whether to prioritize underwriting capacity, technology for direct-to-consumer channels, or targeted M&A to shore up exposure in coastal geographies.
- Underwriting & pricing: Post-2025 premium and claims trends mean material premium adjustments are plausible in certain high-exposure states; underwriting frameworks developed now will determine 2026 loss ratios.
Market trajectory and structural signals
PW Consulting’s historical series (2020–2025) shows steady growth into the base year. The forecast period to 2032 anticipates continued expansion driven by multiple demand-side and supply-side vectors: higher boat ownership rates in mature leisure markets, commercial activity in specialty fishing and small commercial craft, and broader adoption of value-added policy features (e.g., event coverage, agreed-value options). At the same time, the market exhibits meaningful concentration: the top three firms account for a substantial portion of capacity, and a top-five concentration figure signals that competitive moves by a handful of incumbents will materially affect national pricing and distribution dynamics.
Boat Insurance Market
Regulatory and risk environment — what’s changed and what to expect
- Liability mandates are shifting at the state level. For example, new legislation introduced in 2025 in South Carolina requires minimum liability coverage for specified watercraft classes and increases enforcement at title/registration—this illustrates the growing willingness of state legislatures to tie insurance to ownership registration. Firms operating in states adopting similar mandates must prepare for accelerated policy issuance and proof-of-coverage workflows.
- Household policy gaps remain significant. Several regulators continue to note that standard homeowners packages provide only limited protection for boats—often insufficient for liability exposure—meaning there is persistent cross-sell opportunity for standalone boat policies and endorsements.
- Catastrophe and reinsurance pressures are compressing capacity in high-exposure coastal states. Market evidence shows that boaters in highly coastal jurisdictions may see premium impacts materially above national averages—insurers should expect location-driven price differentiation to persist or widen in the near term.
Distribution, consumer behavior and pricing signals
Consumer premium data in industry sources indicates an average annual premium band for recreational policies. At the same time, coastal exposures and reinsurance dynamics are producing above-average increases in specific states. These twin facts mean distribution strategies that balance scale (digital direct channels, affinity partnerships) with localized underwriting acuity (agent-based, field-inspection workflows) will perform best. For 2026, management teams must decide how aggressively to invest in real-time quoting technology versus expanding agency networks to capture the uptick in mandatory and voluntary purchases.
Boat Insurance Market
Competitive landscape — reading the movers
The competitive set combines national multiline carriers, specialty underwriters, and emergent tech-first entrants. Legacy insurers with broad P&C footprints continue to leverage brand and agent networks to capture recreational volumes, while specialized marine underwriters and startups are focusing on tailored products for higher-value yachts, commercial fishing fleets, and flexible admitted/excess structures.
- Large multiline carriers: These firms use scale, integrated distribution, and brand trust to secure retail volumes and affinity partnerships. Their priorities are portfolio-level loss control, pricing normalization across states, and cross-sell into homeowners/auto customers.
- Specialty and marine-focused underwriters: These players concentrate on custom coverages (agreed value, equipment endorsements) and niche commercial needs, often tolerating thinner distribution for superior underwriting margins.
- Tech-native entrants: Newer providers are building direct, data-rich platforms and are expanding into strategic states; their playbooks emphasize pricing agility, rapid underwriting via data ingestion, and partnerships with platform distribution partners.
Notable market activity in 2025–2026 highlights how competitive dynamics are evolving: tech-driven entrants expanded admitted and surplus offerings in major boating states, while state-level regulation introduced new compliance requirements that will accelerate the addressable market for insured boaters where proof-of-coverage becomes mandatory.
What our full report delivers (executive-to-operational granularity)
PW Consulting’s Boat Insurance Market report is built for action. We combine top-down market sizing with bottom-up practical modules designed to move teams from insight to execution. Highlights include:
- Actionable market-sizing models (macro scenario paths for 2026–2032) and revenue ladders by product family and end-use application.
- Regulatory impact matrix that maps state-level legislative trends to projected policy uptake and compliance costs, with sensitivity analysis for liability thresholds and enforcement mechanisms.
- Underwriting playbook: data-led risk segmentation, recommended rating variables, claims frequency/severity scenarios, and a reinsurance optimization template for balancing retention, cost, and capacity.
- Distribution ROI calculator: compare acquisition economics for direct digital channels, agency growth, affinity partnerships, and white-label programs using client-provided cost baselines.
- Product design and bundling tests: prototypes for tiered liability, agreed-value endorsements, towing and equipment packages, and special-event coverages that speak to owner demand patterns.
- Claim and fraud analytics guidance: prioritized telematics and inspection investments to reduce frequency and improve salvage recoveries, including sample KPIs and implementation timelines.
- Competitive playbook and M&A diagnostic: capability heat maps that identify targets for capability buy vs. build decisions across underwriting, tech, and geographic presence.
To respect commercial sensitivity and preserve the strategic "teaser" value of this preview, we intentionally withhold core subsegment-level tables and region/application shares here. The full report contains those granulated splits, scenario files, and proprietary scoring models.
Practical strategic implications for 2026
- Pricing & underwriting: Institutionalize a two-track pricing approach—aggressive digital-first pricing to capture low-risk recreational policyholders, and more conservative, underwritten offerings for higher-exposure coastal and commercial craft. Stress-test tariffs against 15–25% reinsurance-driven premium inflation scenarios in coastal states.
- Distribution: Reallocate incremental marketing budgets to tested affinity channels in states with newly mandated insurance proof, and accelerate API-enabled quoting for dealer and marina partners to capture purchase-moment policy issuance.
- Product innovation: Launch modular endorsements that address liability minimums and short-term event needs (e.g., regatta or charter coverage) to monetize episodic usage and the growing shared-economy segment for vessels.
- Claims & loss control: Invest in remote inspection, digital evidence submission, and preventive boater education discounts—these measures reduce loss severity and enable differentiated pricing for safer customers.
- Capital & reinsurance strategy: Reassess treaty structures to manage accumulating coastal exposures; consider quota-share arrangements for new-state expansions where balance-sheet capacity is constrained.
- M&A and partnerships: Target capability acquisitions that accelerate entry into state markets with regulatory uplift or that plug gaps in digital distribution and telematics-enabled underwriting.
Execution checklist for 90–180 days
- Run scenario stress tests on 2026 portfolio plans using the PW Consulting regulatory impact matrix and the reinsurance sensitivity tool included in our report.
- Prioritize data integrations for dealer and marina point-of-sale APIs; pilot real-time issuing in one high-opportunity state before scaling.
- Deploy a targeted agent training and incentive bundle aligned with any state-level liability mandates anticipated to take effect in 2026.
- Evaluate partnership opportunities with specialty marine insurers to co-underwrite exposures above internal capacity thresholds.
Conclusion — where to focus in 2026
The boat insurance market presents a balanced mix of growth opportunity and concentrated risk. Market expansion, regulatory pushes toward mandatory coverage in certain jurisdictions, and reinsurance-driven premium pressure all create an environment where precise underwriting, nimble distribution, and capital-aware expansion will separate winners from followers. PW Consulting’s full Boat Insurance Market report equips boards and senior management with the scenario tools, pricing models, and operational playbooks needed to translate the 2025–2032 trajectory into profitable 2026 outcomes.
For access to granular segmentation, proprietary scoring models, and the full suite of implementation templates, download the complete PW Consulting report or contact our advisory team to arrange a tailored briefing and hands-on scenario workshop.
For detailed analysis of this topic, please visit the official page: Boat Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Dental Drug Market 2026: Strategic Preview for Decision‑Makers
As dental practices, distributors, and pharmaceutical manufacturers plan investments and go‑to‑market strategies for 2026, they need a compact yet rigorous view of where value will accrue in the Dental Drug Market and what tactical levers will protect growth and margins. This Market Research Preview from PW Consulting synthesizes our data‑driven forecast (base year 2025) and scenario work for 2026–2032, highlighting the strategic choices that matter while preserving the full, granular intelligence for subscribers.
Dental Drug Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 is a hinge year. Our model uses 2025 as the base and integrates five years of historical dynamics (2020–2025) to produce a forward projection across 2026–2032. That makes the report directly actionable for FY‑2026 planning, capital allocation, and M&A diligence.
Dental Drug Market -
Scale and growth profile: The Dental Drug Market is a multi‑billion dollar segment with mid‑single‑digit compounded expansion over the forecast horizon. PW Consulting’s centralized market model projects continued expansion through 2032 at an expected CAGR of 6.2%, reflecting persistent clinical demand, product innovation, and evolving distribution models.
Dental Drug Market -
Market structure: Concentration is meaningful but not prohibitive—our analysis shows a moderate market concentration with the top three and top five players accounting for a material minority of overall revenues. That structural balance creates defensible niches for incumbents and attractive entry points for focused challengers.
Headline quantitative context (selected)
-
Base year (2025) market scale: the market is measured in the mid‑thousands of Million USD globally (base year 2025). Our year‑on‑year model traces the sector from the historical 2020–2025 period into the 2026–2032 forecast window, peak testing multiple macro, regulatory and supply scenarios.
-
Near‑term movement: the model flags a notable rebound entering 2026 as clinics normalize supply chains and new product listings mature in distribution channels. Readers seeking the detailed year‑by‑year tables and model inputs should consult the full report.
What the full report contains (practical deliverables)
-
Integrated market model: an interactive, scenario‑driven forecast (2026–2032) with Monte Carlo sensitivity on demand drivers, pricing, and adoption curves.
-
Commercial playbook: prioritized go‑to‑market strategies for manufacturers, distributors, and clinic groups—covering pricing, bundling, and catalog strategies suitable for global and regional rollouts.
-
Competitive benchmarking: a structured scorecard comparing product portfolios, channel strength, manufacturing footprint, and R&D pipelines for the major market participants.
-
Regulatory and payer risk matrix: mapping of likely regulatory interventions, reimbursement shifts, and cost‑pressure timing across key developed markets.
-
Supply‑chain stress tests: scenario analysis for raw‑material shocks, labor constraints in specialized cartridge filling and QC, and contingency sourcing routes.
-
M&A and partnership targets: screening of acquisition candidates and collaboration structures, with financial return ranges and integration risk estimates.
-
Operational playbooks for clinics and distributors: SKU rationalization, inventory policies, cold chain practices, and training frameworks to accelerate adoption of new dental drug formulations.
Strategic themes shaping 2026
-
Portfolio prioritization toward anesthetics and procedural adjuncts: Demand for procedural anesthetics and peri‑operative agents remains the backbone of dental drug volumes. Our strategic advice is to optimize SKU portfolios—trade off marginal SKUs for scale on core formulations and premiumized, convenience packaging that supports clinic throughput.
-
Distribution as a differentiator: Firms with deep, integrated distribution networks (digital catalogs, direct sales to group practices, and wholesaler partnerships) will convert product innovation into share gains faster. Catalog expansions by major distributors in 2025 demonstrate how shelf‑space and logistics investments translate into 2026 ordering behavior.
-
Supply resilience and API strategy: Securing reliable APIs and specialized filling capacity for cartridges and local delivery systems is non‑negotiable. Labor intensity in QC and filling increases the value of near‑term investments in automation and vendor diversification.
-
Regulatory and payer volatility: The evolving U.S. reimbursement landscape and high regulatory fees for clinical applications raise the bar for launches. Manufacturers must budget both higher regulatory costs and the possibility of negotiated price pressure in core markets when modeling returns.
-
Innovation focused on analgesic alternatives: Interest in non‑opioid dental analgesics and improved injection formulations continues to attract strategic capital—recent equity and board moves in the segment highlight continued investor appetite for differentiated clinical value propositions.
Competitive landscape: what to watch in 2026
The competitive field combines specialized manufacturers, global diversified health‑science conglomerates, and broad dental distributors. PW Consulting’s competitor maps classify firms along three axes: product depth in dental pharmaceuticals, distribution reach into dental practice networks, and capability in regulated drug manufacturing.
-
Specialist manufacturers: Companies with a focused product set around local anesthetics and topical anesthetics retain strong margins and clinical trust. These players often lead on product innovation and rapid clinic adoption.
-
Diversified industrial players: Firms that integrate dental pharmaceuticals into wider oral‑care portfolios benefit from cross‑sell and bundling but must manage internal resource allocation to preserve competitiveness in the specialized dental drug segment.
-
Distributors and service platforms: Large dental distributors control catalog placement and clinic access. Their 2025–2026 catalog and platform updates will determine which product suppliers see accelerated penetration in office channels.
Recent strategic moves illustrate the market logic. Strategic investments by specialty manufacturers into drug innovators signal an acceleration of R&D partnerships and an industry focus on next‑generation injection drugs and analgesics. Expanded supplier catalogs show distributors leaning into assortment leadership to capture clinic share.
Regulatory and macro dynamics to monitor
-
Drug price negotiation and payer pressure: New negotiation frameworks and payer strategies may change pricing dynamics for selected medicines—manufacturers should stress‑test launch and pricing plans against negotiated price scenarios and assess the behavioral effects on clinic procurement.
-
Regulatory cost inflation: Updated fee schedules for clinical applications and filing pathways materially change launch economics; firms pursuing clinical trials must model higher fixed costs into their go/no‑go decision gates.
-
Workforce and production economics: The labor‑intensive nature of cartridge filling, QC, and regulated manufacturing places a floor under cost structures that can compress margins in commodityized product lines; capital investments in automation will be decisive.
-
Reimbursement headwinds and beneficiary savings dynamics: Changes that reduce payer cost exposure can create public savings while compressing manufacturer pricing power—balanced strategies that combine value demonstration with operational efficiency will be favored.
Recommended strategic moves for 2026
-
Refine portfolio to “best‑in‑class” products: Prioritize clinical and commercial investment in the subcategories that deliver the most durable margin and adoption advantages. De‑emphasize low‑velocity SKUs where distributor discounts erode returns.
-
Lock down supply continuity: Negotiate multi‑year API agreements, identify secondary fill partners, and quantify conversion costs to alternative formulations. Include labor and QC variability in S&OP models.
-
Negotiate distribution exclusives and hybrid channels: For differentiated new formulations, secure preferential listings with major catalogs while piloting direct digital channels into group practice networks.
-
Price defensibility and evidence generation: Invest in pragmatic trials and real‑world evidence that demonstrate downstream clinic efficiencies—shorter chair time, reduced retreatment rates, or decreased ancillary medication use—to justify premium positioning.
-
M&A and partnership playbook: Target bolt‑on assets that either expand manufacturing scale in controlled environments or add clinically differentiated molecules that meet emerging clinic needs (e.g., opioid‑sparing analgesics).
How this preview maps to the full PW Consulting study
This preview frames the strategic implications: scale, growth trajectory (6.2% CAGR through the forecast window), concentration dynamics, regulatory pressures, and competitive archetypes. The full report delivers the operational detail and raw data required to execute—complete year‑by‑year market tables, granular segmentation matrices, supplier and plant‑level risk assessments, and executable commercial plans. We have intentionally withheld the full segmentation detail and proprietary model outputs here to channel readers to the comprehensive dataset and tactical annexes available with the report.
Next steps for executives
-
Use this preview to align leadership around the high‑impact choices for 2026: portfolio trimming, supply‑chain resilience, distribution alignment, and evidence generation.
-
Acquire the full PW Consulting Dental Drug Market report to access: downloadable models, granular regional and product segmentation, competitive dossiers, and a prioritized action roadmap for 12–36 month execution.
-
Engage with our advisory team for a tailored 48‑hour strategy sprint: scenario modeling customized to your portfolio and an actionable 90‑day rollout plan for the highest‑impact initiatives.
PW Consulting’s Dental Drug Market study is designed to bridge the gap between boardroom questions and executional realities in 2026. For the full datasets, segmentation tables, and tactical playbooks that power investment memos and commercial strategies, consult the complete report and our advisory services.
For detailed analysis of this topic, please visit the official page: Dental Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Torsional Vibration Damper Market — USD 1,800M in 2025, 5.5% CAGR (2026-2032)
By pmarketresearch, 2026-07-23
Torsional Vibration Damper Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a forward-looking briefing designed to orient executives, investors and product leaders preparing decisions in 2026. This preview synthesizes the structural forces, competitive dynamics and near‑term scenarios shaping the global torsional vibration damper (TVD) market. It demonstrates the type of rigorous, actionable intelligence contained in our full market study — while intentionally withholding the granular segment tables and proprietary model outputs that are included in the report itself.
Torsional Vibration Damper Market
Why this research matters for 2026
- Market inflection: The TVD market is past a commodity-only phase and is entering a technology-differentiation window driven by downsized high-torque engines, hybrid powertrains and stricter NVH and emissions standards.
- Timing: With our base year set at 2025 and the formal forecast window 2026–2032, 2026 is the pivot year for decisions on new product investments, capacity reconfigurations and M&A execution if firms want to capture the next wave of demand.
- Practical outcomes: This study is built to support procurement negotiations, R&D roadmaps, aftermarket strategies and investor due diligence — with scenario-tested revenue, margin and sensitivity tables that speak to near-term capital allocation choices.
Market trajectory — the macro story
Our macro model shows the global TVD market expanding steadily. After a historical rise from around USD 1,200 Million in 2020 to USD 1,800 Million in 2025 (base year), we forecast continued growth through 2032, with the global market reaching approximately USD 2,800 Million by 2032. That implies a compound annual growth rate (CAGR) of roughly 5.5% over the 2026–2032 forecast period. In short: after recovery and consolidation, the market is in a multi-year growth phase driven by NVH regulation, powertrain transitions and industrial vibration control demand.
Torsional Vibration Damper Market
Two additional macro observations shape near-term strategy:
Torsional Vibration Damper Market
- Growth is not linear across technologies and applications — engineering sophistication and OEM integration needs are amplifying value capture for differentiated suppliers.
- Volatility in upstream input costs and OEM price pressure mean margin resiliency will be earned through product differentiation, scale and supply-chain design, not through volume alone.
Competitive landscape — what the leaders are doing
The market exhibits modest concentration, with global incumbents holding meaningful OEM relationships while a broader set of specialized players compete on technology, customization and aftermarket service. Leading firms profiled in our study include Vibracoustic SE, Vibratech TVD, Schaeffler AG, ZF Friedrichshafen AG, Continental AG, Hasse & Wrede, Dayco, American Engineering Group (AEG), Geislinger, BorgWarner, Trelleborg, Valeo, Sumitomo Riko and LuK. Below are strategic snapshots drawn from publicly available company activity and our primary interviews.
- Vibracoustic SE (Weinheim, Germany) — Deep OEM reach and breadth across elastomeric and fluid dampers. Their recent unveiling (Feb 2026) of multi-stage rubber elastomer technology signals a move to capture broader engine speed ranges and to compete where multi-modal damping is required. Expect them to press for long-term OEM contracts where they can trade technological IP for scale commitments. ( https://vibracoustic.com)
- Vibratech TVD / Fluidampr (Springville, NY, USA) — Niche leader in viscous solutions, with strong presence in high-performance, off-highway and stationary power markets. Their 2025 technical webinar on next‑generation viscous dampers underlines a product-led push into downsized high-torque ICEs and hybridized applications — markets that place a premium on thermal stability and long-term viscous performance. ( https://www.vibratechtvd.com)
- Schaeffler AG & ZF Friedrichshafen AG — Both companies leverage systems-level integration (transmissions, dual-mass flywheels, PTOs). They favor solutions that are integrated into broader powertrain modules, creating higher switching costs for OEMs and prioritizing customers seeking single‑supplier simplicity. ( https://www.schaeffler.com; https://www.zf.com)
- Hasse & Wrede — A specialist and world market leader in viscous shear-type dampers for engines and compressors. Their recent trade show activity and product availability on specific compressor platforms reflect a strategy of focusing on high-value industrial applications where switching costs and certification barriers protect margins. ( https://www.hassewrede.com)
- Aftermarket and diversified suppliers (Dayco, Continental, BorgWarner, Valeo, Trelleborg) — These players balance OEM contracts with independent aftermarket offerings, enabling them to monetize installed-base service and to provide complementary NVH systems to OEMs looking to outsource non-core modules. Dayco’s 2025 severe-duty aftermarket expansion is an example of targeting long-tail revenue in heavy-duty segments. ( https://www.dayco.com; https://www.continental.com)
- Smaller specialists (AEG, Geislinger, Sumitomo Riko, LuK) — These firms compete through niche design innovations (dual elastomer systems, tuned steel spring dampers, elastomeric composites) and tight OEM certification paths in specific geographic clusters.
Recent corporate activity in 2025–early 2026 highlights two parallel playbooks: (1) product-innovation and technical evangelism for viscous and multi-stage elastomer solutions; and (2) aftermarket and industrial-targeted expansions to capture non-automotive demand. Both approaches are viable — selection depends on a firm’s scale, certification capability and capital tolerance for long OEM lead times.
Industry dynamics and risk factors
- Raw material volatility — Petrochemical-driven swings in elastomer and silicone-based fluid costs are increasing input-cost variability. Our cost-sensitivity models show that without pass-through mechanisms or design efficiencies, margins can compress materially in high-cost cycles.
- Regulation and certification — Accelerated NVH and emissions standards (tightening at roughly mid-single-digit annual rates in many mature markets) are raising certification burden and testing costs. Suppliers without robust testing and validation capabilities will struggle to win long-term OEM frames.
- OEM price pressure and labor cost dynamics — Sustained OEM price-reduction programs are compressing margins for commoditized suppliers. Labor cost inflation and the need for low-cost manufacturing footprints create a two-edged challenge: price competition versus reliability and certification demands.
- Technology shift risks — Electrification reduces some torsional vibration requirements on pure-EV drivetrains but introduces new NVH profiles (e.g., high-frequency torque pulses, inverter-induced vibrations). The winners will be firms that can translate engine-era competence into electric drivetrain NVH solutions.
What the full PW Consulting report provides (operational, purchase-ready intelligence)
The full study goes beyond high-level trends to provide the operational inputs executives need to act in 2026:
- Validated market sizing and high-granularity forecasts (2026–2032) across product technologies and end-use buckets with sensitivity scenarios based on input-cost and regulation shocks.
- Supplier and OEM matrix mapping technology fit‑for‑purpose, qualification timelines, and switching-cost profiles (essential for procurement negotiation timelines).
- Detailed go‑to‑market playbooks for aftermarket entrants, OEM integrators and niche suppliers, including target account lists, certification roadmaps and cost-to-certify models.
- Capital allocation and M&A screening framework: valuation multipliers observed across recent deals, integration risk checklists, and a prioritized list of tuck‑ins relevant to each strategic archetype.
- Practical engineering briefs on multi-stage elastomer design, viscous fluid formulations temperature durability and service-life prediction models — intended to align R&D sprints with commercialization windows.
- Supply-chain and procurement tactics to mitigate elastomer fluid-cost volatility and to structure OEM contracts for shared risk on raw-material inflation.
Note: In keeping with the preview principle, detailed sub-segment volumes and regional breakdowns are reserved for the full report and interactive dashboards available on our source page.
Strategic implications and recommended 2026 actions
For executives deciding in 2026, our analysis yields a concise decision framework:
- If you are an OEM supplier with scale: prioritize multi-stage elastomer and integrated flywheel/damper systems that raise switching costs. Invest in localized validation centers to shorten qualification timelines.
- If you are a viscous-specialist: lean into performance claims for high-torque, downsized engines and industrial compressor markets where certification barriers and performance differentiation protect margins.
- If you are an aftermarket or diversified supplier: accelerate severe-duty and installed-base service offerings — aftermarket growth can materially improve utilization and dampen OEM margin pressure.
- If you are an investor or M&A strategist: target bolt-on assets that supply certification capability, specialized materials know-how, or captive industrial end-markets; avoid buying into pure-volume plays without engineering IP or OEM feed-in agreements.
- All players should: implement input-cost hedging, incorporate NVH-certification cost into bid economics, and stress-test product roadmaps for EV-era NVH profiles.
Closing perspective
The torsional vibration damper market in 2026 is a classic strategic inflection: predictable macro growth (CAGR ~5.5% through 2032) combined with shifting technical requirements and margin pressures that reward technology and execution. Our full PW Consulting report is designed to convert these dynamics into executable plans — with granular models, supplier scoring, and playbooks that can be used immediately in procurement, R&D prioritization, and M&A diligence.
For executives who want the underlying datasets, segment tables, company scorecards and interactive scenario models that support these conclusions, consult the full report and dashboards on our publication page. The granular intelligence that will inform contract terms, R&D funding and capacity decisions in 2026 is only a click away.
For detailed analysis of this topic, please visit the official page: Torsional Vibration Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Bank Information Systems Market USD 947M in 2025, 7.8% CAGR
By pmarketresearch, 2026-07-23
Blood Bank Information Systems Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
As healthcare organizations confront increasingly stringent traceability and safety requirements, the Blood Bank Information Systems (BBIS) market has moved from niche operational tooling to a strategic infrastructure layer. Our market model, calibrated to a 2025 base year and spanning historical performance (2020–2025) with a forward-looking forecast to 2032, shows a sustained expansion at a compound annual growth rate (CAGR) of 7.8%. The market that approached the billion-dollar threshold in 2025 is projected to exceed USD 1.5 billion by 2032 (figures in USD Million). This trajectory is driven by regulatory imperatives, digitization of transfusion workflows, and cloud-first deployment economics.
Blood Bank Information Systems Market
Why this matters for 2026 strategic planning
For hospital systems, national blood services, ISVs and investors planning actions in 2026, BBIS decisions are no longer confined to feature checklists. They intersect with enterprise architecture, compliance risk, and supply-chain resiliency. The 2026 planning cycle will determine which organizations lock in legacy constraints and which adopt more flexible, audit-ready platforms capable of supporting multi-site operations, donor-to-recipient traceability, and analytics-driven inventory optimization.
Blood Bank Information Systems Market
Key market trajectory — high-level numbers
-
Historical expansion: The market grew steadily from the 2020 baseline through 2025, reflecting accelerating adoption and replacement cycles among blood banks and transfusion services.
Blood Bank Information Systems Market -
Near-term inflection: 2026 marks the start of the forecast horizon in our study. The market crosses the billion-dollar mark in the immediate year and continues an upward path through 2032, reflecting compounding investments in compliance, digital workflows and cloud migration.
-
Long-term opportunity: By 2032 the market size is projected to be materially larger than the 2025 base, underscoring durable demand for integrated BBIS capabilities across healthcare ecosystems.
Report scope — what the study delivers
This research is designed as an operationally actionable guide for executives and program owners. Highlights include:
-
Validated market sizing (2020–2025 historical; 2026–2032 forecast) expressed in USD Million, with scenario sensitivity to regulatory and technology adoption variables.
-
A pragmatic vendor evaluation framework that scores solutions across safety/traceability, interoperability, deployment architecture (on-premise vs cloud), and total cost of ownership (TCO) over 5–7 year horizons.
-
Decision-ready playbooks for procurement teams: RFP templates, risk-adjusted cost models, migration timelines, and success metrics for phased rollouts in multi-facility environments.
-
Integration blueprints for EHR/LIS connectivity and point-of-care allocation, plus recommended KPIs to monitor compliance, utilization and product shelf-life optimization.
-
Scenario analyses for strategic options: in-house modernization, vendor consolidation, managed services, and M&A targets — each with quantified impacts on operational KPIs and compliance risk.
Market dynamics and regulatory drivers
The BBIS market is being reshaped by policy and clinical safety requirements as much as by technology. Two regulatory trends are particularly material in 2026 planning:
-
Traceability mandates: Regulatory agencies now require full donor-to-recipient traceability and audit-ready records. Systems must provide end-to-end documentation that can withstand regulatory scrutiny without creating significant manual workarounds.
-
Real-time auditability: In several jurisdictions, legislators and regulators expect electronic, real-time audit trails as part of Substances of Human Origin (SoHO) compliance frameworks. That raises the bar for data model design, retention policies, and incident response workflows.
Operationally, survey and industry data indicate that regulatory compliance is the primary driver for BBIS upgrades across blood centers — a factor cited by a substantial majority of centers as the leading justification for investment. At the same time, cloud deployments continue to reshape cost structures: they reduce upfront capital expenditure and permit elastic scaling of inventory and traceability services, enabling more sophisticated workflows without commensurate hardware investments.
Competitive landscape — who sets the standard
The vendor environment balances specialized BBIS providers, broader healthcare IT platforms, and niche modules. Market concentration remains modest: the top three and top five firms together account for under half of the market, indicating room for both consolidation and regional specialization. That concentration profile drives specific strategic choices for buyers and investors:
-
Specialist vendors combine deep blood-bank provenance with modular suites tailored to transfusion workflows. Examples include longstanding players whose solutions emphasize inventory control, point-of-care allocation and traceability.
-
Larger healthcare IT platforms embed BBIS functionality within broader EHRs and enterprise suites — attractive to integrated delivery networks seeking single-vendor stacks and tighter clinical interoperability.
-
There is a growing cohort of cloud-native and web-enabled solutions that prioritize rapid deployment, central management and API-first interoperability, appealing to multi-site blood services and national programs.
Representative vendor profiles (high level):
-
Haemonetics — modular suite emphasizing inventory control, traceability and safe transfusion workflows at the point of care.
-
WellSky — transfusion systems with strong EHR/LIS integration and compliance tooling; recent updates (early 2026) introduced new kit-management features focused on inventory and workflow optimization.
-
SCC Soft Computer — web-based BBIS showcased at international conferences in 2025 and 2026, reinforcing its commitment to global best practices and market education.
-
Mediware Information Systems — modular transfusion service management with compliance-centered features and integration capabilities.
-
Cerner (as part of large EHR platforms) — embedded blood bank workflows within broader electronic health record solutions, enabling tighter clinical-process integration.
Recent vendor moves and what they imply
Two tactical developments illustrate vendor positioning in 2026:
-
Feature rollouts that emphasize kit and inventory optimization signal vendors are prioritizing operational efficiency alongside safety. These features reduce waste, improve traceability and shorten turnaround times for critical transfusion decisions.
-
Trade show and conference investments reflect a push to drive global uptake and professionalize BBIS procurement. Vendors are increasingly using live demonstrations and interoperability showcases to de-risk buyer decisions.
Strategic implications and recommended actions for 2026
For enterprise leaders evaluating BBIS directions in 2026, our analysis yields a compact set of recommendations:
-
Prioritize compliance-first roadmaps: Ensure any short-listed system demonstrably meets traceability and audit-readiness requirements in your regulatory jurisdictions. Compliance gaps are the leading source of downstream cost and risk.
-
Model TCO across deployment options: Cloud architectures reduce capex but introduce operational and governance nuances. Build multi-year TCO and vendor-lock-in scenarios into procurement evaluations.
-
Insist on interoperable architectures: Integration with EHRs, laboratory information systems and point-of-care devices must be tested with realistic data and workflows before procurement commitments.
-
Use vendor scorecards and pilot outcomes to drive phased rollouts: Pilots should measure waste reduction, transfusion safety events, cycle-times, and regulatory audit readiness. Translate pilot KPIs into contract SLAs.
-
Explore consolidation or partnership where scale matters: Given the market’s current concentration profile, there are opportunities — and risks — in market consolidation. Assess whether to invest in internal capabilities, partner with a specialist, or pursue M&A to accelerate market entry.
How PW Consulting’s report supports your 2026 agenda
This study is structured to be directly executable by strategy teams:
-
Market sizing and scenario models ready for sensitivity analysis (regulatory tightening, cloud adoption rates, capital availability).
-
Vendor benchmarking tools that translate functional capabilities into procurement scorecard metrics and negotiation levers.
-
Implementation playbooks with timelines, resource plans and governance checkpoints for single-site and multi-site rollouts.
-
Regulatory mapping that aligns local requirements to system capabilities, minimizing compliance surprises during deployment and audit.
Methodology and transparency
The report uses a blended methodology: primary interviews with blood center operators and vendor product teams, a review of regulatory publications, and quantitative triangulation against historical adoption curves. The base year is 2025, historical tracking covers 2020–2025, and forecasts extend 2026–2032 in USD Million. The model is openly documented so decision teams can re-run scenarios with internal assumptions.
Final note — a teaser, not the full map
We have intentionally framed this briefing to reveal the market direction, regulatory imperatives, vendor positioning and the practical levers available to 2026 planners — while withholding the granular regional, application and type-specific breakdowns that are critical to detailed procurement and investment decisions. Those granular splits, vendor-specific scorecards and downloadable executable models are included in the full PW Consulting report and accompanying data pack.
For teams that must convert 2026 strategy into executable programs — from procurement and integration to M&A and product roadmap prioritization — the full report provides the datasets, vendor evaluations and playbooks needed to move from decision to delivery. Contact PW Consulting or visit our report page to access the complete analysis, model files and procurement templates.
For detailed analysis of this topic, please visit the official page: Blood Bank Information Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Combine Harvesters Market to reach USD 180M by 2032 at 4.5% CAGR
By pmarketresearch, 2026-07-23
Combine Harvesters Market 2026 — Strategic Preview for Executive Decision‑Makers
As PW Consulting’s senior industry analyst, I present a concise yet high‑impact preview of our Combine Harvesters Market research — a practical intelligence package designed to inform capital allocation, product strategy, and M&A decisions in 2026. Our model tracks the global market through a detailed historical window (2020–2025, base year 2025) and projects through 2032. Key macro context: the market expanded from approximately USD 120 million in 2020 to USD 145 million in 2025 and is forecast to reach roughly USD 180 million by 2032, growing at a compound annual growth rate of about 4.5%. This trajectory signals steady expansion, tempered by episodic demand shocks and margin compression risks that we unpack below.
Combine Harvesters Market
Why this study matters for 2026 corporate strategy
2026 is shaping up to be a fiscal inflection point for OEMs, suppliers, dealers, and investors in the combine harvester ecosystem. The market’s mid‑single‑digit CAGR masks sharp heterogeneity across technology adoption, customer segments, and aftermarket economics. Executives facing 2026 budget cycles will need evidence‑based guidance on five core questions:
Combine Harvesters Market
- Where should limited CAPEX be concentrated — new platforms, electrification/autonomy, or service networks?
- How do we manage near‑term demand volatility without sacrificing long‑term positioning?
- Which technology partnerships or acquisitions improve competitiveness fastest?
- What pricing and financing structures will sustain replacement cycles amid rising unit prices and component cost pressure?
- How can dealers and OEMs monetize the high‑margin aftermarket and telematics opportunities?
Our report translates the market’s macro growth profile and recent market signals into decision templates that answer these questions pragmatically.
Combine Harvesters Market
Critical market dynamics shaping 2026 decisions
- Demand volatility: Retail metrics in early 2026 show abrupt swings in unit sales, with a notable drop in self‑propelled combine retail activity in the U.S. in April 2026. This underscores the need for flexible production and inventory strategies to avoid overcapacity or lost sales during seasonal and macroeconomic shifts.
- Labor scarcity accelerates automation: North American and other advanced agriculture markets report persistent labor shortfalls during harvest windows, driving stronger interest in autonomous and assisted‑operation systems. Expect accelerated spend on autopilot, Machine‑Sync solutions, and retrofit autonomy kits.
- Policy and subsidy tailwinds: Programs that incentivize eco‑friendly machinery upgrades are altering replacement economics; targeted subsidies can shorten payback periods for higher‑efficiency models and support premium positioning for “green” product variants.
- Aftermarket economics and operating cost pressures: High maintenance costs for premium machines and elevated component prices are reshaping lifecycle value capture. For many operators, service, parts, and telematics will eclipse initial equipment margins as the primary long‑term value stream.
- Pricing and capital intensity: The unit price range for new self‑propelled combines places meaningful strain on working capital and operator financing, creating openings for OEMs and financiers to capture value through innovative leasing and rental models.
Competitive landscape — practical takeaways
We profile the major OEMs and analyze how their strategic moves will influence competitive dynamics in 2026:
- John Deere (Moline, IL) — Leadership in automation and systems integration. Deere’s S‑Series and X9 platforms, combined with machine‑level automation and Machine Sync capabilities, position the firm to capture operators prioritizing productivity gains and reduced labor dependence. Strategic implication: competitors must match systems‑level value or specialize where Deere’s scale is less relevant.
- CLAAS (Harsewinkel, Germany) — Scale and production efficiency. CLAAS’s recent production milestones highlight manufacturing depth and platform breadth. For strategic planning, CLAAS’s advantage is speed to market for incremental model refreshes and special editions; rivals should respond with differentiated service models or targeted niche product excellence.
- CNH Industrial (Amsterdam) — Power and large‑farm focus. CR‑series machines target high‑throughput operations. CNH’s decision levers in 2026 will likely emphasize uptime guarantees and integrated fleet solutions for large ag customers — a template for value capture beyond unit sales.
- AGCO (Duluth, GA) — Brand portfolio and channel strength. AGCO’s multi‑brand approach provides flexibility across customer segments. Dealers and channel partners should refine inventory strategies to balance entry and premium offerings across brands.
- Kubota (Osaka, Japan) — Specialization and autonomy for small holders. Kubota’s strong presence in rice and small‑grain harvesters and its work on autonomous units offer a counterpoint to large‑scale OEMs: mobility into underserved smallholder markets with low‑footprint autonomous solutions.
Across the competitive set, the clearest strategic paths are: (1) double down on software and service‑aligned revenue; (2) expand retrofit and autonomy retrofit ecosystems; and (3) explore partnerships to manage component supply and electrification workstreams.
Where the value pools will be between 2026 and 2032
With the marketplace growing at a mid‑single‑digit rate, the largest near‑term profit pools will not necessarily be in incremental unit sales. Our analysis highlights three high‑leverage plays:
- Aftermarket services and parts: High maintenance cost structures open opportunities for OEMs and third‑party service networks to monetize uptime and predictive maintenance offerings.
- Autonomy and software as a service: Operators show strong willingness to pay for solutions that lower labor needs and improve yield capture during narrow harvest windows.
- Financing, rental and subscription models: Given high unit costs and working capital constraints, flexible ownership models will accelerate adoption and smooth demand cycles.
OEMs that capture these services early can offset unit price pressure, improve customer lifetime value, and create sticky revenue streams.
Report contents — what you get (practical deliverables)
The PW Consulting Combine Harvesters Market report is structured to be immediately actionable. Highlights include:
- Comprehensive market model: Full historical series (2020–2025) and forward projections to 2032 with scenario toggles for demand shocks, subsidy adoption, and technology diffusion.
- Decision‑grade scenario analysis: Stress tests that quantify outcomes under rapid autonomy adoption, raw material inflation, and steep retail contractions.
- Competitive playbooks: Company‑level strategic options, capability gaps, and three‑year priority roadmaps for OEMs, suppliers, and dealers.
- Commercialisation toolkit: Go‑to‑market templates for launching retrofit autonomy, subscription financing plans, and aftermarket service bundles.
- M&A and partnership heatmaps: Screening matrices to identify bolt‑on targets by capability (software, telematics, parts network) and suggested valuation frameworks.
- Supply‑chain stress tests: Component concentration analysis and procurement hedging strategies to defend margins during raw material shocks.
- Operational dashboards: KPI sets for production flexibility, dealer inventory, and service network productivity to align operations with evolving demand patterns.
This package blends quantitative modelling with practitioner playbooks so finance, product, and commercial teams can move from insight to execution within 90 days.
Actionable recommendations for 2026 planning cycles
- Prioritize cash‑light growth: Focus near‑term investments on software, retrofit kits, and dealer enablement rather than broad capital expansion given sales volatility.
- Accelerate autonomy pilots: Target high‑labor‑stress regions and large operators for pilot programs to validate value capture before full platform rollouts.
- Monetize aftermarket: Reconfigure service offerings into outcome‑based contracts (uptime, throughput) to lock in recurring revenues.
- Refine financing propositions: Launch or expand rental and subscription models to lower customer entry barriers and level seasonal demand.
- Strengthen supply resilience: Secure strategic supplier relationships and hedges for critical components to protect margins when raw material costs spike.
Data caveats and the next step
Our preview deliberately surfaces high‑value insights while withholding granular segmentation tables and certain proprietary splits — by design. The full PW Consulting report includes the complete regional and application breakouts, dealer channel economics, and an interactive model that allows you to toggle assumptions and export decision scenarios. If your 2026 plans hinge on detailed regional allocations, product mix levers, or acquisition screening with precise financials, access to the full dataset and model is essential.
For executives preparing budget submissions, product roadmaps, or M&A mandates this year, our research converts market growth projections and observed market signals into executable options. The global combine harvester market’s steady growth to 2032 offers clear upside, but unlocking it requires decisive moves in software, services, and flexible commercial models. PW Consulting’s full report provides the granular inputs and exercise‑ready tools to make those choices with confidence.
To obtain the full report and interactive forecast model, contact PW Consulting’s industry practice or visit our report page for licensing and analyst briefings.
For detailed analysis of this topic, please visit the official page: Combine Harvesters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HF Acid Market to Reach USD 4,405 Million by 2032 at 5.15% CAGR
By pmarketresearch, 2026-07-23
Hydrofluoric Acid Market 2026: Strategic Primer for Executive Decision-Making
As companies plan capital allocation and supply-chain strategy for 2026, hydrofluoric acid (HF) is resurfacing as a material strategic risk and commercial opportunity. PW Consulting’s latest market study — grounded in a 2020–2025 historical series and a 2026–2032 forecast — synthesizes the demand drivers, supply-side shocks, regulatory inflection points and competitive positions that will determine winners and losers in the HF value chain. This primer distills the report’s highest-value insights to inform board-level discussions, while intentionally withholding detailed segment tables and plant-level exposures that are included in the full research deliverable.
Hydro Fluoric Acid Market
Market trajectory at a glance
Our base-year snapshot (2025) shows a global HF market approximately USD 3,093 million (USD Million, base year 2025), following steady expansion from about USD 2,500 million in 2020. Momentum into 2026 projects a market exceeding USD 3,240 million, with an expected compound annual growth rate (CAGR) of roughly 5.15% through 2032, when the market is modeled to surpass USD 4,400 million. The near-term acceleration reflects recovery and reinvestment across fluorochemicals, specialty refrigerants and industrial applications; the longer-term curve is driven by electronics demand, material substitution, and evolving environmental constraints.
Hydro Fluoric Acid Market
Why HF matters for 2026 corporate strategy
- Feedstock criticality: HF is not a generic commodity — it is a feedstock for fluorochemicals, specialty refrigerants, aluminum processing and electronics manufacturing. Short-term availability or quality disruptions ripple rapidly through downstream product lines.
- Concentrated supply base: Industry concentration means a small group of producers exerts meaningful influence over accessible supply and pricing. A focused commercial strategy — with contingency for supplier risk — is therefore non-negotiable.
- Regulatory and social license risk: Emerging regulatory actions and public-health scrutiny are elevating operational and reputational risk for producers and users alike.
Supply and raw-material dynamics shaping 2026
Two linked upstream dynamics are especially material. First, fluorspar — the primary source of fluorine inputs — experienced a modest global production contraction in 2025. Second, import/export flows have shifted meaningfully in recent quarters: certain markets have seen sharp increases in imports amid local mining disruptions and safety-driven rectification. These dynamics collectively compress the short-term buffer that typically cushions HF production, making import dependencies and logistics resilience critical inputs to procurement strategy.
Hydro Fluoric Acid Market
For North American buyers, recent trade flows underscore exposure concentration: a dominant share of HF imports originated from a single neighboring supplier market in late 2025. That pattern creates a vulnerability to trade-policy shifts, route-specific logistics incidents and seasonal demand spikes.
Regulation and public policy — immediate watchpoints
- State-level product rules and toxic-substances lists have moved to the center of HF risk. A prominent U.S. state agency initiated rulemaking in mid-2026 to designate cleaning products containing HF as a priority product — a development with potential downstream implications for formulators and distributors.
- Parallel to product-level action, several producers are undertaking capacity rationalization or site exits as part of corporate restructuring. These closures tighten available global HF capacity and require buyers to reassess contracted volumes and alternate sources.
- Environmental health scrutiny and emergency-response obligations are growing. For producers, enhanced community engagement, capital earmarked for containment and emergency preparedness will increasingly be treated as cost of doing business.
Competitive landscape — what the major players reveal
The HF market is served by a mix of global integrators, regional specialists and niche suppliers. Leading players combine feedstock integration with downstream fluorochemical platforms; others focus on aqueous blends and specialty grades for industrial customers. Key strategic profiles to consider:
- Large integrated producers: Global chemical majors operate high-capacity plants that supply both anhydrous and aqueous HF grades and feed integrated fluorochemical chains. Their strategic advantage is operational scale and the ability to prioritize internal feedstock flows.
- Regional high-purity specialists: Certain Asian and European producers distinguish themselves through high-purity product lines tailored to electronics and specialty etching applications, supported by localized technical service and just-in-time logistics.
- Aqueous and customized-blend suppliers: Regional distributors and manufacturers provide tailored aqueous concentrations and localized supply, emphasizing safety compliance and shorter lead times for industrial markets.
Understanding each supplier’s commercial priorities — export orientation, captive downstream demand, and willingness to supply third parties under spot or contract terms — is critical to shaping procurement strategies and negotiating resilient contracts.
Recent industry events that should change your 2026 plans
- A regulatory initiative in mid-2026 to list certain HF-containing consumer cleaning products as priority items highlights how state-level actions can cascade into commercial restrictions and heightened compliance costs for formulators and retailers.
- Corporate restructuring and site exits announced in the past 12–18 months will remove optionality in specific corridors, necessitating earlier and more diversified sourcing decisions for buyers.
- Industry thought leadership by regional suppliers on trust and domestic-supply advantages underscores an emergent commercial narrative: buyers are increasingly willing to trade unit-cost savings for supply assurance and regulatory alignment.
Strategic implications and recommended actions for 2026
Time horizon matters. Actions that reduce risk in the next 12 months differ from those that create advantage across the 2026–2032 forecast period.
- Near-term (0–12 months): Secure rolling contracts with dual-sourced supply clauses, institute inventory-buffer optimization tied to scenario-based stress tests, and renegotiate freight terms to protect against route-specific shocks. Prioritize suppliers with demonstrable contingency plans and transparent quality systems.
- Medium-term (12–36 months): Evaluate co-investment in local blending or small-scale production to reduce import exposure; incorporate supplier scorecards that weight regulatory resilience and community acceptance; and audit downstream conversion processes to optimize HF consumption efficiency.
- Strategic portfolio decisions (36+ months): Consider partnerships or M&A to secure upstream fluorspar access or HF production capacity, and develop differentiated product offerings based on high-purity or low-environmental-impact credentials aligned with decarbonization and substitution trends.
Operational playbook highlights included in the full report
To support executable decisions, our full study contains granular tools and templates oriented to procurement, operations and corporate strategy teams. These include:
- Supply-risk heatmaps and supplier scorecards (including operational, regulatory and reputational dimensions).
- Scenario-based supply-demand models and price path simulations for 2026–2032.
- Contract playbooks with recommended clauses for force majeure, diversion rights, and environmental compliance pass-through.
- Plant-level risk assessments and emergency-response benchmarking templates.
- M&A screening criteria for upstream feedstock and downstream integration opportunities.
Each tool is calibrated to the market’s expected growth trajectory and to contemporary regulatory pressures. The full report also includes an annex of company profiles and links to primary sources used in our analysis.
How to think about commercial negotiation in 2026
Market tightening and regulatory uncertainty mean price will not be the only leverage in negotiations. Buyers should shift to a total-cost-of-supply framework that captures inventory carrying costs, regulatory compliance expenses, logistics risk premiums and the cost of potential supply restoration. Contract structures that combine volume-flexibility, pre-agreed escalation mechanics and operational transparency (e.g., supplier audits, third-party monitoring) will outperform spot-only strategies in both cost and continuity.
What PW Consulting’s research delivers (and what we intentionally withhold here)
We designed this study to be immediately actionable for executives. The report provides:
- Validated historical market sizing (2020–2025) and a detailed forecast model (2026–2032) with scenario outputs.
- Plant-level exposure matrices, regional flow maps, and application demand curves for downstream sectors.
- Competitive intelligence dossiers on leading suppliers, including strategic intent indicators and likely response scenarios to supply shocks.
- Regulatory and raw-material monitoring dashboards that flag rulemaking, trade-flow shifts and mine production notices.
- A prioritized list of tactical and strategic initiatives tailored to buyer, producer and investor profiles.
To preserve the commercial value of the study and to respect proprietary supplier data, this primer omits full regional and application splits, plant-level capacities and specific contractual language — all of which are available in the subscription report and accompanying datasets.
Immediate next steps for executive teams
- Run a 30–60 day rapid diagnostic using the report’s supplier scorecard to identify single-source exposures and critical-path dependencies.
- Convene a multi-disciplinary steering committee (procurement, operations, HSE, legal) to stress-test existing contracts against the regulatory scenarios highlighted in this study.
- Prioritize small-scale resilience investments — alternate blending capability, buffer inventory, and logistics redundancies — that can be executed within a single budget cycle.
The hydrofluoric acid market is entering a period where strategic foresight, not short-term spot savings, will determine operational continuity and margin stability. PW Consulting’s full study equips decision-makers with the data, scenarios and playbooks to make those calls confidently in 2026.
Accessing the full intelligence
If your 2026 planning cycle requires the detailed tables, regional and application breakdowns, plant-level risk heatmaps and supplier scorecards referenced above, we invite you to consult the complete Hydrofluoric Acid Market report on our website or contact PW Consulting for a briefing. The full dataset contains the granular numbers and scenario models necessary to translate the strategic imperatives summarized here into executable plans.
For detailed analysis of this topic, please visit the official page: Hydro Fluoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com