

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydraulic Bolt Tensioner Market — USD 211.1M in 2025, 5.5% CAGR (2026–2032)

Hydraulic Bolt Tensioner Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
As PW Consulting’s lead industry analyst, I present a concise, decision-focused preview of our full Hydraulic Bolt Tensioner Market study. This briefing synthesizes the macro trajectory, competitive posture, regulatory and technical headwinds, and the practical tools procurement, engineering, and corporate development teams will need to act decisively in 2026. The full report contains the granular segmentation, vendor scorecards, and transaction-level scenarios that senior teams require — but this preview intentionally omits those detailed splits to preserve the value of the full intelligence package.
Hydraulic Bolt Tensioner Market
Market trajectory: what the numbers say (and why they matter)
-
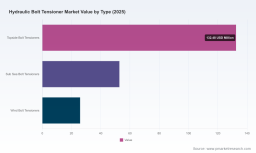
The market has demonstrated steady expansion through 2025, rising from approximately USD 163 million in 2020 to about USD 211 million in 2025. Our modeling projects continued growth through the 2026–2032 forecast window, reaching roughly USD 304 million by 2032, at a compound annual growth rate of 5.5%.
Hydraulic Bolt Tensioner Market -
This growth is not uniform; it reflects a combination of steady replacement and aftermarket demand, incremental adoption in wind and power-generation projects, and specialized procurement for subsea and heavy industrial applications. The market’s moderate concentration (CR3 ≈ 35%, CR5 ≈ 45%) signals a mixed competitive environment — established specialist vendors coexist with regional and niche innovators, producing both price and technology differentiation opportunities.
Hydraulic Bolt Tensioner Market -
For 2026 planning, the headline implication is clear: this market is large enough to justify targeted supplier strategies (preferred supplier lists, multi-year contracts, and local stocking), yet fragmented enough to benefit materially from disciplined procurement, technical due diligence, and selective partnerships.
Why this research matters to 2026 corporate decisions
-
Capital allocation: Buyers in oil & gas, wind farm construction, and heavy industry face competing CapEx priorities. Our study converts market dynamics into capital deployment scenarios that demonstrate the total cost of ownership (TCO) trade-offs between single-stage, multi-stage, and subsea-capable tensioners, enabling CFOs to prioritize investments with modeled payback horizons.
-
Procurement & supply continuity: We identify supplier risk vectors (manufacturing concentration, raw-material exposure, and aftersales responsiveness) and provide practical sourcing strategies — e.g., supplier tiering, consignment stocking, and critical-spare pooling — that minimize downtime for high-value flanged joints.
-
Product & service positioning: Product teams and OEMs can use our demand and technology signals to prioritize R&D roadmaps around labor-saving features (spring-return, auto-retract), corrosion-resistant materials for subsea, and modular adapter systems for wind foundations — areas where field efficiency and safety create measurable commercial premiums.
-
M&A and partnership screening: The market’s mid-level concentration presents opportunities for bolt-on acquisitions and joint ventures. We provide a prioritized list of target archetypes — regional manufacturers with aftermarket networks, technology-led specialists in subsea/wind, and service-platform operators — together with valuation multipliers and integration risk heuristics.
Operational contents of the full report (what you’ll get)
-
Transparent market sizing and forecasting methodology with scenario sensitivity (base, upside, downside) mapped to commodity and labor cost swings.
-
Supply chain mapping that traces critical-path components (high-strength stainless fasteners, seals, high-pressure hydraulic components), vendors of record, and single-sourcing risk nodes.
-
Procurement playbooks: RFP templates, SLA clauses, inspection and test plans, spare-parts stocking algorithms, and specification checklists that align with ISO/ASTM compliance requirements.
-
Competitive benchmarking toolkit: vendor capability matrices, win-loss drivers, aftermarket-support scoring, and a repeatable framework for on-site verification of vendor claims.
-
Technical appendix covering tensioning methods, pump interfaces, adapter families, and guidance for integrating tensioners into existing bolting management systems.
-
Regulatory and standards matrix linking product characteristics to compliance points and audit checklists.
-
Executive action templates for M&A diligence, strategic sourcing, and product co-development agreements.
Competitive landscape — strategic read on the core players
Our study profiles the established global specialists and regional challengers shaping competitive dynamics. Below is a high-level synthesis of strategic positioning for the vendors we track (profiles reflect product focus, end-market strength, and strategic implications for buyers).
-
HYTORC (United States) — Deep heritage in hydraulic tensioning with broad adapter interoperability and a strong presence in topside and wind single-stage solutions. Buyers valuing modularity and field-serviceability will find HYTORC’s ecosystem attractive; its product breadth supports integrated service agreements across asset portfolios.
-
TorqLite (United States) — Product portfolio emphasizes return mechanisms (spring-return), wind-specific systems, subsea-ready units with composite seals, and foundation tensioners. TorqLite’s feature-led differentiation reduces onsite labor and safety exposure, making it a compelling supplier for wind operators focused on fast, repeatable foundation bolting.
-
Tritorc (India) — Positioned as a technically rigorous, cost-competitive provider with strong design and documentation updates (recent catalog and technical guides). Their investments in pump performance and load-measurement transparency signal readiness to serve critical oil & gas applications with competitive local manufacturing economics.
-
Atlas Copco (Sweden) — Global OEM strength, breadth across topside, subsea and wind portfolios, and integrated pump systems. Atlas Copco’s strength lies in systems integration and aftermarket service networks — attractive to multinational buyers seeking global single-vendor solutions and predictable lifecycle support.
-
Hydratight (United Kingdom) — Engineering-led supplier with flange-focused series and an emphasis on interchangeable accessories and compliance to established flange standards. Hydratight is well-suited for industrial and energy clients that require engineered, standard-compliant tensioning protocols.
-
Hi-Force (United Kingdom) — Product innovation in subsea quick-fit releases and manual-return safety features. Hi-Force’s product attributes reduce offshore intervention time and align with operators who face high mobilization costs for maintenance campaigns.
-
FPT Fluid Power Technology (Italy) — Strong technical focus on multi-stage solutions for industry-standard flanges. FPT’s serial hydraulic connections and design compliance make it a logical supplier for complex flange geometries and repeatable offshore applications.
-
Technotorc (India) — Specializes in multi-stage tools and high-pressure systems for heavy construction and industrial use; a candidate for partnerships where cost-sensitive projects require robust, high-throughput tensioning.
-
WREN Hydraulics (United States) — Broad bolting portfolio including ultra-high-pressure tensioners, appealing to buyers with extreme-torque and high-precision requirements and those seeking integrated bolting solutions from a single source.
Recent signals and regulatory drivers
-
Vendor innovation is focused on documentation, measurement fidelity, and onsite usability — illustrated by recent catalog and technical updates from regional suppliers that emphasize load-cell accuracy, pump performance, and common faults mitigation.
-
Standards compliance remains a gating factor. ISO 898-1 and ASTM A490M continue to be referenced across product specifications; procurement teams should insist on traceable compliance and test certificates at contract award to avoid field failures and warranty disputes.
-
Materials and labor costs are shaping product selection: stainless and corrosion-resistant builds increase component cost for subsea units, while spring-return and auto-retract designs materially lower onsite labor and safety exposure — two levers with direct P&L consequences for operations-heavy asset owners.
-
Wind foundation projects continue to drive demand for compact single-stage and multi-stage systems that can operate in constrained environments and achieve simultaneous preload on multi-bolt patterns.
Five practical actions for 2026
-
Initiate supplier qualification pilots focused on lifecycle cost not sticker price: include mobilization, spare-parts lead times, and certified inspection intervals in RFPs.
-
Embed standards compliance into payment milestones: condition a portion of supplier payment on delivery of verifiable ISO/ASTM test certificates and witnessed tensioning trials.
-
Prioritize retrofit-friendly adapter systems when standardizing across fleets to reduce future CapEx on tooling and training.
-
Pursue regional manufacturing or stocking partnerships to de-risk subsea and wind projects from long lead times and material-cost volatility.
-
Maintain M&A watchlists of regional OEMs and aftermarket service providers whose local networks and spare-parts inventories can be rapidly integrated to improve service levels.
Closing — how this preview should be used
Think of this briefing as an operational map: it highlights where value is created and where risk concentrates without disclosing the granular segmentation that confers competitive advantage. If you are preparing 2026 budgets, refining your supplier strategy, or assessing M&A targets, the full PW Consulting Hydraulic Bolt Tensioner Market report contains the transactional detail, vendor scorecards, and scenario models required to convert insight into executable decisions.
To unlock the complete dataset, vendor matrices, and procurement-ready templates, please access the full report page or contact PW Consulting’s industry desk for a tailored briefing and data extract optimized for your operating geography and asset mix.
For detailed analysis of this topic, please visit the official page: Hydraulic Bolt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com