

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Modular Data Centers Market Poised for 17.11% CAGR (2026–2032)

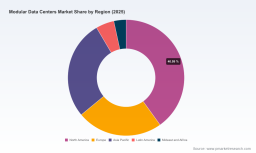
Modular Data Centers Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present this forward-looking introduction to our Modular Data Centers Market study — a decision-ready briefing tailored for C-suite and infrastructure leaders preparing for 2026. The modular data center segment has transitioned from niche tactical deployments to a structural element of enterprise and hyperscale infrastructure strategies. Our study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes market dynamics, competitive positioning, regulatory shifts, and practical playbooks so you can convert market momentum into durable advantage.
Modular Data Centers Market
Market trajectory: what the headline numbers mean
The market has recorded rapid expansion over the past half-decade, rising from approximately USD 16.5 billion in 2020 to roughly USD 36.4 billion in 2025. Looking forward, our model projects continued durable growth through the forecast window to 2032, reaching roughly USD 110 billion. That trajectory implies a compounded annual growth rate of about 17.1% through 2032 — a level that reshapes vendor economics, procurement cadence, and site selection logic for 2026 and beyond.
Modular Data Centers Market
Two immediate strategic implications follow. First, the scale and velocity of this growth mean that modular solutions are no longer an auxiliary option but a primary delivery model for organizations pursuing speed, cost predictability, and scalability. Second, the market concentration profile is meaningful: a moderate-top-tier share by a small number of global suppliers creates both supplier-driven standards and pockets of opportunity for specialized integrators and regional players.
Modular Data Centers Market
Why this research matters to enterprise decision-makers in 2026
- AI and high-density compute as growth multipliers: New high-performance workloads are pushing site-level power and cooling requirements, raising the bar for prefabricated and containerized systems that can be optimized for AI/HPC without prolonged on-site construction cycles.
- Edge proliferation and heterogeneous estates: Enterprises are balancing centralized hyperscale capacity with distributed edge deployments. Modular systems shorten deployment lead times and limit construction risk in geographies with supply-chain or labor constraints.
- Regulatory, safety and standards inflection: Recent updates to standards frameworks and an industry push toward interoperable module designs (including initiatives under major open-hardware projects) mean compliance and standards-readiness are strategic purchasing criteria — not afterthoughts.
- Supply chain and delivery velocity: Prefabrication mitigates some material and schedule risk, but lead times for compute, power and thermal subsystems remain strategic considerations. Strategic sourcing and build partners matter.
What our full report delivers (practical, executable outputs)
- Proprietary market model: multi-scenario forecasts (base, accelerated, conservative) from 2026–2032, with transparent assumptions and sensitivity levers for power density, deployment cadence and regional demand drivers.
- Actionable go-to-market playbooks for buyers and vendors: procurement templates, contracting strategies that preserve flexibility for hardware refresh and modular upgrades, and vendor evaluation matrices.
- TCO and lifecycle modeling tools: CapEx / OpEx tradeoffs for containerized, prefabricated and all-in-one approaches calibrated to typical enterprise and colocation profiles.
- Risk and opportunity heatmaps: site selection criteria, regulatory and standards exposure, supply-chain bottleneck analysis, and mitigation tactics for time-to-market pressure.
- Supplier scorecards and strategic vendor maps: qualitative and quantitative assessment across engineering depth, delivery footprint, integration capability, and aftermarket services.
- Implementation playbooks: deployment sequencing, testing and commissioning checklists, and operational handover templates to reduce time-to-first-workload.
Note: This preview intentionally omits the full detailed breakdowns by region, type and application to preserve the report’s proprietary intelligence. The full dataset, scorecards and downloadable modeling assets are available in the complete PW Consulting report.
Competitive landscape — positioning and practical implications
The market combines global OEMs, systems integrators, and specialist modular fabricators. Three dynamics define competitive moves in 2026: product differentiation around integrated power/cooling/IT modules, speed-to-deployment claims supported by factory-controlled fabrication, and commercial models that align CapEx and OpEx incentives for customers.
- Vertiv: Vertiv’s prefabricated modular solutions target high-performance AI/HPC pockets and large-scale deployments. Their emphasis on integrated power and cooling systems aims to shorten engineering cycles for hyperscalers and service providers.
- Schneider Electric: Schneider’s EcoStruxure approach focuses on adaptable, high-performance modular designs suitable for complex, geographically diverse estates — positioning that favors multinational enterprises and environmentally constrained sites.
- ABB: ABB emphasizes modular scaling for colocation operators, prioritizing repeatable modules that accelerate ROI and simplify capacity expansion for operators seeking fast, bankable deployments.
- Eaton: Eaton’s SmartRack offerings and recent collaboration with Flexnode reflect a tactic of vertically optimizing power and backup subsystems to shave weeks off deployment schedules — a critical differentiator for AI factory projects.
- Flex: Flex positions its AI infrastructure platform as a pre-engineered route to accelerate chassis-to-compute timelines, claiming notable reductions in deployment cycle time via integrated design and assembly practices.
- Dell Technologies: Dell takes a systems-integration stance, modularizing racks and compute to serve edge and high-density environments where standard data center shells are impractical.
- M.C. Dean: With a recent patent covering support rack systems and installation methods, M.C. Dean is moving to protect and scale a differentiated installation approach aimed at campus-style deployments.
- Haskell Modular Solutions: Haskell plays to custom, factory-controlled fabrication, making it attractive where bespoke configurations or fast turnarounds are strategic priorities.
Recent product launches and alliances — including the 2025–2026 spate of product expansions and turnkey edge offerings — underscore a clear market move: vendors are packaging more pre-integrated value (power, cooling, management) to win shorter sales cycles and higher-margin professional services. For buyers, that trend simplifies vendor selection but increases the importance of rigorous vendor due diligence around interoperability, upgrade paths, and lifecycle support.
Regulatory and standards headwinds/opportunities
- Safety and compliance frameworks have been refreshed to address modern prefabricated systems and AI-driven workloads; procurement processes must include compliance verification early in the RFP stage.
- Open-hardware standardization efforts are lowering integration overhead and enabling more modularity across suppliers — a strategic opening for organizations seeking multi-vendor flexibility.
- Patents and proprietary installation methods are becoming differentiators; buyers should balance innovative delivery against lock-in risk.
Strategic recommendations for 2026
- Adopt modular-first sourcing policies for new greenfield and brownfield expansions where speed and repeatability matter; require vendor roadmaps and upgrade pathways in contracts.
- Implement staged pilots for AI/HPC and edge workloads: validate thermal and power management strategies in production-like environments before large rollouts.
- Negotiate service-level contracts that include performance guarantees for integrated power and cooling subsystems, and insist on interoperability clauses tied to open standards where feasible.
- Prioritize partners with factory-controlled manufacturing and proven supply-chain continuity to reduce schedule risk; map critical-path components and create redundancy in procurement plans.
- Use scenario-based TCO models to compare containerized, prefabricated and all-in-one approaches under varying utilization profiles and upgrade cadences.
- Monitor regulatory updates and standards participation (including major open-hardware initiatives) as an input to vendor selection and architecture design.
- For service providers and colocation operators: design modular rolls that support rapid densification and multi-tenant isolation to capture evolving third-party demand.
Use cases shaping buying criteria
Different business objectives imply different modular strategies. Rapidly deployable temporary capacity, edge sites with constrained footprints, AI/HPC facilities requiring dense power/cooling integration, and colocation expansions each place a distinct premium on engineering, factory control, and lifecycle support. Our full report maps these use cases to vendor capabilities and procurement templates to make decision-making operational rather than aspirational.
Concluding perspective — act with speed, but structure for resilience
The modular data center market’s projected near-term scale and high growth rate make 2026 a pivotal year to lock in strategic advantage. The winners will be organizations that treat the modular transition as a systems-design exercise — combining vendor selection rigor, standards alignment, and flexible commercial structures — rather than a one-off procurement. PW Consulting’s full report delivers the quantitative foundations, supplier scorecards, and implementation playbooks needed to convert market momentum into defensible capacity and predictable economics.
This briefing highlights core trends and practical imperatives while withholding the granular segmentation tables, supplier-level metrics, and downloadable forecasting models that our clients rely on for procurement and investment decisions. To access the full dataset, scenario models, and the PW Consulting vendor evaluation toolkit, please visit the report landing page and download the comprehensive Modular Data Centers Market study.
For detailed analysis of this topic, please visit the official page: Modular Data Centers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com