

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Boat Insurance Market to Reach USD 475 Million by 2032 (CAGR 5.85%)

Boat Insurance Market 2026 — Strategic Preview
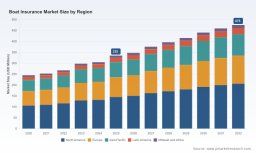
As senior industry analysts at PW Consulting, we present a forward-looking briefing designed to orient executive teams, investors, and insurance strategists as they finalize plans for 2026. The global boat insurance market has demonstrated consistent expansion through the early 2020s, increasing from a measured base in 2020 to an estimated USD 335.0 Million in our base year (2025), and is projected to reach approximately USD 475.0 Million by 2032. Our forecast window (2026–2032) embeds a compound annual growth rate (CAGR) assumption of 5.85% and reflects the combined influence of rising recreational participation, evolving regulatory regimes, and reinsurance market dynamics.
Boat Insurance Market
Why this briefing matters for 2026 decision-making
- Timing: 2026 represents an inflection point where premium adequacy, digital distribution investments, and regulatory compliance choices crystallize into durable competitive advantage.
- Capital allocation: Insurers and reinsurers must decide whether to prioritize underwriting capacity, technology for direct-to-consumer channels, or targeted M&A to shore up exposure in coastal geographies.
- Underwriting & pricing: Post-2025 premium and claims trends mean material premium adjustments are plausible in certain high-exposure states; underwriting frameworks developed now will determine 2026 loss ratios.
Market trajectory and structural signals
PW Consulting’s historical series (2020–2025) shows steady growth into the base year. The forecast period to 2032 anticipates continued expansion driven by multiple demand-side and supply-side vectors: higher boat ownership rates in mature leisure markets, commercial activity in specialty fishing and small commercial craft, and broader adoption of value-added policy features (e.g., event coverage, agreed-value options). At the same time, the market exhibits meaningful concentration: the top three firms account for a substantial portion of capacity, and a top-five concentration figure signals that competitive moves by a handful of incumbents will materially affect national pricing and distribution dynamics.
Boat Insurance Market
Regulatory and risk environment — what’s changed and what to expect
- Liability mandates are shifting at the state level. For example, new legislation introduced in 2025 in South Carolina requires minimum liability coverage for specified watercraft classes and increases enforcement at title/registration—this illustrates the growing willingness of state legislatures to tie insurance to ownership registration. Firms operating in states adopting similar mandates must prepare for accelerated policy issuance and proof-of-coverage workflows.
- Household policy gaps remain significant. Several regulators continue to note that standard homeowners packages provide only limited protection for boats—often insufficient for liability exposure—meaning there is persistent cross-sell opportunity for standalone boat policies and endorsements.
- Catastrophe and reinsurance pressures are compressing capacity in high-exposure coastal states. Market evidence shows that boaters in highly coastal jurisdictions may see premium impacts materially above national averages—insurers should expect location-driven price differentiation to persist or widen in the near term.
Distribution, consumer behavior and pricing signals
Consumer premium data in industry sources indicates an average annual premium band for recreational policies. At the same time, coastal exposures and reinsurance dynamics are producing above-average increases in specific states. These twin facts mean distribution strategies that balance scale (digital direct channels, affinity partnerships) with localized underwriting acuity (agent-based, field-inspection workflows) will perform best. For 2026, management teams must decide how aggressively to invest in real-time quoting technology versus expanding agency networks to capture the uptick in mandatory and voluntary purchases.
Boat Insurance Market
Competitive landscape — reading the movers
The competitive set combines national multiline carriers, specialty underwriters, and emergent tech-first entrants. Legacy insurers with broad P&C footprints continue to leverage brand and agent networks to capture recreational volumes, while specialized marine underwriters and startups are focusing on tailored products for higher-value yachts, commercial fishing fleets, and flexible admitted/excess structures.
- Large multiline carriers: These firms use scale, integrated distribution, and brand trust to secure retail volumes and affinity partnerships. Their priorities are portfolio-level loss control, pricing normalization across states, and cross-sell into homeowners/auto customers.
- Specialty and marine-focused underwriters: These players concentrate on custom coverages (agreed value, equipment endorsements) and niche commercial needs, often tolerating thinner distribution for superior underwriting margins.
- Tech-native entrants: Newer providers are building direct, data-rich platforms and are expanding into strategic states; their playbooks emphasize pricing agility, rapid underwriting via data ingestion, and partnerships with platform distribution partners.
Notable market activity in 2025–2026 highlights how competitive dynamics are evolving: tech-driven entrants expanded admitted and surplus offerings in major boating states, while state-level regulation introduced new compliance requirements that will accelerate the addressable market for insured boaters where proof-of-coverage becomes mandatory.
What our full report delivers (executive-to-operational granularity)
PW Consulting’s Boat Insurance Market report is built for action. We combine top-down market sizing with bottom-up practical modules designed to move teams from insight to execution. Highlights include:
- Actionable market-sizing models (macro scenario paths for 2026–2032) and revenue ladders by product family and end-use application.
- Regulatory impact matrix that maps state-level legislative trends to projected policy uptake and compliance costs, with sensitivity analysis for liability thresholds and enforcement mechanisms.
- Underwriting playbook: data-led risk segmentation, recommended rating variables, claims frequency/severity scenarios, and a reinsurance optimization template for balancing retention, cost, and capacity.
- Distribution ROI calculator: compare acquisition economics for direct digital channels, agency growth, affinity partnerships, and white-label programs using client-provided cost baselines.
- Product design and bundling tests: prototypes for tiered liability, agreed-value endorsements, towing and equipment packages, and special-event coverages that speak to owner demand patterns.
- Claim and fraud analytics guidance: prioritized telematics and inspection investments to reduce frequency and improve salvage recoveries, including sample KPIs and implementation timelines.
- Competitive playbook and M&A diagnostic: capability heat maps that identify targets for capability buy vs. build decisions across underwriting, tech, and geographic presence.
To respect commercial sensitivity and preserve the strategic "teaser" value of this preview, we intentionally withhold core subsegment-level tables and region/application shares here. The full report contains those granulated splits, scenario files, and proprietary scoring models.
Practical strategic implications for 2026
- Pricing & underwriting: Institutionalize a two-track pricing approach—aggressive digital-first pricing to capture low-risk recreational policyholders, and more conservative, underwritten offerings for higher-exposure coastal and commercial craft. Stress-test tariffs against 15–25% reinsurance-driven premium inflation scenarios in coastal states.
- Distribution: Reallocate incremental marketing budgets to tested affinity channels in states with newly mandated insurance proof, and accelerate API-enabled quoting for dealer and marina partners to capture purchase-moment policy issuance.
- Product innovation: Launch modular endorsements that address liability minimums and short-term event needs (e.g., regatta or charter coverage) to monetize episodic usage and the growing shared-economy segment for vessels.
- Claims & loss control: Invest in remote inspection, digital evidence submission, and preventive boater education discounts—these measures reduce loss severity and enable differentiated pricing for safer customers.
- Capital & reinsurance strategy: Reassess treaty structures to manage accumulating coastal exposures; consider quota-share arrangements for new-state expansions where balance-sheet capacity is constrained.
- M&A and partnerships: Target capability acquisitions that accelerate entry into state markets with regulatory uplift or that plug gaps in digital distribution and telematics-enabled underwriting.
Execution checklist for 90–180 days
- Run scenario stress tests on 2026 portfolio plans using the PW Consulting regulatory impact matrix and the reinsurance sensitivity tool included in our report.
- Prioritize data integrations for dealer and marina point-of-sale APIs; pilot real-time issuing in one high-opportunity state before scaling.
- Deploy a targeted agent training and incentive bundle aligned with any state-level liability mandates anticipated to take effect in 2026.
- Evaluate partnership opportunities with specialty marine insurers to co-underwrite exposures above internal capacity thresholds.
Conclusion — where to focus in 2026
The boat insurance market presents a balanced mix of growth opportunity and concentrated risk. Market expansion, regulatory pushes toward mandatory coverage in certain jurisdictions, and reinsurance-driven premium pressure all create an environment where precise underwriting, nimble distribution, and capital-aware expansion will separate winners from followers. PW Consulting’s full Boat Insurance Market report equips boards and senior management with the scenario tools, pricing models, and operational playbooks needed to translate the 2025–2032 trajectory into profitable 2026 outcomes.
For access to granular segmentation, proprietary scoring models, and the full suite of implementation templates, download the complete PW Consulting report or contact our advisory team to arrange a tailored briefing and hands-on scenario workshop.
For detailed analysis of this topic, please visit the official page: Boat Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com