

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Torsional Vibration Damper Market — USD 1,800M in 2025, 5.5% CAGR (2026-2032)

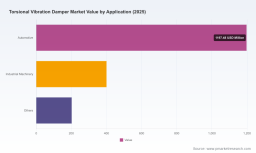
Torsional Vibration Damper Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a forward-looking briefing designed to orient executives, investors and product leaders preparing decisions in 2026. This preview synthesizes the structural forces, competitive dynamics and near‑term scenarios shaping the global torsional vibration damper (TVD) market. It demonstrates the type of rigorous, actionable intelligence contained in our full market study — while intentionally withholding the granular segment tables and proprietary model outputs that are included in the report itself.
Torsional Vibration Damper Market
Why this research matters for 2026
- Market inflection: The TVD market is past a commodity-only phase and is entering a technology-differentiation window driven by downsized high-torque engines, hybrid powertrains and stricter NVH and emissions standards.
- Timing: With our base year set at 2025 and the formal forecast window 2026–2032, 2026 is the pivot year for decisions on new product investments, capacity reconfigurations and M&A execution if firms want to capture the next wave of demand.
- Practical outcomes: This study is built to support procurement negotiations, R&D roadmaps, aftermarket strategies and investor due diligence — with scenario-tested revenue, margin and sensitivity tables that speak to near-term capital allocation choices.
Market trajectory — the macro story
Our macro model shows the global TVD market expanding steadily. After a historical rise from around USD 1,200 Million in 2020 to USD 1,800 Million in 2025 (base year), we forecast continued growth through 2032, with the global market reaching approximately USD 2,800 Million by 2032. That implies a compound annual growth rate (CAGR) of roughly 5.5% over the 2026–2032 forecast period. In short: after recovery and consolidation, the market is in a multi-year growth phase driven by NVH regulation, powertrain transitions and industrial vibration control demand.
Torsional Vibration Damper Market
Two additional macro observations shape near-term strategy:
Torsional Vibration Damper Market
- Growth is not linear across technologies and applications — engineering sophistication and OEM integration needs are amplifying value capture for differentiated suppliers.
- Volatility in upstream input costs and OEM price pressure mean margin resiliency will be earned through product differentiation, scale and supply-chain design, not through volume alone.
Competitive landscape — what the leaders are doing
The market exhibits modest concentration, with global incumbents holding meaningful OEM relationships while a broader set of specialized players compete on technology, customization and aftermarket service. Leading firms profiled in our study include Vibracoustic SE, Vibratech TVD, Schaeffler AG, ZF Friedrichshafen AG, Continental AG, Hasse & Wrede, Dayco, American Engineering Group (AEG), Geislinger, BorgWarner, Trelleborg, Valeo, Sumitomo Riko and LuK. Below are strategic snapshots drawn from publicly available company activity and our primary interviews.
- Vibracoustic SE (Weinheim, Germany) — Deep OEM reach and breadth across elastomeric and fluid dampers. Their recent unveiling (Feb 2026) of multi-stage rubber elastomer technology signals a move to capture broader engine speed ranges and to compete where multi-modal damping is required. Expect them to press for long-term OEM contracts where they can trade technological IP for scale commitments. ( https://vibracoustic.com)
- Vibratech TVD / Fluidampr (Springville, NY, USA) — Niche leader in viscous solutions, with strong presence in high-performance, off-highway and stationary power markets. Their 2025 technical webinar on next‑generation viscous dampers underlines a product-led push into downsized high-torque ICEs and hybridized applications — markets that place a premium on thermal stability and long-term viscous performance. ( https://www.vibratechtvd.com)
- Schaeffler AG & ZF Friedrichshafen AG — Both companies leverage systems-level integration (transmissions, dual-mass flywheels, PTOs). They favor solutions that are integrated into broader powertrain modules, creating higher switching costs for OEMs and prioritizing customers seeking single‑supplier simplicity. ( https://www.schaeffler.com; https://www.zf.com)
- Hasse & Wrede — A specialist and world market leader in viscous shear-type dampers for engines and compressors. Their recent trade show activity and product availability on specific compressor platforms reflect a strategy of focusing on high-value industrial applications where switching costs and certification barriers protect margins. ( https://www.hassewrede.com)
- Aftermarket and diversified suppliers (Dayco, Continental, BorgWarner, Valeo, Trelleborg) — These players balance OEM contracts with independent aftermarket offerings, enabling them to monetize installed-base service and to provide complementary NVH systems to OEMs looking to outsource non-core modules. Dayco’s 2025 severe-duty aftermarket expansion is an example of targeting long-tail revenue in heavy-duty segments. ( https://www.dayco.com; https://www.continental.com)
- Smaller specialists (AEG, Geislinger, Sumitomo Riko, LuK) — These firms compete through niche design innovations (dual elastomer systems, tuned steel spring dampers, elastomeric composites) and tight OEM certification paths in specific geographic clusters.
Recent corporate activity in 2025–early 2026 highlights two parallel playbooks: (1) product-innovation and technical evangelism for viscous and multi-stage elastomer solutions; and (2) aftermarket and industrial-targeted expansions to capture non-automotive demand. Both approaches are viable — selection depends on a firm’s scale, certification capability and capital tolerance for long OEM lead times.
Industry dynamics and risk factors
- Raw material volatility — Petrochemical-driven swings in elastomer and silicone-based fluid costs are increasing input-cost variability. Our cost-sensitivity models show that without pass-through mechanisms or design efficiencies, margins can compress materially in high-cost cycles.
- Regulation and certification — Accelerated NVH and emissions standards (tightening at roughly mid-single-digit annual rates in many mature markets) are raising certification burden and testing costs. Suppliers without robust testing and validation capabilities will struggle to win long-term OEM frames.
- OEM price pressure and labor cost dynamics — Sustained OEM price-reduction programs are compressing margins for commoditized suppliers. Labor cost inflation and the need for low-cost manufacturing footprints create a two-edged challenge: price competition versus reliability and certification demands.
- Technology shift risks — Electrification reduces some torsional vibration requirements on pure-EV drivetrains but introduces new NVH profiles (e.g., high-frequency torque pulses, inverter-induced vibrations). The winners will be firms that can translate engine-era competence into electric drivetrain NVH solutions.
What the full PW Consulting report provides (operational, purchase-ready intelligence)
The full study goes beyond high-level trends to provide the operational inputs executives need to act in 2026:
- Validated market sizing and high-granularity forecasts (2026–2032) across product technologies and end-use buckets with sensitivity scenarios based on input-cost and regulation shocks.
- Supplier and OEM matrix mapping technology fit‑for‑purpose, qualification timelines, and switching-cost profiles (essential for procurement negotiation timelines).
- Detailed go‑to‑market playbooks for aftermarket entrants, OEM integrators and niche suppliers, including target account lists, certification roadmaps and cost-to-certify models.
- Capital allocation and M&A screening framework: valuation multipliers observed across recent deals, integration risk checklists, and a prioritized list of tuck‑ins relevant to each strategic archetype.
- Practical engineering briefs on multi-stage elastomer design, viscous fluid formulations temperature durability and service-life prediction models — intended to align R&D sprints with commercialization windows.
- Supply-chain and procurement tactics to mitigate elastomer fluid-cost volatility and to structure OEM contracts for shared risk on raw-material inflation.
Note: In keeping with the preview principle, detailed sub-segment volumes and regional breakdowns are reserved for the full report and interactive dashboards available on our source page.
Strategic implications and recommended 2026 actions
For executives deciding in 2026, our analysis yields a concise decision framework:
- If you are an OEM supplier with scale: prioritize multi-stage elastomer and integrated flywheel/damper systems that raise switching costs. Invest in localized validation centers to shorten qualification timelines.
- If you are a viscous-specialist: lean into performance claims for high-torque, downsized engines and industrial compressor markets where certification barriers and performance differentiation protect margins.
- If you are an aftermarket or diversified supplier: accelerate severe-duty and installed-base service offerings — aftermarket growth can materially improve utilization and dampen OEM margin pressure.
- If you are an investor or M&A strategist: target bolt-on assets that supply certification capability, specialized materials know-how, or captive industrial end-markets; avoid buying into pure-volume plays without engineering IP or OEM feed-in agreements.
- All players should: implement input-cost hedging, incorporate NVH-certification cost into bid economics, and stress-test product roadmaps for EV-era NVH profiles.
Closing perspective
The torsional vibration damper market in 2026 is a classic strategic inflection: predictable macro growth (CAGR ~5.5% through 2032) combined with shifting technical requirements and margin pressures that reward technology and execution. Our full PW Consulting report is designed to convert these dynamics into executable plans — with granular models, supplier scoring, and playbooks that can be used immediately in procurement, R&D prioritization, and M&A diligence.
For executives who want the underlying datasets, segment tables, company scorecards and interactive scenario models that support these conclusions, consult the full report and dashboards on our publication page. The granular intelligence that will inform contract terms, R&D funding and capacity decisions in 2026 is only a click away.
For detailed analysis of this topic, please visit the official page: Torsional Vibration Damper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com