

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Lift Chair Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Industry Analyst, I present a concise strategic preview of our comprehensive Lift Chair Market study (base year 2025; historical 2020–2025; forecast 2026–2032). The sector is entering a decisive phase: after a period of steady recovery and product refresh, the global market reached approximately USD 3,400 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 7.5% through the 2026–2032 forecast window, crossing the multi‑billion threshold by the end of the period. For corporate leaders planning 2026 investments, M&A activity, or operational pivots, this report translates market momentum into actionable choice architecture—without giving away the granular segmentation that forms the core of our premium deliverable.
Lift Chair Market
Why 2026 Is a Strategic Inflection Point
- Demographics and reimbursement converge: An aging population and established reimbursement pathways have created a persistent demand base that is now being amplified by product innovation and distribution realignment.
- Manufacturing localization and supply resilience: Recent industry moves toward domestic manufacturing capacity reflect a broader re‑pricing of supply‑chain risk—an important factor for capital allocation and sourcing strategy.
- Product and service differentiation: The market is shifting from basic utility to wellness‑centric and integrated solutions, increasing the premium potential for differentiated players while compressing margins for undifferentiated OEMs.
What the Report Delivers (Practical Content Overview)
- Robust market sizing and validated growth scenarios: We model demand across 2020–2032, offering base, upside, and downside scenarios that isolate drivers such as reimbursement policy shifts, raw material price shocks, and aging‑population variants.
- Channel & commercial playbooks: Detailed go‑to‑market options for direct OEM retail, DME supplier partnerships, healthcare procurement, and e‑commerce—with impact matrices that quantify sales, margin and service cost sensitivities.
- Competitive benchmarking: A qualitative and quantitative framework to evaluate incumbents and challengers across product breadth, manufacturing footprint, regulatory positioning, and channel control—ranked on strategic levers rather than merely revenue share.
- Product roadmaps and white‑space analysis: Identifies high‑value product features (positioning systems, motors, ergonomic design, integrated therapy) and suggests prioritization paths for R&D investment that align with reimbursement incentives.
- Supply‑chain stress tests and cost buckets: Scenario analysis on critical inputs—high‑torque motors, scissor mechanisms, and steel—plus sourcing levers to reduce lead‑time risk and total landed cost.
- M&A and partnership playbooks: Criteria and shortlists for bolt‑on acquisitions, manufacturing JV targets, and channel alliances that accelerate scale while protecting margin.
- Implementation toolkit: Executive dashboards, ROI calculators, and a 90‑ to 180‑day rollout checklist for commercialization and operational adjustments.
Macro and Structural Dynamics Shaping Strategy
Three structural forces deserve immediate attention from C‑suite and corporate development teams:
Lift Chair Market
- Reimbursement complexity and clinical pathway integration. Lift chairs are often procured through healthcare channels because they qualify as durable medical equipment under Medicare Part B; crucially, coverage typically extends to the motorized lifting mechanism (subject to clinical documentation and supplier enrollment) rather than the furniture shell. This creates a two‑tier commercial landscape where the product and the clinical claim must be aligned—an area where partnerships with enrolled DME suppliers or new in‑house reimbursement capabilities can create defensible margins.
- Product safety and regulatory posture. Leading manufacturers market devices that meet medical‑device classifications and weight/safety standards; this raises the bar for product development and post‑market surveillance, but also creates opportunity for premiumization through verified clinical claims and ergonomics validated for chronic conditions such as arthritis and lower‑back disorders.
- Material and mechanical dependencies. Performance, serviceability and cost are driven by key components—high‑torque motors, robust scissor lift mechanisms and steel structural parts. Firms that de‑risk these inputs through alternate sourcing, supplier partnerships or vertical integration will enjoy superior uptime and service economics.
Competitive Landscape: Strategic Positions to Watch
The market comprises established furniture brands, specialized mobility manufacturers, and retail‑focused incumbents. Our research highlights several archetypes and current strategic moves:
Lift Chair Market
- Specialized mobility leaders: Companies with deep clinical positioning and dedicated mobility portfolios have translated product engineering into durable competitive advantage. Their strengths include regulatory knowhow, clinical claims, and distribution via enrolled DME networks.
- Furniture brands moving up‑market: Major furniture manufacturers are leveraging design heritage, retail reach and brand equity to capture wellness‑seeking consumers, often adding features such as heat/massage and premium upholstery to differentiate in retail channels.
- Integrated OEM‑retailer hybrids: Some market participants combine manufacturing scale with retail distribution, enabling faster product feedback cycles and closer control of margins and service.
Recent corporate developments point to tactical priorities: one leading manufacturer reduced lead times and extended model variants to address availability and fit; another expanded domestic manufacturing capacity to strengthen “made‑in‑USA” value propositions; and a market‑leading manufacturer earned industry recognition for product quality—signals that manufacturing agility and brand trust are central to near‑term competition.
Regulatory and Reimbursement Implications for 2026 Decisions
- Reimbursement as a strategic channel: Because motorized lifting mechanisms can be reimbursed under certain conditions, firms should assess whether to build in‑house clinical documentation and DME enrollment capabilities or to create partnership models with certified suppliers.
- Regulatory labeling and claims: Manufacturers that can demonstrate compliance with medical‑device classifications and safety standards will access institutional buyers and clinical referral pathways more readily; this requires investment in testing, documentation, and post‑market vigilance.
- Procurement friction points: The dual nature of sellable goods (chair + lift kit) introduces billing and warranty complexities that must be anticipated in pricing, contract terms and customer support planning.
Strategic Playbook for 2026
We outline five prioritized actions for executives preparing decisions in 2026. Each is linked to the commercial levers that will most influence returns in a market growing at c.7.5% per annum.
- Prioritize channel modernization. Invest in DME partnerships and digital ordering for clinical channels while refining premium retail assortments for direct‑to‑consumer sales. Test hybrid pricing pilots that separate the lift mechanism and furniture in controlled geographies.
- Secure critical component supply. Negotiate multi‑year contracts for motors and structural steel, pursue dual sourcing for high‑failure items, and evaluate nearshoring for the highest‑risk components to reduce lead time and tariff exposure.
- Differentiate through verified functionality. Allocate R&D to clinically‑validated positioning systems and ease‑of‑use features for elderly and bariatric users; small feature premiums can compound into significant margin improvement when aligned with reimbursement pathways.
- Operationalize service as a competitive moat. Develop warranty and aftercare programs, including technician networks and remote diagnostics, to convert one‑time buyers into service revenue streams and to reduce return rates.
- Evaluate M&A selectively. Target bolt‑ons that add DME enrollment capabilities, proprietary lift mechanisms, or regional manufacturing footprints that accelerate time‑to‑market and reduce unit costs.
Where the Report Helps You Now
For executives evaluating capital allocation and strategic initiatives in 2026, our study functions as both map and toolkit. It blends macro sizing and scenario planning with a practical set of deliverables: market models you can stress test, competitor dossiers you can use in diligence, and playbooks that can be operationalized within 90–180 days. The core segmentation and financial detail are intentionally reserved for the full report—this preview surfaces the directional insights that matter for confidential boardroom decisions while steering interested teams to the commissioned study for the detailed segment economics, regional breakdowns and company‑level revenue mixes.
Conclusion: From Insight to Competitive Action
The lift chair market is no longer a niche appliance category; it sits at the intersection of healthcare economics, aging‑population dynamics, and consumer wellness trends. With a 2025 market base in the billions (USD) and a mid‑single‑digit to high‑single‑digit CAGR ahead, firms that move early to secure component supply, build reimbursement competence, and differentiate through validated features will capture disproportionate value. PW Consulting’s full Lift Chair Market study provides the granular segmentation, competitor financials and prioritized implementation playbooks required to turn these strategic possibilities into measurable outcomes in 2026.
Contact PW Consulting to access the full market model, company profiles, and the decision‑ready implementation toolkit that underpin this preview.
For detailed analysis of this topic, please visit the official page: Lift Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Grippers Market at USD 1,755M in 2025, Poised for 9.4% CAGR (2026–32)
By pmarketresearch, 2026-07-30
Grippers Market: Strategic Imperatives for 2026 — A PW Consulting Industry Brief
As global manufacturers accelerate automation strategies to solve persistent labor shortages, tighten safety compliance, and squeeze greater flexibility from production lines, grippers — the end-effectors that enable robots to touch, move, and manipulate — are no longer a commodity. They are a strategic lever. PW Consulting’s Grippers Market study (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes market dynamics, competitive positioning, regulatory shifts, and technology roadmaps to equip executives with the decision-grade intelligence required for 2026 and beyond.
Grippers Market
Why 2026 Is a Pivotal Year for Gripper Strategy
After steady expansion through the early 2020s, the grippers market enters the 2026 planning horizon with renewed urgency. Our base-year analysis concludes that market growth momentum—anchored by a compound annual growth rate (CAGR) of 9.4% across the 2026–2032 forecast window—will reshape supplier economics and buyer choices. In practical terms, companies that define gripper strategy in 2026 will lock in unit economics, ecosystem partnerships, and compliance postures that determine competitiveness for the remainder of the decade.
Grippers Market
High-Level Market Trajectory (Macro View)
- Base and historical framing: The study includes a robust historical series (2020–2025) and detailed forecasting from 2026 through 2032 to support short- and medium-term capital planning.
- Forecast growth dynamics: The projected 9.4% CAGR reflects an interplay of automation adoption, rising sophistication of collaborative and adaptive grippers, and replacement cycles driven by evolving safety standards and modular robotic platforms.
- Market structure: The market exhibits moderate concentration — our analysis shows the top three players account for a meaningful portion of value (CR3 at 45%), while the top five compress further (CR5 at 55%) — leaving room for focused challengers and niche innovators.
Dynamics Driving Adoption
- Labor constraints and operational continuity: By Q3 2025 manufacturers reported an average of 4.2% of roles unfilled, with a sizable subset facing vacancy pressures above 5%. These labor realities are pushing OEMs and end-users toward gripper-led automation for repetitive, ergonomically risky, or precision tasks.
- Regulation and safety: The 2025 revision of ISO 10218-2 embeds force and speed limits and expanded guidance for end-of-arm tooling. For firms deploying collaborative systems, compliance is not optional; end-effectors must now meet explicit thresholds and documented risk assessments for dropped loads and pinch points.
- Segment evolution: Demand motion is shifting from simple, high-throughput pneumatic designs toward hybrid solutions — electric actuation, integrated sensing, soft- and vacuum-based delicate handling — enabling new use cases in food, electronics, and medical device assembly.
Technology and Product Innovation — What to Watch in 2026
Innovation is converging on three vectors: intelligence at the end-effector (embedded sensors and tactile feedback), hygienic or food-safe materials, and plug-and-play integration for collaborative robots. Recent vendor activity illustrates these trends:
Grippers Market
- Destaco’s eRDH electric parallel gripper (launched mid-2025) emphasizes teachable sensors and configurable grip modes targeted at high-mix automotive cells.
- Festo’s late-2025 adaptive gripper introduces food-grade silicone and bionic handling concepts for hygienic pick-and-place applications.
- Robotiq’s early-2026 tactile fingertip integration signals a broader move to tactile-enabled manipulation that reduces vision dependency in unstructured pick tasks.
- Piab’s 2026 soft gripper for confectionery highlights how vacuum and soft-robotic hybrids are unlocking previously inaccessible categories.
Competitive Landscape: How to Read the Field
Our competitive analysis synthesizes vendor capabilities, route-to-market, and innovation pipelines. Key players profiled in the report include legacy industrial automation specialists, cobot-native entrants, and niche innovators:
- SCHUNK GmbH & Co. KG — modular systems portfolio spanning pneumatic, electric, and adaptive grippers tailored to industrial robotics platforms.
- OnRobot A/S — a leader in plug-and-play collaborative grippers and EOAT optimized for cobots and light-duty cells.
- DESTACO (Stabilus Group) — focused on electric and pneumatic parallel grippers with teachable sensor features for machine tending.
- Piab AB — vacuum and soft-grip expertise for packaging, palletizing, and delicate parts handling.
- Zimmer Group, Robotiq, Weiss Robotics, ATI Industrial Automation, Festo, and Schmalz — each brings differentiated strengths in intelligent gripping, force/torque integration, hygiene-compliant materials, or system-level integration.
While the market contains dominant incumbents, there is ample space for specialist providers that combine material science, sensing, and software integration to capture premium segments. The report offers supplier scorecards, partnership archetypes, and negotiating playbooks suited to OEMs, system integrators, and end-users.
What PW Consulting’s Grippers Market Report Delivers (Practical, Actionable Content)
We structured the study to be immediately operational for commercial planning and procurement cycles in 2026:
- Executive strategy frameworks — decision trees for make vs. buy, modularization priorities, and portfolio rationalization across product lines.
- Commercial models — TCO and ROI templates calibrated to gripper lifecycle drivers (actuation type, maintenance cadence, sensor integration), with sensitivity analyses for price, uptime, and labor substitution.
- Procurement playbook — supplier scorecards, SLA templates, and criteria for vendor qualification that factor in regulatory compliance, service coverage, and software interoperability.
- Integration and deployment blueprints — recommended control architectures, safety validation checklists aligned to ISO 10218-2:2025, and pragmatic steps for achieving collaborative safety without sacrificing throughput.
- Strategic scenario planning — three demand scenarios (baseline, accelerated automation, and constrained-capex) with corresponding capital and sourcing pathways for 2026–2028.
- M&A and partnership guidance — target profiles for bolt-on technologies, due-diligence checklists for IP and field reliability, and valuation sensitivities tied to modularity and software capability.
- Market and technology roadmaps — timelines of expected adoption inflection points for electric actuation, soft gripping, integrated tactile sensing, and standardization trends.
- Field intelligence — anonymized use cases and measured KPIs from deployments across high-turnover sectors to illustrate real-world payback periods and pitfalls.
Methodology and Forecast Rigor
The report’s forecast blends bottom-up shipment and pricing models with macro adoption curves and historical data (2020–2025). We triangulate primary interviews with OEMs, system integrators, and leading suppliers with secondary sources to stress-test assumptions. Scenario sensitivity allows users to adjust key inputs — adoption rate, price erosion, and regulatory compliance costs — to quantify outcomes across CAPEX cycles.
Strategic Recommendations for 2026 Decision-Makers
- Prioritize modularity: Insist on grippers with standardized mechanical interfaces and documented electrical/software APIs to preserve future flexibility and reduce lock-in.
- Treat sensing as a first-class requirement: Tactile and force sensing transform grippers from passive tools into active decision points that reduce vision dependency and increase yield in mixed-SKU lines.
- Embed compliance early in procurement: With ISO 10218-2:2025 tightening requirements for end-effectors, integrate safety validation into vendor selection rather than as a retrofit project.
- Build hybrid sourcing strategies: Combine long-term strategic agreements with niche buys to balance cost, innovation access, and risk mitigation — particularly for food-safe and soft-grip applications.
- Plan for total cost, not unit price: Evaluate maintenance, downtime risk, spare-parts availability, and software update pathways during capex approval stages.
How to Use This Report to Gain Competitive Advantage
For manufacturers, the study functions as a procurement and line-engineering playbook that shortens deployment timelines and clarifies ROI. For suppliers, the report is a go-to-market manual, defining whitespace opportunities, vertical use case primers, and partnership models that accelerate adoption. Investors gain an evidence-based lens into concentration dynamics and the competitive swaths most likely to reap scale economies.
Closing Perspective
By 2026, grippers will be judged not only by grip force or cycle time, but by their contribution to a resilient, compliant, and flexible production system. PW Consulting’s Grippers Market report offers the strategic scaffolding to transform gripper choices from tactical purchases into strategic enablers of productivity and safety. The report reveals the data, templates, and competitive intelligence you need to make informed decisions; it intentionally reserves proprietary segment-level granularity and supplier share tables for the full report to preserve client value and ensure rigorous interpretation.
To access the complete dataset, supplier scorecards, and executable playbooks that underpin these insights, visit the report page or contact PW Consulting’s industry team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Grippers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Turbomolecular Pumps Market to Hit USD 2,460M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-30
Turbo Molecular Pumps Market — 2026 Strategic Preview
By PW Consulting — Senior Strategic Advisor / Head of Industry Analysis
This briefing frames the strategic decisions that matter in 2026 for executives operating in or adjacent to the turbomolecular pumps market. Drawing on our PW Consulting market model (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) and primary research across OEMs, integrators and end-users, this preview highlights where value will accrue, where risk is concentrating, and which tactical moves buy time versus create durable advantage. The purpose is to demonstrate technical and commercial depth while reserving core segmented datasets for the full report.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Market snapshot — macro trajectory you can act on
The turbomolecular pumps market reached approximately USD 1.69 billion in 2025 and is forecast to grow at a steady compound annual growth rate of about 5.5% over the 2026–2032 period, reaching roughly USD 2.46 billion by 2032 under our base scenario. After a measured recovery from 2020–2023, the market experienced an acceleration in 2024 and 2025 driven by capacity build-outs in semiconductor and advanced materials processing, and the maturation of higher-throughput maglev and hybrid solutions. Market concentration is meaningful: the top three vendors account for a majority share of revenue, and the top five raise that concentration modestly further — an important structural feature for pricing dynamics, aftermarket opportunity and M&A playbooks.
Turbo Molecular Pumps (Turbomolecular Pumps) Market
Key demand & supply dynamics shaping 2026 decisions
-
Policy and procurement are now technical levers. Energy-efficiency directives in major jurisdictions have already pushed OEMs to deliver lower-wattage drives and intelligent standby modes. Public-sector procurement and large-system integrators are explicitly scoring energy intensity and lifecycle emissions, creating a near-term bid advantage for pump platforms with validated efficiency credentials.
Turbo Molecular Pumps (Turbomolecular Pumps) Market -
Net-zero roadmaps impose multi-year product and capital cycles. Net-zero energy-intensity requirements in Europe and North America extend planning horizons for manufacturers (multi-year compliance windows), forcing choices between incremental efficiency upgrades and more fundamental architecture changes (e.g., wider adoption of magnetic levitation and smart power electronics).
-
Semiconductor and life-science ecosystems are demand multipliers. Policy stimuli and domestic fab programs are sustaining demand for higher pumping speeds and lower base pressures in select submarkets; procurement timelines and qualification hurdles remain long, making early engagement and co-development with strategic customers a high-return activity.
-
Raw-material and component risk is concentrated but manageable. Bearings made from advanced stainless steels such as Cronidur 30 extend service life and lower total cost of ownership, but rare-earth magnet supply risk for maglev rotors is prompting design responses — dual sourcing, magnet-reduced rotor concepts and increased tolerance for lower dysprosium content.
Technology trajectories and product strategy
-
Magnetic levitation versus mechanical bearings. Maglev platforms continue to advance performance, reliability and maintenance economics; however, they introduce different supply-chain exposures (rare-earth magnets, specialized power electronics). Mechanical (oil-lubricated and ball-bearing) architectures remain attractive for certain industrial coatings and retrofit niches because of lower upfront cost and established service networks.
-
Hybrid architectures as a pragmatic bridge. Hybrid designs that combine elements of maglev control with mechanical resilience are emerging as a strategic compromise for customers unwilling to accept full maglev life-cycle trade-offs immediately.
-
Software and systems matter as much as spinning hardware. Digital features — predictive maintenance, remote diagnostics, and intelligent standby — now materially affect procurement choices. OEMs that bundle proven software services alongside validated power-efficiency metrics capture higher aftermarket revenue and improve retention.
Supply chain and cost resilience — what to prioritize now
-
Dual-source critical magnets and bearings. Short-term supplier diversification for rare-earth magnets and advanced stainless alloys is a high-payoff defensive move. Firms should invest in audited second-source qualification and flexible bill-of-materials testing.
-
Vertical or contractual integration for power electronics. Control boards and motor drives are an underappreciated source of differentiation. Securing capacity or preferred pricing for advanced inverter components reduces time-to-market risk for new maglev platforms.
-
Aftermarket and service-first strategies. With replacement cycles longer but service margins higher, developing modular upgrade kits (efficiency retrofits, maglev upgrade paths) and standardized field-service training yields durable margin expansion.
Competitive landscape — who to watch and why
The field is characterized by a mix of established vacuum OEMs and technology-led entrants. The following firms are active players we tracked closely; each has distinct strategic strengths that make them potential partners, competitors or acquisition targets depending on your objectives:
-
Edwards Vacuum — Burgess Hill, United Kingdom — https://www.edwardsvacuum.com. Strengths: broad mechanical turbomolecular ranges (nEXT and STP series) and expanding maglev offerings; notable go-to-market across industrial and analytical segments. Recent visibility at Analytica 2026 underscores channel engagement and field validation efforts.
-
Pfeiffer Vacuum — Aßlar, Germany — https://www.pfeiffervacuum.com. Strengths: comprehensive TURBOPUMPS portfolio spanning mechanical, magnetic and hybrid bearings with strong positioning in high/ultra-high vacuum applications and systems integration capability.
-
Ebara Corporation — Tokyo, Japan — https://www.ebara.com. Strengths: high-throughput maglev turbopumps and strong manufacturing throughput; emphasis on performance and throughput metrics for industrial customers.
-
Leybold — Cologne, Germany — https://www.leybold.com. Strengths: robust TURBOVAC i/iX family tailored to industrial coating and research use-cases; recent product expansion signals continued focus on hardening designs for tough working environments.
-
ULVAC — Chigasaki, Japan — https://www.ulvac.com. Strengths: desktop and mid-range maglev and ball-bearing series with channel focus in Asia; modular product platforms that appeal to OEM integrators.
-
Agilent Technologies — Santa Clara, CA, USA — https://www.agilent.com. Strengths: analytical and research-grade high-vacuum turbo pumps backed by broad customer relationships in instruments and laboratories.
Recent market signals
-
Edwards Vacuum showcased nEXT and STP series alongside T-Station pumping solutions at Analytica 2026 — a signal of continued investment in channel demonstration and turnkey pumping solutions (March 2026).
-
Leybold expanded its TURBOVAC i/iX family with robust variants aimed at industrial coating and research applications — a reminder that ruggedized mechanical platforms retain clear niche relevance (March 2026).
Strategic playbook for 2026 — actions by role
-
OEMs: Prioritize a three-track product roadmap: immediate low-power drive retrofits, medium-term maglev proliferation with supply-chain hardening, and long-term platform redesigns that lower lifecycle emissions. Pair product launches with service bundles to capture recurring revenue.
-
Component suppliers: Move from spot-selling into co-development agreements for bearings and magnet systems. Offer qualification packages and extended warranties to shorten OEM certification cycles.
-
Systems integrators and large end-users: Lock multi-year service contracts and negotiate upgrade credits tied to energy-efficiency performance. Early engagement in OEM R&D roadmaps reduces qualification risk and shortens adoption timelines.
-
Private equity and corporate development teams: Look for tuck-in opportunities in aftermarket services, software-enabled maintenance platforms, and regional service centers to leverage the concentrated market structure and aftermarket margins. Use buy-and-build plays to capture retrofit demand.
What PW Consulting’s full report delivers (practical modules)
-
Detailed market sizing and 2026–2032 forecasts with scenario and sensitivity analyses, including upside and downside demand drivers.
-
Segment-level demand maps (by region, product architecture, and application) and prioritized TAM/SAM/SOM frameworks for commercial planning.
-
Vendor benchmarking with product matrices, technology scorecards, go-to-market positioning, and aftermarket revenue models.
-
Supply-chain risk register (critical components, second-source options, and cost-inflation scenarios) and an implementation playbook for mitigation actions.
-
Commercial playbooks: pricing levers, qualification pathways for semiconductor and life-science customers, RFQ templates, and retrofit upgrade pricing guide.
-
M&A and partnership screening toolkits with candidate lists, valuation guardrails, and integration risk checklists.
Concluding perspective
The turbomolecular pumps market in 2026 is neither nascent nor fully commoditized — it sits in a phase where technical differentiation (bearing architecture, electronics, and software) and regulatory-driven efficiency credentials meaningfully influence commercial outcomes. Firms that move early to secure critical materials, offer service-forward total-cost-of-ownership propositions, and align roadmaps with public-sector energy/CHIPS-driven demand will create asymmetric returns. PW Consulting’s full study provides the granular segment-level maps, vendor scorecards and executable playbooks executives need to prioritize investment and M&A through 2026 and beyond.
To access the complete dataset, supplier scorecards, and the operational playbook referenced above, contact PW Consulting or visit our report portal for licensing and tailored advisory options.
For detailed analysis of this topic, please visit the official page: Turbo Molecular Pumps (Turbomolecular Pumps) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV & Fuel Cell Vehicles Market to Reach USD 539B by 2032
By pmarketresearch, 2026-07-30
Electric Vehicles and Fuel Cell Vehicles Market — Strategic Insights for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concentrated briefing that translates our latest Electric Vehicles (EV) and Fuel Cell Vehicles (FCEV) Market study into immediate strategic value for executives planning 2026 moves. This piece follows a “trailer” approach: it surfaces the analytical rigor and directional findings you need to judge relevance, while preserving the granular segmented datasets and proprietary models that are accessible in the full report.
Electric Vehicles and Fuel Cell Vehicles Market
Executive snapshot — the market in context
Our analysis uses 2025 as the base year, reviews historical trends from 2020–2025, and models a 2026–2032 forecast horizon. The combined EV + FCEV market has transitioned from an emerging growth phase into a structural build-out: from roughly USD 163 billion in 2020 it expanded to about USD 215 billion by 2025, and our baseline forecast projects the market to surpass USD 500 billion by the early 2030s. The modeled compound annual growth rate (CAGR) for the forecast window is 14.06%, reflecting sustained demand, vehicle electrification momentum, and progressive technology cost curves.
Electric Vehicles and Fuel Cell Vehicles Market
These headline numbers frame several practical implications for corporate strategy in 2026: the market is large enough to justify scale investments but still diffuse enough that differentiated plays, partnerships and selective vertical integration can materially change competitive positions.
Electric Vehicles and Fuel Cell Vehicles Market
Why this research matters for 2026 decision-making
- Timing and investment calibration:
With double-digit structural growth baked into our baseline, firms must decide in 2026 whether to accelerate capital deployment (manufacturing, assembly lines, hydrogen fueling partnerships) or to stage investments to capture margin improvement from technology learning curves. The market trajectory supports aggressive scaling for players who can reduce unit costs quickly; it also rewards targeted pilots for those prioritizing route optimization and customer experience.
- Product and portfolio choices:
Automakers and fleets face trade-offs among battery-electric, fuel-cell, and hybrid platforms. Regulation-driven affordability initiatives and shifting consumer segments mean product roadmaps should be optimized not only on unit economics but also on lifecycle emissions compliance and total cost of ownership at the fleet level.
- Supply chain de-risking:
Raw material and component cost targets announced by governments and industry bodies — including fuel cell cost milestones and hydrogen production targets — create actionable procurement triggers. 2026 is the year to lock multi-year agreements, qualify secondary suppliers, and invest in recycling or substitution research to mitigate PGM exposure and upstream bottlenecks.
- Regulatory and market-access playbooks:
New CO2 standards, incentive rebalances and regional policy shifts have made market-entry conditional on well-orchestrated pricing and compliance strategies. Positioning product variants to meet affordability thresholds and navigating region-specific registration dynamics are critical tactical priorities for 2026 launches.
What the report delivers — practical, decision-ready outputs
- High-fidelity market sizing and 2026–2032 forecasts (including scenario and sensitivity analyses).
- Actionable go-to-market roadmaps for OEMs, Tier-1 suppliers, fleet operators, and infrastructure investors.
- Technology and cost trajectories (battery, fuel cell stacks, power electronics, hydrogen handling) with break-even timelines and unit-cost ladders.
- Supplier and partner heatmaps, including capability matrices to expedite procurement and JV screening.
- Regulatory and incentives tracker mapped to commercialization milestones and launch windows.
- Investment case templates, M&A screens, and financial models calibrated to risk-adjusted returns under alternate adoption curves.
- Field-tested pilot blueprints, procurement clauses, and go/no-go decision checkpoints for 0–24 month programs.
Note: the report includes full regional and application segmentations and the underlying datasets that support these deliverables; selective high-level figures and trends are presented here to demonstrate methodological rigor while preserving the proprietary segmentation tables for report subscribers.
Competitive landscape — companies to watch in 2026
- Toyota Motor Corporation (Toyota City, Japan)
Strategic posture: Toyota continues to play a foundational role in fuel-cell commercialization, leveraging product iterations and system-level engineering to expand applicability across passenger, commercial and heavy-duty segments. The company’s announcement of a third-generation fuel cell system slated for multi-region rollout underscores a push to improve durability and lower lifecycle costs. For competitors and partners, Toyota’s scale and system know-how make it both a potential collaborator and a benchmark for component reliability.
- Hyundai Motor Company (Seoul, South Korea)
Strategic posture: Hyundai’s broad product set — spanning passenger vehicles to hydrogen trucks and buses — positions it to capture diverse hydrogen demand pockets. The refresh cycles for fuel-cell models and commercial vehicle developments suggest a playbook focused on platform reuse and aftermarket services as levers to monetize hydrogen ecosystems.
- Honda Motor Co., Ltd. (Tokyo, Japan)
Strategic posture: Honda’s move to produce plug-in fuel cell variants in the U.S. signals an emphasis on localized manufacturing and market-specific product adaptation. This highlights an operational theme for 2026: OEMs that marry regional production footprints with local policy engagement can accelerate market access while containing logistics costs.
- BMW AG (Munich, Germany)
Strategic posture: BMW’s planned series production of fuel-cell vehicles, leveraging collaborative technology pathways, reveals a risk-managed approach to hydrogen. By combining licensing/partnered technology with scaled manufacturing intent, BMW illustrates an approach suited to premium segments where value capture can justify higher early-cycle costs.
- Nippon Shokubai Co., Ltd. (Tokyo, Japan)
Strategic posture: Component and catalyst innovators are critical enablers of cost reduction. Advances in platinum-group-metal-free catalysts and related materials science are a lever for industrial players to outflank raw-material constraints and to reduce stack costs — an outcome that materially affects heavy-duty total cost equations.
Complementing these OEM and supplier dynamics, product expansions from specialist suppliers (hydrogen recirculation, blowers, system integrators) are sharpening the ecosystem, creating new supplier niches and partnership options. The market concentration metrics indicate a relatively unconsolidated landscape, providing opportunities for agile entrants and focused consolidations.
Industry dynamics and critical external signals
- Policy acceleration: Tighter CO2 standards and region-level mandates are reshaping pricing and portfolio decisions; affordability-driven product introductions are increasingly important.
- Adoption scale: Global electric car sales hit record volumes in 2025, reinforcing electrification as mainstream; this scale validates network and after-sales investments.
- Cost targets: Public-sector technology targets for fuel cell stack costs and hydrogen production create clear commercial inflection points — hitting those targets materially improves heavy-duty and long-haul business cases.
- Localized friction points: Early signs of registration slowdowns in some FCEV registries highlight the need to pair vehicle launches with refueling infrastructure and customer value propositions.
Scenario planning — triggers that change the game
- Base case: Realization of the modeled CAGR and infrastructural rollouts in line with public targets; gradual cost declines enable broadening commercial adoption.
- Upside case: Faster-than-expected hydrogen production cost reductions and accelerated fuel-cell cost improvements unlock rapid heavy-duty electrification and industrial-scale fleet conversions.
- Downside case: Raw-material shocks, slower infrastructure scaling, or policy reversals compress adoption rates and push ROI timelines beyond early investors’ thresholds.
Concrete 2026 actions — prioritized
- Immediate (0–12 months):
Secure supply hedges for key materials, finalize pilots with targeted fleet partners, and lock conditional offtake or offtake-linked financing for infrastructure projects. Use modular procurement templates to speed RFP cycles while retaining flexibility for design evolution.
- Near-term (12–36 months):
Scale production in regions where regulatory and cost conditions align, negotiate technology partnerships for stack and system integration, and build bundled service offerings (vehicle + refueling + telematics) to improve payback for fleet customers.
- Strategic (36+ months):
Pursue consolidation in targeted supplier segments, vertically integrate critical modules if warranted by scale economics, and consider cross-sector alliances to accelerate hydrogen supply and amortize infrastructure investments.
Final word — using this research in 2026
The 2026 strategic window is defined by a large and fast-growing total market, significant technology milestones within reach, and uneven but accelerating infrastructure development. PW Consulting’s EV & FCEV Market study equips decision-makers with the scenario-based forecasts, cost curves, supplier maps and executable playbooks needed to convert market opportunity into competitive advantage. If your 2026 decisions involve capacity commitments, product launches, M&A, or infrastructure investments, the full report will provide the segmented forecasts, model inputs and executable templates to move from intent to impact.
To access the complete datasets, regional and application breakdowns, and the operational toolkits referenced above, please consult the PW Consulting EV & FCEV Market report page or contact our advisory team to arrange a briefing and licensing of the full analytical package.
For detailed analysis of this topic, please visit the official page: Electric Vehicles and Fuel Cell Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Heat Guns Market to Hit USD 2,185.8M by 2032 at 4.3% CAGR
By pmarketresearch, 2026-07-30
Heat Guns Market 2026 Strategic Brief: Why This Report Will Shape Your Decisions
Executive summary
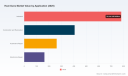
As strategic decision-makers prepare plans for 2026, understanding the structural trajectory of the heat guns market is no longer optional — it is mission critical. PW Consulting’s latest market research uses a 2025 base year and a 2026–2032 forecast window to map a market that has moved from recovery into structurally supported expansion. Our topline model places the global market at approximately USD 1,613.6 Million in 2025 and projects it to reach roughly USD 2,185.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of 4.3% across the forecast period. Historical trends from 2020 through 2025 show steady expansion with episodic volatility tied to macro cycles and supply-side shocks — context that underpins our forward scenarios.
Heat Guns Market
Beyond raw growth, market structure matters. Competitive concentration is meaningful: the three largest manufacturers control a clear majority of industry revenue, while the five largest firms account for an even larger share. This dynamic creates both barriers and levers for incumbents and challengers — scale delivers distribution and R&D advantages, while pockets of fragmentation leave room for targeted disruption.
Heat Guns Market
What the PW Consulting report delivers (practical, actionable content)
This study is designed for executives, corporate development teams, product leaders, and commercial strategists who need immediately actionable insight rather than academic description. Key deliverables include:
Heat Guns Market
- Robust market sizing and forecasting models (base year 2025; forecast 2026–2032) with transparent assumptions and scenario variants (baseline, upside, downside).
- Proprietary demand-driver decomposition that links end-market activity, channel shifts, and technology adoption to volume and revenue outcomes.
- Competitive benchmarking across product capabilities, channel reach, and non-price propositions (warranty, service, digital features).
- Commercial playbooks for product portfolio optimization, channel segmentation, pricing strategies, and after-sales monetization.
- Supply chain and cost-structure maps highlighting supplier concentration, single-sourcing risks, and relocation options.
- M&A target screening and value creation templates for bolt-on and roll-up scenarios, together with integration risk checklists.
- Regulatory and safety compliance matrix with jurisdictional triggers and cost-to-compliance estimates.
- Excel-based sensitivity tools and slide-ready strategic roadmaps that can be adapted to corporate constraints and investment horizons.
We intentionally present synthesis, strategic implications, and diagnostic tools in this brief; detailed subsegment-level datasets (by type, application, and region), including granular percentage splits and downloadable tables, are reserved for the full report and our client portal.
Strategic implications for 2026 decision-makers
The macro trajectory (CAGR 4.3% to 2032) and the concentration profile produce a set of strategic priorities you should adopt immediately if you want to convert market tailwinds into durable advantage:
- Prioritize product differentiation linked to professional use-cases. Growth is being driven by professional and industrial demand that values robustness, temperature precision, and serviceability. Commodity models will face margin pressure — invest selectively in features and extended warranties that create lock-in.
- Accelerate cordless and energy-efficiency roadmaps. Advances in battery chemistry and motor efficiency are enabling cordless form factors that are attractive to professional users and retrofit channels. Early movers who combine battery systems with proprietary thermal control software capture premium price points.
- Design channel strategies for dual distribution models. The market favors both traditional distributor networks (professional/industrial buyers) and big-box/DIY channels. Successful firms maintain differentiated SKUs, pricing ladders, and logistics playbooks for each channel rather than a one-size-fits-all approach.
- Monetize after-sales services and consumables. Consumable elements (nozzles, filters), maintenance contracts, and rapid-replacement programs are low-effort levers to increase lifetime value in a market where product cycles are measured in years.
- Use M&A to fill capability gaps, not just revenue. With top players holding a majority of market share, disciplined bolt-ons that add battery expertise, heat-control electronics, or service networks often unlock more value than horizontal roll-ups alone.
- Fix supply-chain resilience as a strategic objective. Raw-material swings and component shortages materially affect lead times. Dual-sourcing strategies, near-shore options, and inventory-as-a-service should be stress-tested in 2026 budgets.
- Embed sustainability and safety in product roadmaps. Regulatory scrutiny and procurement preferences are shifting to lower embodied energy and safer end-of-life profiles. These are not compliance costs alone — they are differentiators.
Competitive landscape: what the leading manufacturers are signaling
Our competitive analysis profiles the major incumbents and their strategic postures. Across the landscape, several consistent patterns emerge:
- Large global tool OEMs — including established players headquartered in Japan, Germany, and the United States — leverage strong channel partnerships and broad product portfolios to defend professional and consumer demand. Their assets include scale manufacturing, recognized brands, and deep distribution.
- Specialist manufacturers — focused on hot-air technology and professional applications — compete on thermal control, ergonomics, and service propositions. For many buyers, product-level performance and trusted durability trump headline price.
- Newer entrants and regional specialists — particularly those emphasizing cordless and energy-efficient designs — are using narrow product differentiation and aggressive channel partnerships to gain footholds.
Company-level strategies that matter in 2026:
- Invest in cordless ecosystems: firms that can pair heat guns to a common battery platform across tools create cross-selling synergies and higher customer switching costs.
- Optimize aftermarket revenue: warranty extensions, consumables, and service contracts are practical routes to margin expansion even in mature segments.
- Leverage distribution intelligence: real-time channel analytics and differentiated SKUs per channel reduce stock-outs and deepen shelf presence.
For organizations evaluating partnerships, licensing, or acquisition targets, our report includes an executable matrix that ranks prospective counterparties by technology fit, geographic reach, and integration complexity.
Risks and leading indicators to monitor through 2026
Strategic planning must be scenario-ready. Monitor these leading indicators closely to recalibrate decisions mid-course:
- Battery and component cost curves — significant improvements will accelerate cordless adoption and compress price elasticities.
- Regulatory shifts in electrical safety and emissions — new standards can create short-run compliance costs and long-run market advantage for early adopters.
- Construction and industrial activity indices — demand sensitivity remains highest to capex and renovation cycles.
- Channel inventory and sell-through rates — divergence between distributor inventories and point-of-sale can signal pending price competition or supply constraints.
- Consolidation activity among mid-tier suppliers — rapid roll-ups can change supplier bargaining power overnight.
How PW Consulting can accelerate your 2026 agenda
PW Consulting couples deep industry bench strength with hands-on commercial execution. If you engage with us, we will:
- Deliver a compact executive dashboard (KPIs and triggers) tailored to your product portfolio and markets of interest.
- Run a rapid commercial due diligence stream for M&A targets, with integration playbooks and 100-day value-capture plans.
- Co-create product and channel pilots that test cordless, service-based, and premium-performance propositions in controlled geographies.
- Provide workshop-based alignment with sales, product, and operations to translate market scenarios into 2026 budgets and R&D roadmaps.
Next steps — why the full report matters
This brief highlights the strategic vectors that will shape success in 2026. To act with conviction, you need the full set of granular inputs that inform investment sizing, SKU-level pricing, and regional go-to-market sequencing. While this introduction surfaces the market’s trajectory, concentration dynamics, and practical implications for corporate strategy, the detailed subsegment datasets (by type, application, and region), supplier lists, and modeled scenarios are intentionally withheld here to preserve actionable exclusivity in the full PW Consulting deliverable.
For leaders who must translate a 4.3% forecast CAGR and a structurally consolidating landscape into profitable action: secure the full report, adopt a prioritized execution plan, and treat 2026 as the year to convert product and channel investments into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Heat Guns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Copper Sulfate Pentahydrate Market to Hit USD 576.8M by 2032 (5.4% CAGR)
By pmarketresearch, 2026-07-30
Copper Sulfate Pentahydrate Market: Strategic Intelligence for 2026 Decision-Making
Executive trailer
As companies realign supply chains and product portfolios for the post‑pandemic and decarbonization eras, Copper Sulfate Pentahydrate emerges as a quietly critical intermediate across agriculture, feed, electroplating and specialty industrial applications. This PW Consulting briefing introduces our full Copper Sulfate Pentahydrate Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) and explains why the insights it contains are indispensable for boardrooms and procurement teams planning for 2026.
Copper Sulfate Pentahydrate Market
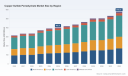
Key macro position: the global market, measured in USD Million, expanded from approximately 315.2 in 2020 to 402.5 in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 5.4% through 2032 — reaching an estimated 576.8 by 2032. These topline dynamics reflect the combined effects of agricultural demand resilience, selective industrial recovery, and periodic supply shocks that amplify volatility in certain grades.
Copper Sulfate Pentahydrate Market
Why this report matters for 2026 strategy
-
Operational resilience: the market’s steady mid‑single‑digit CAGR masks episodic supply and quality disruptions that can rapidly cascade into production stoppages or costly recalls. Companies that treat copper sulfate as a strategic raw material — not a commoditized, low‑touch buy — will avoid expensive remediation.
Copper Sulfate Pentahydrate Market -
Regulatory and reputational risk: recent regulatory activity (notably a voluntary recall in April 2026 of contaminated feed‑grade lots originating from China) underscores the need for traceability, batch testing, and contract clauses that allocate recall costs. The recall and confirming reports of dioxin contamination have already prompted faster adoption of upstream verification protocols among North American and European buyers.
-
Commercial differentiation: as customers demand higher‑assurance materials (GMP/USP/FCC/technical certificates, documented supply chains, and product stewardship), producers with certified quality systems and transparent traceability can capture premium pricing and longer contracts.
-
M&A and vertical plays: the market’s structure and pockets of regional specialization create tactical opportunities for acquisitive buyers to secure high‑purity feeds, backward integrate into feed‑grade production, or establish regional hubs that reduce lead times and import risk.
What the full report delivers (practical, transaction‑ready content)
-
Robust market sizing and forecast model (USD Million; 2020–2032) with build‑up logic and sensitivity toggles to test price, feedstock availability and regulatory stress scenarios.
-
Demand driver diagnostics by grade and application, with elasticities and scenario impacts (presented qualitatively in this preview; granular subsegment volumes and shares are reserved for the full report to maintain competitive value).
-
Supply map and capacity registry covering global producers, conversion facilities, and logistical chokepoints; includes lead‑time benchmarks and alternative routing playbooks for emergency sourcing.
-
Supplier due‑diligence toolkit: audit checklists, required certificate templates, in‑market testing regimes and contract language to mitigate contamination risk and supplier non‑performance.
-
Price build and trade dynamics: raw‑material drivers, pass‑through analysis, and a proprietary pricing deck for use in negotiation and budgeting.
-
Regulatory tracker and recall playbook: mapping of current controls across major markets, recall impact scenarios, insurance considerations and crisis communication templates.
-
Competitive landscape intelligence: profiles and strategic positioning of key players, capability matrices, and a short list of potential targets and partners for buyers and investors.
-
Actionable growth roadmaps: go‑to‑market plays, cost‑to‑serve optimization, and a prioritized list of tactical initiatives with expected ROI and implementation timelines for 6–24 months.
High‑level competitive landscape and strategic implications
The Copper Sulfate Pentahydrate market sits in a middle ground of specialization: several established producers serve distinct channels (pharma/nutraceutical, agricultural, feed, electroplating, and industrial uses), while many smaller suppliers address local commodity demand. The market is best characterized as moderately fragmented: the largest regional players collectively do not exert dominant, global pricing control, leaving room for consolidation and margin capture through quality differentiation and logistics efficiency.
-
Shreeji Industries (India) — GMP‑certified manufacturer supplying IP/BP/USP/FCC grades. Strengths: pharmaceutical‑grade credentials, multi‑grade capability and a clear focus on higher‑value channels (nutraceuticals, fungicides, electroplating). Strategic implication: potential partner or acquisition target for firms seeking a certified, Asia‑based, quality‑assured source and faster entry into regulated markets.
-
Sulfozyme Agro India Pvt Ltd (India) — supplier oriented to agricultural and technical grades for plant nutrition, fungicide formulations and feed additives. Strengths: proximity to large agricultural demand pools, specialized technical grade production. Strategic implication: attractive for agricultural chemical formulators that require integrated supply and formulation co‑development; also a candidate for off‑taker agreements or joint quality uplift programs.
-
Univerical (United States) — North American manufacturer of high‑purity liquid and crystalline products for electroplating and industrial uses. Strengths: regional manufacturing, focus on high‑purity and plating‑on‑plastics niches, shorter lead times for North American customers. Strategic implication: natural partner for Western buyers seeking to reduce import dependency and to secure more consistent quality for industrial applications.
Each player illustrates a strategic axis buyers should evaluate: quality certification (GMP/USP/FCC), geographic risk (local production vs. import dependence), and channel focus (agriculture/feed vs. electroplating/industrial). The full report contains head‑to‑head capability matrices and supplier scorecards that buyers can use immediately in sourcing decisions.
Supply‑chain vulnerability spotlight — the 2026 contamination episode
April 2026 saw a voluntary recall of contaminated feed‑grade Copper (II) Sulfate Pentahydrate lots originating from China, reported by the Animal Nutrition Association of Canada and flagged by national food safety authorities. The contamination—associated with dioxin residues—has tangible operational implications:
-
Immediate testing and batch hold policies are now business‑critical for feed and agricultural formulators selling into regulated markets.
-
Buyers must reassess audit frequency, third‑party lab validation, and contractual warranties to allocate recall and remediation costs.
-
Regionalization of supply (or strategic inventory buffers) may be justified despite added holding costs for customers with zero‑tolerance product profiles.
The PW report contains a forensic appendix on the recall, a recommended lab‑testing protocol, and a supplier‑risk matrix that quantifies expected disruption costs under multiple contamination scenarios.
Strategic recommendations for leadership teams planning in 2026
-
Procurement: shift from single‑source spot buys toward blended buying strategies: certified regional suppliers for critical applications and vetted global suppliers for cost flexibility. Implement mandatory incoming batch testing for feed and pharma grades.
-
Quality & Regulatory: prioritize suppliers with third‑party certifications and documented chain‑of‑custody. Insert contractual clauses for recall liability, and secure contingent supply agreements with tested alternates.
-
Operations: evaluate regional buffer stocks and near‑shoring for high‑assurance grades. Rebalance safety stock vs. working capital to reflect the realized risk premium post‑recall.
-
Commercial & R&D: explore premiumization for traceable, certified grades and invest in formulation changes that reduce copper sulfate dependence where possible (or increase recrystallization/upgrade steps to capture margin).
-
M&A & Partnerships: screen targets that provide quality uplift, regional manufacturing, or access to regulated markets. Consider minority investments in certified producers to secure preferential supply.
-
Risk & Finance: stress‑test budgets with the PW forecast scenarios (base, supply shock, regulatory tightening) and ensure insurance coverage aligns with identified recall exposure.
How to use this briefing and next steps
This article is a focused executive preview designed to communicate the strategic value embedded in our full market study. For procurement teams, the buyer’s toolkit and supplier scorecards are immediately actionable. For corporate strategy and M&A teams, the sector mapping and candidate shortlists accelerate diligence. For R&D and product teams, the formulation impact assessments spotlight opportunities to reduce raw material intensity or develop premium, differentiated product lines.
The complete PW Copper Sulfate Pentahydrate Market report contains the granular sub‑segment volumes, regional and application splits, price decks, full company profiles and the quantitative scenario models that underpin the recommendations summarized above. Those detailed elements are intentionally held in the full report to preserve competitive advantage — and they are precisely what your commercial and sourcing teams will need to operationalize 2026 plans.
Call to action
To obtain the full dataset, supplier scorecards, risk matrices and the downloadable forecast model (2026–2032), visit our report page or contact PW Consulting’s industry team. If you are preparing 2026 budgets, negotiating multi‑year offtake agreements, or evaluating acquisition targets, securing the complete intelligence now will materially shorten decision cycles and reduce execution risk.
For detailed analysis of this topic, please visit the official page: Copper Sulfate Pentahydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gibberellin Acid Market Poised for 8.15% CAGR Through 2032 — PW Consulting
By pmarketresearch, 2026-07-30
Gibberellin Acid (GA) Market — Strategic Outlook for 2026 Decision-Makers
Executive summary: why this briefing matters for 2026 strategy
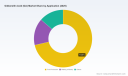
As companies reset budgets and strategic priorities for 2026, plant growth regulators — and gibberellin acids (GAs) in particular — have moved from niche tool to an operational lever across fruit production, specialty crops, malting and turf management. Our market modelling shows a clearly accelerating revenue trajectory from a 2025 base to 2032, underpinned by sustained demand for yield/quality improvement, regulatory reclassifications, and manufacturing innovation. The market, measured in USD Million, grew through 2020–2025 and, with a compound annual growth rate of 8.15% over the forecast window, reaches materially higher absolute scale by 2032.
Gibberellin Acid (GA) Market
For executives evaluating portfolio allocation, M&A, commercial expansion or manufacturing investments in 2026, this report functions as both a decision support tool and a competitive intelligence compass: it validates the commercial opportunity in headline metrics while reserving the granular, actionable segment tables and price-volume curves for licensed subscribers.
Gibberellin Acid (GA) Market
Market trajectory at a glance (base year and forecast)
- Base year: 2025 (established as our anchor for model calibration)
- Forecast horizon: 2026–2032
- Compound annual growth rate (CAGR): 8.15% across the forecast period
- Our bottom-line view: the GA industry transitions from steady supplementation to strategic crop-management adoption, with 2026 representing the inflection year when product innovation and regulatory clarity converge to expand commercial pathways.
To give executives a sense of scale without substituting for contract-level market data: the modelled market expands meaningfully year-on-year from the 2025 anchor into the 2026–2032 window, reflecting both volume-driven adoption and value accrual from higher-margin formulation innovations. Our financial modelling is denominated in USD Million and supports scenario analysis at range-bound, base-case and upside assumptions — all available in the full report.
Gibberellin Acid (GA) Market
Key dynamics shaping the GA market in 2026
- Regulatory clarity and re-registration cycles. Recent regulatory activity at both regional and federal levels has reduced compliance uncertainty. Notable administrative updates and renewal processes in 2025–2026 have created predictable windows for formulators and registrants to secure or expand labeled uses. Firms with regulatory bandwidth can convert this predictability into faster label extensions and broader crop claims in 2026.
- Product innovation pushes premiumization. The market is seeing formulation-led differentiation — lower-volatility concentrates, organic-eligible registrations and crop-specific blends that unlock new use-cases (e.g., delayed ripening, shelf-life extension, cell expansion). Recent product introductions demonstrate the willingness of large agri-players to seek higher-margin, value-added PGR offerings.
- Manufacturing and input-cost evolution. Advances in fermentation and bioprocessing — including probiotic-enabled fermentations and other optimized bioproduction techniques adopted late in 2025 — have improved unit economics across the supply chain. This both compresses cost for bulk suppliers and permits reinvestment in formulation R&D for differentiated products.
- Commercialization and channel sophistication. Adoption is being driven not only by price and efficacy but by better integration into agronomic service models, supply-chain partnerships with packers/processors, and digital agronomy that quantifies GA impact on post-harvest value. Companies that treat GA products as a service — combining application timing, analytics and crop-rotation playbooks — will capture disproportionate share of value.
- Market structure and concentration. The competitive landscape is moderately fragmented: aggregate concentration metrics highlight that the top three to five players do not dominate to the degree seen in other agrochemical segments. This structural openness creates opportunity for fast-followers and specialists to scale via targeted shelf-space, channel partnerships and formulation niches.
Competitive landscape — how leading players are positioning (implications for partners and rivals)
The GA market combines legacy agrochemical incumbents, specialty formulators, and large regional producers. Key actors illustrate distinct strategic archetypes:
- Platform incumbents focused on brand & channel (example: Valent BioSciences, Nufarm, Corteva). These players leverage established distribution networks, registered labels, and brand trust to commercialize full-channel rollouts. Their advantage lies in integrated marketing to growers and in regulatory resources to expand labeled uses. Expect these firms to prioritize high-visibility crop segments and formulations with clear ROI stories.
- Specialty formulators and turf/aquatic specialists (example: Fine Americas, SePRO, Greenleaf Chemical). These companies compete on tailored formulations and technical support for horticulture, ornamentals and turf. They are natural partners for packers and nursery chains seeking customized dosing and application timing.
- Cost-competitive bulk producers (example: Jiangsu Fengyuan, Zhengzhou Delong). Producers with scale in bulk GA synthesis or fermentation can underwrite competitive pricing and supply reliability. Their strategic path is either to remain B2B suppliers to formulators or to pursue forward integration into branded lines where channel access exists.
- New product entrants and organic-eligible offerings (example: Corteva's recent launch). Companies launching low-volatile, organic-eligible formulations are targeting premium segments and sustainability-focused customers. These launches signal that regulator-approved, market-differentiated GA products can command higher price points and may catalyze adoption in crops previously unconvinced by conventional formulations.
For 2026, strategic actions by competitors will cluster around three playbooks: (1) accelerate label expansion and OMRI/organic clearances; (2) scale margin-enhancing formulations and service bundles; (3) secure raw-material sourcing via long-term supply agreements or backward integration. Firms pursuing multiple tracks simultaneously will require careful capital allocation and disciplined go-to-market sequencing.
Where the commercial opportunities lie — pragmatic scenarios for 2026
- Premiumization in high-value fruit and specialty crops. Grower willingness to pay increments for quality and shelf-life improvements creates an attractive avenue for higher-margin formulations. Sales teams should refocus on packer contracts and post-harvest service propositions.
- Service-led adoption in malting and industrial crops. In segmented, process-sensitive applications, integrating product application with agronomic advisory services reduces user hesitation and locks in annuity revenues.
- Channel rollups and co-pack agreements. Distributors and regional formulators can secure supply and margins by signing multi-year supply or co-manufacturing deals with bulk producers — an effective hedge against short-term price volatility.
- Regulatory arbitrage through targeted registrations. Prioritize territories and label claims where the regulatory timeline offers first-mover advantage in 2026–2027.
What the full report contains — practical deliverables for strategy teams
Our full Gibberellin Acid Market study is structured for operational use by commercial, regulatory, and M&A teams. It includes:
- Detailed historical and forecast revenue series (2020–2032) denominated in USD Million, with scenario sensitivity and unit-volume drivers;
- Segment-level demand drivers, pricing dynamics and margin matrices (note: granular segment tables and proprietary share estimates are gated for subscribers);
- Regulatory matrix and timeline by jurisdiction, highlighting re-registration windows, label extension pathways and compliance cost estimates;
- Supplier and channel maps with risk heatmaps for raw-material concentration, logistics exposure and single-source dependencies;
- Commercial playbooks — go-to-market frameworks for branded formulations, service bundles, and contract manufacturing partnerships;
- Due-diligence checklist and valuation heuristics for potential M&A targets in bulk, formulation, and channel assets;
- Appendix of primary and secondary sources, including recent product launches and regulatory notices for 2025–2026.
How to use the insights in 2026 planning cycles
- Board level: Use our scenario outputs to stress-test capex asks tied to new formulation lines or fermentation capacity, and to inform M&A premium tolerance for strategic acquisitions.
- Commercial leaders: Revisit channel incentives and pricing tiers using the report’s margin ladder and breakeven timelines; prioritize crops and packer relationships where shelf-life premiumization creates the sharpest ROI.
- R&D and registration teams: Align pipeline priorities with regulatory windows and product features that unlock premium status (e.g., low-volatility, organic-eligible formulations).
- Supply chain and procurement: Reconfigure supply agreements to insulate against feedstock volatility and to capture benefits from improved bioprocess economics.
Closing — the strategic playbook for 2026
Gibberellin acids are no longer a specialist curiosity: they are a strategic lever in crop-value engineering. Our modelling — anchored on a 2025 base year and projecting forward to 2032 at a compound annual growth rate of 8.15% — shows a market that rewards both operational excellence in production and commercial sophistication in go-to-market. The competitive field is sufficiently open that disciplined entrants can capture share, but success in 2026 will be decided by three capabilities: regulatory execution, formulation differentiation, and integration into customer value chains.
This article is a high-level preview of the analytical depth available in PW Consulting’s full Gibberellin Acid (GA) Market report. To review the complete segment matrices, proprietary share estimates, and ready-to-execute playbooks that support board-level decisions in 2026, please consult the full study on our website.
For detailed analysis of this topic, please visit the official page: Gibberellin Acid (GA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Rubber market to hit USD 344.8M by 2032 at 5.86% CAGR
By pmarketresearch, 2026-07-30
Natural Rubber Market 2026: Strategic Outlook and Decision-Grade Insights
As PW Consulting’s senior industry analyst, I present a concise, decision-focused preview of our 2026 Natural Rubber Market study. This briefing synthesizes the authoritative market sizing, trajectory and strategic implications that corporate leaders, procurement heads and investors need to act with confidence in 2026 — while preserving the granular, transaction-grade datasets for readers who access the full report.
Natural Rubber Market
Executive snapshot
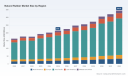
The natural rubber market has demonstrated steady recovery and expansion through the 2020–2025 historical window, with our base year set at 2025. Measured in USD (Million), total market revenue moved from an earlier cycle low to an elevated 2025 level and — under our central forecast path — is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of approximately 5.86%. By 2032 the market reaches a materially larger scale, reflecting demand resilience in key applications and structural supply dynamics that will shape strategic choices in 2026.
Natural Rubber Market
Why this study matters for 2026 decision-making
- Actionable foresight: The report translates macro growth (2020–2025 history and a 2026–2032 forecast horizon) into tactical signals for procurement windows, contract tenors and inventory policy. It identifies time-sensitive inflection points where supply constraints and regulatory milestones converge.
- Risk-to-return mapping: We connect physical supply risks, commodity price drivers and evolving sustainability rules to quantify downside exposure for manufacturers and traders — enabling calibrated capital allocation and hedging strategies.
- Competitive advantage: The study surfaces strategic levers for producers and processors — from traceability investments and upstream partnerships to premium product positioning — that can convert regulatory compliance into price differentiation and margin capture.
Market trajectory and underlying drivers
The market’s recent expansion is neither accidental nor uniformly distributed: structural demand from mobility and industrial rubber goods plus cyclical restocking drove the recovery through 2025. Our forecast to 2032 assumes continued urbanization, vehicle parc growth in emerging markets and a shift in product mixes toward higher-value latex and specialty grades. On the supply side, natural rubber’s biological production cycles, land-use constraints and climate variability create a baseline of limited elasticity — meaning supply shocks propagate quickly into availability and commercial terms.
Natural Rubber Market
Key drivers that executives must monitor in 2026 include:
- Regulatory compliance costs and traceability requirements that raise the marginal cost of sourcing from opaque supply chains.
- Climate and weather risk affecting core producing regions and smallholder yields, which can compress supply in short windows.
- Downstream substitution and product innovation trends (e.g., synthetic blends, engineered elastomers) that alter premium spreads and long-term demand composition.
Regulatory inflection: EUDR and the new compliance horizon
Regulatory changes in 2026 create a firm, date-certain obligation for market participants interacting with the EU: supply-chain traceability and no-deforestation evidence will be mandatory for natural rubber and rubber-based products placed on the EU market. This is not a distant policy risk — it is a near-term operational reality that impacts onboarding, certification timelines and supplier qualification. Large operators should assume immediate resource needs for plot-level traceability, third-party verification pathways and supplier engagement protocols.
Supply dynamics and the short-term shock layer
Beyond structural constraints, the market’s short-term risk profile has been elevated by episodic production disruptions. Recent extreme-weather episodes in key producing geographies have tightened available volumes and exposed the limits of spot-market flexibility. For 2026 planning, commercial teams must treat weather-related production disruptions as persistent tail risks and stress-test supply scenarios across a range of durations and intensities.
Competitive landscape — what the market structure implies
The natural rubber processing and exporting segment is dominated by several integrated, vertically proficient players that combine plantation exposure, processing scale and global trading networks. These firms — ranging from large Thai processors to Malaysia- and Vietnam-based integrated groups — set commercial norms for quality specification, service levels and traceability capabilities. For buyers, this concentration translates into a twofold strategic reality:
- Counterparty stability: long-term contracts with established processors can reduce volatility in physical availability and support traceable sourcing commitments.
- Supplier power: concentrated processing capacity gives leading processors leverage to enforce premium structures for certified, compliant material and to set delivery terms during constrained periods.
Our full study profiles the leading processors and exporters in depth, assessing their asset footprints, sustainability programs and supply-chain reach. We identify which players are positioned to meet traceability requirements and which may face capital or operational constraints as compliance timelines accelerate.
What practical, operable content the full report contains
- Methodology and assumptions: base year (2025), historical window (2020–2025), forecast horizon (2026–2032), currency and units, and sensitivity scenarios around price and supply shocks.
- Top-line market sizing and growth trajectory, with scenario-based forecasts under alternative demand and supply pathways.
- Supply-chain mapping and risk heatmaps that identify geographic, operational and governance exposures at each node of the value chain.
- Regulatory impact assessment: compliance playbooks for EUDR readiness, auditability pathways and supplier engagement templates.
- Commercial playbook: procurement tactics, contract structures, inventory optimization heuristics and hedging instruments calibrated to rubber market behavior.
- Competitive benchmarking: executive summaries of major processors and suppliers, their strategic strengths and gaps, and M&A/partnership opportunities.
- Executive dashboards and data annexes: downloadable tables, forecast series and scenario outputs suitable for board-level briefings and procurement systems.
Practical strategic recommendations for 2026
Based on our integrated analysis, we recommend that market participants prioritize the following actions in 2026:
- Operationalize traceability now: invest in plot-level traceability pilots with a subset of suppliers and align contractual terms to on-ramp compliance documentation. Delay increases implementation risk and cost.
- Diversify sourcing across supplier archetypes: combine relationships with integrated processors, regional aggregators and certified smallholder cooperatives to balance cost, traceability and resilience.
- Adopt a layered procurement approach: blend short-term spot purchases (for flexibility) with multi-year supply agreements tied to sustainability milestones and index-linked pricing.
- Invest in supplier capacity building: co-fund yield-improvement and sustainability programs with trusted suppliers to reduce future compliance costs and secure preferential access to certified volumes.
- Prepare contingency capital: maintain liquidity buffers and pre-arranged credit lines to act quickly when physical availability tightens and premiums emerge.
- Assess strategic M&A and alliance targets: prioritize assets that provide traceable supply, processing control or technological capability (e.g., traceability platforms, analytics providers) that can be integrated within 12–18 months.
Implications for investors and financial sponsors
The market’s mid-term growth path and concentrated processing base create selective investment opportunities. Value capture will favor firms that can credibly de-risk supply chains against regulatory and climate shocks, demonstrate premium product differentiation and scale traceability economically. Our report surfaces targets and partnership models that can de-risk buyer portfolios and accelerate revenue capture in certified product lines.
Why this is a ‘trailer’ not the full movie
This article is intended to surface the strategic contours you need to act in 2026 — the full report contains the granular segmentation, regional allocation, application-level demand detail and downloadable time-series data you will require to operationalize the recommendations. We deliberately withhold the transaction-level tables and subsegment percentages here so that decision-makers can access the validated datasets through the report portal and apply them directly to commercial models, risk systems and board materials.
Next steps
- Procurement and supply-chain leaders should request our compliance playbook to begin traceability pilots this quarter.
- Strategy and corporate development teams should book a briefing to review our supplier scorecards and prioritized M&A targets.
- Investors and traders: contact PW Consulting for the full forecast tables, scenario outputs and bespoke valuation overlays.
PW Consulting’s Natural Rubber Market report is built to be a practical tool for 2026: rigorous in method, targeted in recommendations and executable at commercial scale. For the full datasets, segment-level analysis and proprietary company benchmarking that underpin these conclusions, please access the complete report on our website or contact our team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Natural Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com