

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Vitamin D Testing Market to Hit USD 1,985.5M by 2032 at 8.15% CAGR
By pmarketresearch, 2026-07-30
Vitamin D Testing Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive summary
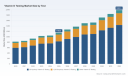
As healthcare stakeholders enter 2026, Vitamin D testing remains a high-velocity segment within clinical diagnostics. Our proprietary market model puts the global market at approximately USD 1.15 billion in 2025, and—assuming the central scenario—rising toward the USD 2.0 billion range by the end of our forecast window in 2032, driven by an 8.15% compound annual growth rate. These headline figures mask a rapidly evolving competitive, regulatory, and reimbursement landscape. This preview surfaces the strategic consequences for manufacturers, clinical laboratories, payers, and investors while intentionally withholding the granular regional and sub-segment worksheets included in the full PW Consulting report; those datasets are available through our secure report portal.
Vitamin D Testing Market
Market trajectory and growth dynamics
The Vitamin D testing market is moving from episodic demand—driven by seasonal screening and specific clinical indications—toward more integrated, protocolized testing across primary care and specialty pathways. The market’s mid-single-digit-to-high-single-digit trajectory over the 2026–2032 forecast period reflects three structural forces:
Vitamin D Testing Market
- Clinical expansion: growing clinician awareness of extra-skeletal roles of vitamin D and guideline updates that broaden testing triggers in certain patient cohorts.
- Technological substitution: a sustained shift toward higher-specificity assay platforms (including mass spectrometry and next-generation immunoassays), which changes unit economics and capital intensity for laboratories.
- Reimbursement and policy reconfiguration: a flurry of local coverage decisions and billing guidance that is tightening claim adjudication in some channels while opening opportunity windows in others.
For strategic planning, the core implication is that topline growth is available, but access to that growth will be uneven across channels and geographies depending on reimbursement alignment, laboratory capability, and go-to-market execution.
Vitamin D Testing Market
Regulatory, reimbursement and policy context
Regulatory and payer actions are shaping near-term access and long-term demand patterns:
- Regulatory classifications and test complexity designations are material. A notable development in late 2025 saw a mass spectrometry–based 25-hydroxy vitamin D assay categorized as Moderate Complexity—an event with immediate implications for decentralization and laboratory-sourcing models.
- Medicare and payer guidance continues to evolve. The retirement of certain Medicare local coverage guidance in mid‑2025 and selective revisions to billing and coding documents have created both compliance risk and opportunities for labs that can evidence medical necessity under updated LCD criteria.
- Commercial payers are refining policy language: several plan-specific updates in 2025–2026 now emphasize diagnosis-code alignment and prior authorization rules linked to discrete CPT and proprietary codes.
Decision-makers must therefore bake policy-sensitivity into their 2026 plans: a product launch or price change that looks attractive on raw market growth can be derailed by shifting CPT/LCD interpretations or plan-level claim edits.
Competitive landscape — concentrated but dynamic
The market’s concentration is meaningful but not immovable. PW Consulting’s competitive analysis shows a moderately consolidated supplier base: three-firm concentration and five-firm concentration metrics indicate incumbent strength, yet there remains room for niche innovators and vertically integrated labs to capture value. Key players that shape industry structure include:
- Roche Diagnostics — with a strong clinical sales and service footprint; recent regulatory milestones around mass spectrometry testing materially shift the accessibility of higher-specificity assays to a broader set of clinical labs.
- DiaSorin S.p.A. — a specialist player with assay-focused portfolios and channel relationships in core European markets; their product roadmap positions them to compete on both accuracy and lab workflow integration.
- Abbott Laboratories — notable for scale in instrument placements and reagent revenues, with distribution strengths in hospital and reference lab segments.
- Siemens Healthineers — leveraging integrated diagnostics platforms and lab automation capabilities to sell testing solutions as part of broader laboratory modernization programs.
- Beckman Coulter, Thermo Fisher Scientific, Quidel Corporation, Bio‑Rad Laboratories — each occupies differentiated niches from high-volume immunoassays and mass-spec consumables to point-of-care and decentralized testing options.
Strategically, incumbents differentiate on three vectors: analytical performance, integration into laboratory IT and automation ecosystems, and channel/service economics (pricing, reagent-on-contract, maintenance). New entrants that focus solely on analytical superiority without credible channel and reimbursement strategies face elongated commercialization timelines.
What the full report delivers (practical, transaction-ready content)
PW Consulting’s full market study is structured to be operational from day one. Highlights include:
- Proprietary market-sizing model (base year 2025) with a transparent forecast engine for 2026–2032, including scenario toggles for regulatory shifts, technology substitution rates, and pricing pressure.
- Competitive profiles and product mappings for the leading suppliers, with go-to-market playbooks tailored to instrument vendors, reagent-only suppliers, and diagnostics start-ups.
- Reimbursement & regulatory tracker that aggregates LCDs, CPT-level developments, and payer-specific policy updates impacting clinical access across major jurisdictions.
- Laboratory adoption curves and capital investment calculators that help hospital labs and reference networks evaluate the ROI of mass spectrometry versus automated immunoassay pathways.
- Commercial templates — segmented sales/marketing messages, pricing negotiation playbooks, and sample contracting language for reagent and service agreements.
- M&A and partnership intelligence: a proprietary list of likely targets, valuation benchmarks, and integration risk checklists for strategic acquirers and private equity investors.
- Risk heatmaps and sensitivity analyses: quantifying impact of potential policy changes (e.g., LCD revision, CPT retirements) on revenue and unit volumes across scenarios.
To preserve competitive confidentiality and to honor data-use agreements, this preview omits granular regional and application-level splits and the underlying tables; those detailed worksheets are accessible only in the full report package.
Strategic playbook for 2026
For executives making allocation decisions in 2026, PW Consulting recommends a three-part approach:
- Prioritize channel-aligned innovation. Invest selectively in test platforms whose deployment economics align with the target laboratory profile (centralized reference labs, hospital core labs, or decentralized clinic labs). Matching technical claims to purchaser pain points (turnaround time, cost per test, throughput) accelerates adoption.
- Lock in reimbursement pathways early. Create cross-functional teams (clinical affairs + reimbursement + commercial) to generate the evidence dossiers and coding strategies required to pass plan-level medical necessity reviews and to shepherd new assays through local coverage processes.
- Develop hedged commercialization scenarios. Use the PW forecast toggles to stress-test pricing and volume assumptions under alternative policy outcomes; maintain flexibility in supply chain and reagent-contract terms to respond to rapid shifts in demand.
For investors and M&A teams, the clearest opportunities will be targets that combine analytical differentiation with established lab channel access or that offer enabling software solutions (lab informatics, decision support) to lower the operational friction of adoption.
Methodology and credibility
The analysis reflects a blended-methods approach: triangulation of primary interviews with laboratory directors and procurement leads, contract-level intelligence, payer policy review, and bottom-up build of testing volumes from epidemiology and clinical practice patterns. Base-year alignment is to 2025, and the forecast horizon is 2026–2032. Concentration metrics (three‑firm and five‑firm concentration ratios) are calculated from supplier revenue estimates to indicate market structure and competitive intensity.
Next steps — why this matters for your 2026 plan
At market scale, the value pool is expanding—but the path to capture is becoming more conditional on regulatory alignment, lab capability, and channel economics than it was five years ago. PW Consulting’s full Vitamin D Testing Market report converts growth forecasts into executable strategies: bid-ready commercial materials, reimbursement dossiers, lab ROI calculators, and an opportunity map by buyer type. For teams evaluating product launches, capital investments, or acquisition targets, the report is designed to shorten the time from analysis to decision.
How to access the full study
This preview is intended to demonstrate the analytical depth and practical orientation of our work while preserving the proprietary data that underpins tactical decisions. To obtain the full dataset, detailed segment tables, and the interactive forecast model—required for transaction diligence or operational planning—please contact PW Consulting or visit our report page. Our advisory team can also arrange a tailored briefing that maps the report’s insights to your specific strategic questions.
For detailed analysis of this topic, please visit the official page: Vitamin D Testing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shooting Market to Hit USD 343.48M by 2032 at 6.8% CAGR
By pmarketresearch, 2026-07-30
Shooting Market 2026: Strategic Imperatives from PW Consulting’s Market Outlook
Overview
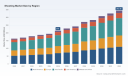
As organizations across manufacturing, retail, range operations, and training services look to 2026 as a year for decisive investment, PW Consulting’s Shooting Market study provides a data-driven compass for strategy. The sector has shown steady expansion through the first half of the decade, climbing from a clearly measurable base in 2020 to a substantially larger market in the base year of our study (2025). Our forecast through 2032 projects continued growth at a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 horizon, culminating in a materially expanded market by 2032. These macro dynamics create both opportunity and urgency: the market is large enough to warrant scale plays, yet fragmented enough to reward targeted capability investments.
Shooting Market
Why this matters for 2026 decision-making
-
Capital allocation under uncertainty: With the market trajectory established and a mid-single-digit CAGR guiding expectations, capital planners should shift from defensive preservation to selective growth — prioritizing investments that shorten time-to-revenue and de-risk regulatory exposure. Our report includes modeled capex/opex scenarios that translate market growth assumptions into portfolio-level investment needs.
Shooting Market -
Product and portfolio strategy: The market’s expansion is uneven across use cases and product categories (as detailed in the full study). Firms that refine product mixes — balancing recreational, training, and competitive offerings — can capture premium pricing and higher lifetime value. We provide go-to-market playbooks for repositioning legacy products and introducing next-generation simulators and modular range systems.
Shooting Market -
Operational resiliency and cost management: Elevated labor and specialized maintenance costs are a recurring force in range operations and services. In 2026, operators will need precision staffing models and predictive maintenance programs to protect margins. Our benchmarking templates allow executives to stress-test labor and maintenance cost assumptions against the market forecast.
-
Regulatory and trade risk mitigation: Changes to export controls, licensing, and compliance frameworks are active and enforceable. The study synthesizes the practical impacts of recent regulatory updates — including export control adjustments and federal licensing revisions — and maps compliance checkpoints to product development, distribution, and aftermarket support.
-
M&A and partnership prioritization: The sector’s competitive structure signals opportunity for bolt-ons and capability buys, particularly where incumbents lack digital training platforms or advanced target systems. Our M&A playbook ranks acquisition archetypes by value capture potential and regulatory risk exposure.
What the PW Consulting report delivers (practical, executable tools)
The objective of this study is not merely to describe market growth but to equip leaders with operational instruments they can apply immediately. The report package includes:
-
A transparent forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario toggles to evaluate alternative growth rates and demand shocks.
-
Commercial playbooks for range operators, manufacturers, and training-service providers — covering product roadmaps, pricing architectures, and channel strategies focused on accelerating adoption of simulators and low-cost training platforms.
-
Capital planning templates calibrated to the sector’s cost structure and investment cycles, including sensitivity analyses for labor and infrastructure cost inflation.
-
Regulatory compliance checklist tied to recent federal updates and export control changes, with practical steps for manufacturer and operator compliance workflows.
-
Competitive benchmarking tools and a short-list of strategic partnership archetypes, enabling faster diligence and integration planning.
-
Risk heatmaps and mitigation playbooks covering supply-chain disruption, regulatory shifts, and liability exposure for range operators.
For confidentiality and strategic clarity, the report intentionally abstracts certain granular segmental figures in public summaries; full segment-level tables and downloadable models are available in the comprehensive dataset.
Competitive landscape: structure and strategic moves
The shooting market presents a mixed structure: meaningful scale players operate alongside numerous specialized manufacturers and service providers. Market concentration metrics indicate a fragmented market where the largest three firms capture under a quarter of total revenue, and the top five only modestly more. That fragmentation validates varied strategic approaches — from scale-oriented consolidation to niche dominance through product differentiation.
-
Action Target — A range-systems integrator known for end-to-end facility delivery, Action Target remains a front-runner in commercial and tactical range infrastructure. Their platform-level innovations (for example, next-generation range control and target systems) and high-profile trade-show presence underscore their focus on productizing turnkey solutions for large-scale clients. Recent product showcases highlight their continued investment in smart range technologies that integrate moving targets and advanced safety systems.
-
Range USA, Inc. — As a supplier of range equipment and infrastructure, Range USA’s model emphasizes modular systems and retrofit capabilities. Companies seeking to upgrade existing facilities without full rebuilds will find their solutions strategically relevant; our benchmarking evaluates retrofit ROI under multiple utilization scenarios.
-
Cubic Corporation — Cubic’s strength is in training and simulation, where virtual and synthetic environments meet defense and law-enforcement buyers. Their offering illustrates the high-margin, software-enabled segment of the market. For firms exploring software–hardware bundles, Cubic’s approach provides important lessons about recurring revenue and customer lock-in.
-
Beretta USA, Kel-Tec, Air Arms, Weihrauch — These manufacturers represent diverse product strategies from premium precision airguns to compact firearms and accessories. Their presence highlights the continued relevance of product engineering, brand heritage, and distribution reach. Manufacturers with deep OEM or brand equity can leverage those assets to accelerate adoption of premium and training-oriented product lines.
-
NSSF — The industry association plays a coordinating role, publishing guidance and standards that shape compliance and best practices. For operators and manufacturers, engagement with NSSF’s resources is required to stay current with evolving safety, training, and regulatory expectations.
Recent industry developments — such as trade-show demonstrations of advanced range technologies — confirm that innovation remains a primary differentiator. At the same time, regulatory updates and infrastructure compliance requirements are re-shaping where and how investments are prioritized.
Regulatory and operational headwinds (and tactical responses)
-
Export controls and licensing: Updates to export controls and federal licensing frameworks in recent years are active considerations for 2026. Companies expanding cross-border must embed compliance into early-stage product design and contractual terms to avoid costly after-the-fact retrofits.
-
Infrastructure compliance and safety: NSSF guidance and federal revisions impose capital and operational requirements on range infrastructure. Operators will need to accelerate safety-system upgrades and document maintenance regimes; our templates calculate lifecycle costs and compliance timelines to support procurement planning.
-
Labor and operating cost inflation: Specialized staffing — from certified instructors to range technicians — drives operating expense growth. The report provides staffing models that connect utilization rates to break-even thresholds and margin sensitivity.
How executives should use this study in 2026
-
Use the forecast model as a planning anchor, then layer scenario analyses (regulatory tightening, supply-chain shock, rapid adoption of virtual training) to stress-test capital and resource allocation.
-
Prioritize initiatives that shorten payback: modular retrofits, software-enabled recurring revenue streams, and targeted channel partnerships deliver faster returns than large greenfield investments.
-
Operationalize compliance: integrate the report’s compliance checkpoints into procurement and product development cycles to reduce time-to-market and limit legal exposure.
-
Design M&A with integration playbooks: target acquisitions that fill capability gaps (simulation software, target systems, service networks) rather than purely revenue accretion; our diligence templates and integration checklists are ready for immediate use.
Next steps and access
PW Consulting’s Shooting Market study is designed as an operative briefing for executives making allocation decisions in 2026. It combines a rigorously documented macro forecast (historical 2020–2025; base year 2025; forecast 2026–2032 with a 6.8% CAGR), practical toolkits, and competitive diagnostics that translate insight into action. To preserve strategic value in a contested market, this public summary intentionally omits detailed segment tables and company-level scorecards; these are available in the full report package, which includes downloadable models, segment-level demand drivers, and supplier scorecards.
For organizations evaluating capital projects, market-entry strategies, or M&A targets this year, the full dataset and executable playbooks will materially reduce timeline and execution risk. Contact PW Consulting through our report access page to retrieve the full intelligence suite and a customized briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Shooting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CCA Market to Reach USD 714.24 Million by 2032 at 3.8% CAGR
By pmarketresearch, 2026-07-30
Chromated Copper Arsenate (CCA) Market: Strategic Preview for 2026 Decision-Makers
As companies prepare their 2026 capital plans and supply‑chain strategies, a clear-eyed, pragmatic view of the Chromated Copper Arsenate (CCA) market is essential. PW Consulting’s forthcoming market study — base year 2025, with historical coverage 2020–2025 and forecasts through 2032 — synthesizes commercial dynamics, regulatory trajectory, and competitive positioning into an actionable strategic brief. This introduction outlines the report’s strategic value for 2026 decisions, highlights the most consequential market signals, and previews the hands‑on tools contained in the full study. Consider this a trailer: we show the analytical architecture and strategic implications while intentionally reserving granular segment-level data for the full report.
Chromated Copper Arsenate Market
Why CCA matters in 2026: a macro snapshot
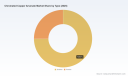
CCA continues to play a defined, primarily non‑residential role in pressure‑treated wood applications. From 2020 to 2025 the global market expanded from roughly USD 462 million to USD 557 million (USD Million, base year 2025), underscoring steady recovery and demand consolidation in industrial and infrastructure uses. Our forecast extends through 2032 with a compound annual growth rate (CAGR) of 3.8%, projecting continued expansion driven by renewals in utility, marine and industrial structures, and selective growth in regions prioritizing durable timber solutions.
Chromated Copper Arsenate Market
This growth profile positions CCA as a predictable, mid‑cycle market: large enough to attract strategic investment but sufficiently fragmented to reward targeted consolidation and capability plays. Market concentration metrics reflect that leading suppliers hold a meaningful, but not dominant, share — an environment that simultaneously rewards scale economies and nimble, differentiated service models.
Chromated Copper Arsenate Market
Regulatory and cost dynamics that will shape 2026 choices
-
Regulatory review is the central risk vector. As of December 2025, chromated arsenicals including CCA are undergoing registration review by the U.S. Environmental Protection Agency. Interim mitigation measures focused on worker protection are already in place; these underscore the potential for tighter operating requirements and compliance costs going forward.
-
Use restrictions remain material. Regulatory policy continues to confine CCA to commercial, industrial and non‑residential applications — a structural constraint on demand composition that should inform any product‑mix or channel strategy.
-
Worker health concerns are concentrated inside treatment facilities. The EPA’s recent findings center on occupational cancer and non‑cancer risks for workers, not on general public exposures. For operators, this means investments in engineering controls, PPE, and medical surveillance may become mandatory costs of doing business.
-
Alternative preservatives exert pricing pressure. Industry data indicate alternatives can raise treatment costs by 10–30% relative to CCA — a double‑edged sword that both elevates CCA’s near‑term competitiveness in price‑sensitive industrial applications and increases the total cost employers face if forced to substitute.
-
End‑of‑life and disposal are an emerging liability vector. Non‑household disposal of CCA‑treated wood may require hazardous‑waste determinations under RCRA, with state‑specific guidance creating operational complexity across jurisdictions.
Strategic implications for 2026 planning
-
CapEx and plant footprint decisions must be stress‑tested for regulatory tightening. Line expansions, new treatment sites, or retrofit investments should be evaluated across multiple regulatory scenarios (status quo, incremental mitigation, and stringent controls). Our scenario toolbox quantifies NPV sensitivities to operating constraints and compliance capex.
-
Labor and automation investment become competitive levers. Given the worker‑risk narrative, companies that proactively invest in automation, closed‑loop systems, and advanced exposure controls can lower long‑term labor risk while capturing efficiency gains and differentiation in bidding for utility and industrial contracts.
-
Price architecture and cost pass‑through models must reflect alternative‑preservative pressure. With substitutes imposing 10–30% higher treatment costs, suppliers and customers will renegotiate procurement practices. Our elasticities model and tiered pricing playbook help determine optimal pass‑through rates by customer segment and contract tenor.
-
Disposal services and circular strategies convert regulation into revenue streams. Forward‑thinking firms can monetize compliant disposal, recycling, and certification services — converting a pain point into a differentiation strategy that reduces customer liability and builds stickiness.
-
M&A windows are asymmetric. The market’s moderate concentration and regulatory complexity create acquisition opportunities for larger players seeking scale and smaller operators seeking exits. Our target screening ranks candidates by compliance posture, asset quality, and integration risk.
What the PW Consulting report delivers — operational and strategic toolset
The full study is designed as a practical playbook for executives who must make 2026 decisions under uncertainty. Key deliverables include:
-
Demand forecasting models (interactive): granular demand by region, application and product form across multiple scenarios from 2026–2032, with sensitivity levers for regulatory outcomes and substitution rates.
-
Regulatory impact assessment and compliance roadmap: stepwise mitigation requirements tied to likely EPA outcomes, cost estimates for engineering controls, and a jurisdictional matrix for disposal obligations.
-
Cost and price modeling toolkit: bottom‑up cost curves, break‑even analyses under substitution scenarios, and contract negotiation templates for price escalation clauses tied to preservative inputs and compliance costs.
-
Supply‑chain and raw‑material risk mapping: supplier concentration heatmaps, critical input analyses, and sourcing contingency plans for procurement teams.
-
Commercial playbooks: go‑to‑market frameworks for utility, marine, and industrial segments, plus channel strategies that reflect non‑residential use constraints.
-
Competitive benchmarking and M&A screening: profiles of incumbent players, capability gaps, valuation multiples observed in adjacent consolidation events, and an acquisition integration checklist.
-
Operational checklists and audit templates: worker protection protocols, environmental compliance checklists, disposal routing standard operating procedures, and a regulatory monitoring dashboard.
Competitive landscape: what incumbents are likely to do in 2026
The CCA supplier community exhibits a mix of legacy incumbents with integrated capabilities and regional specialists focused on treatment services. Our competitive review emphasizes three archetypal players who exemplify strategic responses to 2026 pressures:
-
Koppers Performance Chemicals Inc. — With a strong manufacturing heritage in treated lumber and broad commercial and industrial coverage, Koppers is positioned to exploit scale advantages in compliance investment and contract delivery. Expect Koppers to prioritize modernization of treatment lines, deeper integration of downstream services (e.g., certified disposal), and selective partnerships to de‑risk regulatory exposure.
-
Goodfellow Inc. — As a regional specialist with treatment facilities concentrated in Eastern Canada, Goodfellow’s value lies in local regulatory familiarity and customer intimacy. Its likely plays in 2026 include premiumization of service (certificate‑based compliance offerings), targeted capacity optimization, and cross‑border logistics to serve adjacent industrial markets seeking compliant, non‑residential treated wood.
-
Chemical Specialties, Inc. (CSI) — A North America‑focused supplier with commercial and agricultural footprints, CSI is the archetype for nimble operators who can reposition quickly. CSI’s options include niche differentiation through custom formulations for industrial users, investment in closed‑loop exposure controls, and opportunistic M&A as smaller local players face compliance cost pressure.
Collectively, these firms illustrate likely market behaviors: investment in compliance and automation; expansion of ancillary services (disposal, certification, logistics); and opportunistic consolidation. None are insulated from regulatory tightening, but those with disciplined balance sheets and operational modernization programs will emerge as preferred suppliers to institutions and utilities.
Recommended actions for executives in 2026
-
Run regulatory‑first scenario planning before finalizing CapEx: model at least three EPA outcome scenarios and stress‑test existing contracts against each.
-
Prioritize worker‑safety investments that also improve productivity: closed‑loop systems and automation reduce long‑run compliance exposure while lowering variable labor costs.
-
Develop a price‑escalation framework tied to preservative substitution indices: this preserves margins if customers require alternative chemistries.
-
Build a disposal and certification offering: converting an end‑of‑life requirement into a recurring revenue service improves customer retention and reduces legal exposure.
-
Prepare an M&A playbook aligned to compliance posture: target acquisitions that consolidate regional footprint or add compliant capabilities at below‑market multiples.
Concluding perspective
For 2026, the CCA market presents a classic strategy paradox: stable, incremental growth and clear industrial demand on one hand; regulatory uncertainty and downstream liability on the other. The companies best positioned to win will be those that treat regulatory requirements as a competitive moat rather than a cost burden — investing in automation, compliance services and disposal solutions to lock in industrial customers. PW Consulting’s full report provides the quantitative backbone (interactive forecasts, sensitivity models, and valuation matrices) and the operational checklists necessary to translate these strategic choices into executable plans.
To access the complete dataset, regional and application breakdowns, and the full set of implementation toolkits that underpin the analysis summarized here, please refer to PW Consulting’s Chromated Copper Arsenate Market report page. The full study contains the detailed segment tables and interactive models required to finalize 2026 budgets and strategic initiatives.
For detailed analysis of this topic, please visit the official page: Chromated Copper Arsenate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Reusable Gloves Market Poised for 6.5% CAGR Through 2032
By pmarketresearch, 2026-07-30
Reusable Gloves Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, judgment-driven preview of our full Reusable Gloves Market study — timed for executives making allocation, sourcing, and R&D decisions in 2026. This preview synthesizes the market trajectory, regulatory inflection points, supplier dynamics, and the practical tools included in the full report. It is intentionally directional: we reveal the macro context and strategic implications while preserving the granular segmentation and proprietary scenarios for subscribers who access the full dossier.
Reusable Gloves Market
Market Trajectory: Where demand is headed
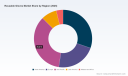
The reusable gloves market has moved from niche cost-savings initiatives to a structural element of occupational safety and clinical supply strategies. On a macro level, the market expanded steadily through 2020–2025, reaching roughly USD 292 million in 2025. Our baseline forecast, incorporating supply-chain normalization, material-cost trends, and policy shifts, projects a compound annual growth rate (CAGR) of about 6.5% for 2026–2032 — bringing the market to an estimated USD 454 million by 2032 under the central case.
Reusable Gloves Market
That pace reflects a balance of forces: accelerating institutional adoption driven by lifecycle economics and sustainability targets, partially offset by continued competition from disposables for certain low-cost, single-use applications. The pattern of growth is not uniform; pockets of accelerated adoption exist where reuse protocols deliver measurable operating savings and compliance advantages. The full report models these pockets with scenario sensitivity and supplier-level impact assessments.
Reusable Gloves Market
Why 2026 is a strategic inflection year
-
Regulatory tightening: The FDA’s Quality Management System Regulation (QMSR) requiring ISO 13485:2016 compliance for medical glove manufacturing became effective in early 2026. For manufacturers and medical-supply procurement teams this raises compliance entry costs and shifts supplier economics — favoring players with established quality systems and capitalized manufacturing footprints.
-
Cost-benefit clarity: Institutional buyers report meaningful savings when migrating to reusable programs. Published field analyses indicate that well-designed reusable programs can cut hand-protection costs materially versus disposables — an especially compelling proposition for high-volume facilities trying to manage operating budgets.
-
Certification and infection control: For clinical use, reusable gloves must meet ASTM and EN standards for chemical permeation and dexterity. Compliance is now non-negotiable for infection control committees, and suppliers who can demonstrate certified performance gain access to hospital formularies at scale.
-
Operational realities: Reuse introduces upstream and downstream costs — notably laundering, inspection, and re-sterilization protocols that can add approximately 10–15% to operational labor costs for hospital programs. When these labor and logistics costs are modeled alongside per-use material savings, the economic case requires rigorous, site-level analysis.
Strategic implications for stakeholders
For executives, 2026 decisions should be framed not as binary “reuse versus disposable” choices but as system-level optimizations. Our research highlights five pragmatic moves:
-
Adopt a lifecycle procurement lens. Move beyond per-unit pricing to measures like cost per use, waste handling, and compliance risk. Organizations that integrate this into supplier RFQs gain a sustainable cost advantage.
-
Prioritize certified suppliers with scalable quality systems. The capital and procedural requirements implied by ISO 13485 compliance mean fewer low-cost entrants will be able to service clinical segments. This creates premium for established suppliers that can demonstrate repeatable, auditable quality.
-
Invest in centralized laundering and inspection protocols where volumes justify it. Centralization reduces per-use costs and improves traceability but requires upfront systems and governance investment. Our financial model shows payback timelines at the facility and network levels.
-
Leverage supplier partnerships for co-innovation. Material science advances (e.g., enhanced nitrile formulations, antimicrobial linings) and ergonomic design improvements are differentiators. Strategic suppliers are open to joint testing and shared risk pilots.
-
Validate sustainability and occupational safety metrics. Reusable programs reduce waste streams but shift environmental and operational footprints. Decision frameworks should include lifecycle carbon and labor implications to satisfy ESG and risk committees.
Competitive landscape — who matters and why
The market remains moderately fragmented: the three largest players account for a modest share of global revenue, and the five largest capture roughly one-third of the market, leaving substantial room for regional specialists and niche innovators. The competitive map is shaped by a few structural variables: product durability and performance, regulatory compliance and certification, manufacturing footprint, channel reach, and services such as laundering and end-to-end program support.
-
Ansell Ltd (Melbourne, Australia) — A recognized manufacturer across nitrile and latex reusable gloves, with product lines tailored to healthcare, laboratory, and industrial applications. Ansell’s advantage is a broad certified portfolio and established relationships in clinical procurement.
-
Honeywell International Inc. (Charlotte, NC, USA) — Focused on industrial and specialty segments, Honeywell leverages scale and distribution to serve cut-resistant and high-durability needs, emphasizing workplace safety programs and integrated PPE solutions.
-
Showa Group (Japan) — Known for chemical resistance and antimicrobial treatments across reusable nitrile and latex ranges. Showa’s R&D focus on material performance makes it a preferred supplier in environments with elevated chemical exposure risk profiles.
-
MAPA Professional GmbH (Germany) — Positions itself on durability and tactile performance for medical and laboratory markets, with localized manufacturing strengths in Europe that benefit buyers seeking shorter lead times and regulatory alignment.
-
Sempermed USA Inc. (Austria / US operations) — An established player servicing healthcare and industrial channels; its cross-border manufacturing footprint and medical-grade product lines align with buyers requiring certified, consistent supply.
-
Reflexx (Italy) — Specialist in multiple material technologies including nitrile, latex, and neoprene. Reflexx competes on product breadth and customizability for professional and medical applications.
Recent industry activity underscores the dynamic nature of the market. In 2025 several manufacturers launched new lines — for example, chemotherapy-rated nitrile gloves and low-protein latex examination gloves — reflecting both clinical demand and material innovation. These launches signal continued product-level differentiation rather than commoditization.
Where winners will emerge
Winning suppliers and buyers will be those who integrate three capabilities: certified product performance, supply reliability under evolving regulatory regimes, and services that lower the total cost of ownership (TCO) for end-users. The mid-term competitive advantage will accrue to organizations that can bundle high-performance materials with program services (e.g., laundering, traceability, warranty) and whose financial models make adoption economics transparent for clients.
What the full PW Consulting report delivers
The full study is designed as a decision-support toolkit for 2026 planning cycles. Key deliverables include:
-
A detailed market model (2020–2032) with central, upside, and downside scenarios, enabling sensitivity testing against material-cost shocks, regulatory adoption timelines, and labor-cost variations.
-
Supplier benchmarking scorecards that evaluate quality certifications, production capacity, lead times, channel reach, and service offerings.
-
Lifecycle cost calculators that quantify per-use economics, factoring in laundering, inspection labor, replacement rates, waste handling, and compliance expenditures.
-
Regulatory playbook and compliance checklist aligned to FDA QMSR/ISO 13485 and key ASTM/EN standards — designed for procurement and compliance teams drafting RFPs and supplier audits.
-
Commercial playbooks for OEMs and private-label entrants that map go-to-market choices, margin structures, and partnership models with service providers.
-
Case studies and pilot designs illustrating measurable pathways to up to 30% savings in hand-protection costs where programs are optimized — with sensitivity ranges and realistic operational assumptions.
How to use this preview in your 2026 planning
Use this analysis to set three immediate priorities for 2026: (1) audit supplier compliance and certification status against ISO 13485 and relevant ASTM/EN standards; (2) run a targeted lifecycle-cost pilot in high-volume sites to validate per-use equations while capturing laundering and labor overheads; and (3) reassess supplier contracts to include service-level agreements tied to traceability, durability, and program-support commitments.
These steps convert the macro growth trajectory and regulatory shifts into operational action — narrowing uncertainty while preserving optionality for different adoption speeds across regions and applications.
Conclusion — the tactical payoff
With the market expanding at a steady mid-single-digit CAGR and regulatory forces raising the bar for clinical-grade supply, 2026 is a year to convert strategy into operational protocols. The reusable gloves category is moving from cost-avoidance experiments to scaled program adoption where certified performance, supply reliability, and service-enabled economics determine who captures value.
For readers seeking the granular segmentation, supplier scorecards, and the full suite of modeling tools that underpin this preview, the complete PW Consulting Reusable Gloves Market report provides the necessary detail to implement and defend 2026 capital and procurement choices. Accessing the full report will unlock the proprietary scenarios, regional breakouts, and supplier-level financials we deliberately withheld from this preview to preserve its function as a strategic “trailer.”
For detailed analysis of this topic, please visit the official page: Reusable Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bolt Market to Reach $115.3M by 2032 at 3.48% CAGR — PW Consulting Insight
By pmarketresearch, 2026-07-30
Bolt (Fastener) Market: A 2026 Strategic Primer for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present an executive introduction to our latest Bolt (Fastener) Market study — designed explicitly to equip corporate leaders with the actionable perspective they need in 2026. The global market, measured on a USD Million basis, has expanded from roughly USD 71.0 Million in 2020 to a 2025 base of about USD 91.04 Million, and our forward view projects continued expansion to the low‑hundreds by the end of the 2026–2032 forecast window (reaching roughly USD 115.3 Million by 2032). That represents a steady compound annual growth rate of approximately 3.48% across the forecast period. These headline numbers frame the opportunity set; the strategic aim of this primer is to translate them into practical choices for procurement, manufacturing, portfolio, and M&A leaders.
Bolt (Fastener) Market
Why this research matters for 2026 decisions
- Timing capital investments: Moderate but persistent growth and the uneven year‑to‑year cadence we observe in the 2026–2032 forecast imply that plant expansion and automation investments should be staged and tied to demand triggers rather than broad, front‑loaded capacity builds.
- Supply‑chain risk management: Raw material volatility and labor constraints are recurrent pressures — procurement teams must adopt hedging, multi‑sourcing, and inventory optimization strategies to avoid margin erosion.
- Commercial segmentation and pricing: End‑market cyclicality (notably automotive, construction, and industrial machinery) requires differentiated go‑to‑market and pricing playbooks rather than a one‑size‑fits‑all approach.
- M&A and partnership prioritization: Mid‑market consolidation dynamics create windows for bolt‑and‑nut players to scale through targeted acquisitions or logistics/technology partnerships — but value realization depends on playbook execution.
- ESG and standards compliance: Emerging standards activity and sustainability expectations are reshaping supplier qualification and product claims, with implications for certification costs and market access.
Key market dynamics shaping 2026 strategy
- Raw materials and price pressure: Steel remains the dominant cost driver. As of early June 2026, benchmark steel pricing stood at approximately 3,152 CNY per tonne — up around 6.9% year‑on‑year — transmitting cost pressure across the value chain and compressing margins for players unable to pass through increases.
- Standards and technical governance: Industry institutions have intensified standards stewardship. Notably, the Industrial Fasteners Institute ran its inaugural Standards Camp in mid‑2026 and continues to steer technical committee work — an operational reality for product engineers and compliance teams.
- Workforce and capacity constraints: The fastener sector remains labor‑intensive; global employment metrics indicate a workforce base in the millions with ongoing localized shortages that complicate ramp schedules and increase unit labor costs.
- Trade shows and knowledge flows: 2026 saw key convenings — Fastener Fair USA in May and the International Fastener Expo in October — which catalyzed a wave of product and logistics innovations visible across suppliers and OEM procurement teams.
- Macro oversupply/industry cycles: Broader metal industry signals — including international dialogues on steel excess capacity — inject episodic price and trade‑policy risk into fastener sourcing strategies.
Competitive landscape — who matters and why
The market structure is neither fully fragmented nor dominated by a tiny oligopoly. Top players exert meaningful influence through distribution networks, specialty product portfolios, and value‑added services, but there remains room for nimble competitors to capture niche or regional positions.
Bolt (Fastener) Market
- Würth Group (Künzelsau, Germany): A distribution and branch network powerhouse, Würth’s global footprint and extensive product range create a strong platform for integrated logistics and small‑lot servicing to construction and industrial buyers.
- LISI Group (Grandvillars, France): A specialist in high‑spec fasteners for aerospace, automotive, and medical applications — their engineering depth and certification credentials position them for higher‑margin segments.
- Bossard Group (Zug, Switzerland): Notable for fastening technology and logistics systems; Bossard’s focus on assembly efficiency and inventory services makes it a preferred partner for lean manufacturers.
- SFS Group (Heerbrugg, Switzerland): Precision fastening and assemblies for industrial customers; strengths include close engineering collaboration and custom component supply.
- Bulten AB (Gothenburg, Sweden): An automotive‑focused fastener supplier with deep OE and tier‑1 relationships, tuned to the vehicle manufacturers’ quality and scale requirements.
- Hilti Corporation (Schaan, Liechtenstein): Although broader than just fasteners, Hilti’s construction‑grade fasteners and tools combine product differentiation with strong brand recognition in building markets.
- Precision Castparts Corp (Lake Oswego, USA): Supplier of investment castings and high‑strength forged components — positioned for high‑value aerospace and power‑generation fastener requirements.
Strategically, these companies represent four archetypes: distribution and branch scale, engineered‑component specialists, logistics/assembly service innovators, and multi‑segment OEM partners. The competitive implications for 2026 are straightforward: scale matters for price and reach, engineering depth wins certified and high‑margin work, and logistics/automation capability is becoming a defensible competitive moat.
Bolt (Fastener) Market
What the PW Consulting report delivers (practical contents)
Our full report goes well beyond headline growth figures to deliver deployable intelligence across decision horizons. Key elements include:
- Methodology and transparent assumptions underpinning our historical reconstruction (2020–2025) and the 2026–2032 forecast.
- Market sizing and scenario tables (interactive dashboards) that let executives model demand on alternative macro and end‑market trajectories.
- Supply‑chain mapping and cost build‑ups — from raw‑steel price sensitivity to labor and logistics components — to support margin and sourcing stress tests.
- Regulatory and standards matrix with compliance impact scoring tailored by product families and end uses.
- Comprehensive company profiles, capability maps, and partnership/opportunity heatmaps for M&A and supplier selection.
- Commercial playbooks for procurement, pricing, aftermarket, and product standardization to improve working capital and reduce SKU complexity.
- Risk registers and a prioritized mitigation roadmap (covering raw materials, labor, trade policy, and climate‑related supply disruptions).
Note: this introduction intentionally emphasizes the strategic contours. Detailed tables that break down type, application, and regional splits (and the company‑level KPIs that drive M&A screens) are available in the full report and via the source page.
Actionable strategic recommendations for 2026
- Hedge steel exposure and adopt trigger‑based procurement: Combine multi‑tier supplier contracts with indexed pricing clauses and a calibrated buffer inventory to smooth volatility without tying excessive capital.
- Prioritize automation in assembly and logistics: Target investments that reduce dependence on scarce labor and shorten lead times — robotics in sorting and automated replenishment systems offer the fastest payback in many plants.
- Shift to modular standardization: Rationalize SKUs and push commonality across platforms to reduce inventory carrying costs and simplify supplier management.
- Develop service and aftermarket revenue streams: For distribution players, create bundled installation, inspection, and certified repair services to extend customer lifetime value.
- Selective M&A and strategic partnerships: Acquire engineering‑led niche manufacturers to access certified product lines, or partner with logistics tech providers to accelerate distribution efficiency.
- Invest in standards and certification capability: Be proactive in standards committees (technical participation) to shape specifications and reduce compliance surprises.
- Address workforce gaps with training and automation: Combine targeted recruitment with reskilling programs linked to automation projects to maintain throughput and quality.
How senior teams should use this report in 2026
- Board level: Use the forecast scenarios to stress‑test capital allocation and M&A authorization thresholds.
- CFO/Procurement: Incorporate price‑sensitivity models and supply‑chain risk heatmaps into budgeting and supplier scorecards.
- COO/Manufacturing: Apply the operational playbooks and benchmarking to prioritize automation, floor‑plan changes, and SKU rationalization pilots.
- Corporate development: Filter acquisition targets through our capability maps and integration templates to accelerate due diligence.
Closing: where to find the full intelligence
This primer is intentionally selective — a “trailer” that demonstrates the analytical depth and practical orientation of PW Consulting’s Bolt (Fastener) Market study while preserving the granular subsegment and company metrics that give competitors their commercial edge. For access to the full dataset, interactive dashboards, and the detailed segmentation tables (by type, application, and region), please consult the full report and our data portal. PW Consulting’s team stands ready to tailor the findings into a decision package that fits your 2026 strategic planning cycle.
For detailed analysis of this topic, please visit the official page: Bolt (Fastener) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Locker Locks Market Poised for 5.0% CAGR from 2026–2032
By pmarketresearch, 2026-07-30
Locker Locks Market: Strategic Insights for 2026 Decision-Making
Executive snapshot
As organizations recalibrate physical-security investments in a post-pandemic, data-conscious world, the global locker locks market stands at a meaningful inflection. Our analysis uses 2025 as the base year, traces developments since 2020, and projects through 2032. The market—which expanded from a clear five-year historical base—registered measured growth to approximately USD 125 million in 2025 and is expected to continue on a steady trajectory (approximate CAGR 5.0% over the forecast window). Concentration remains material: the top three vendors account for roughly 70% of revenue, and the top five capture about 85%, underscoring a market where scale, channel reach and product breadth matter for sustained leadership.
Locker Locks Market
Why this research matters for 2026 decision cycles
- Timing: 2026 is the first full planning year following several product refreshes from major OEMs and a fresh wave of regulatory clarifications affecting electronic access systems. Tactical choices made this year—on product roadmaps, OEM partnerships, and procurement standards—will govern multi-year market share outcomes.
- Risk management: New privacy and safety requirements (notably GDPR-driven audit-trail expectations, CE marking regimes in the EU, and U.S. workplace safety rules relating to lockout/tagout) mean that product compliance, data architecture and after-sales processes are now strategic risk vectors rather than checkbox items.
- Return optimization: With a steady mid-single-digit CAGR anticipated, volume alone will not deliver outsize returns. Winning players will differentiate through adjacent services, platform integrations and channel economics.
Market trajectory and structural signals
The market’s historical performance from 2020 through 2025 shows a stable expansion path, and our forecast through 2032 projects continued single-digit growth moderated by periodic product refreshes and adoption cycles of smarter, networked solutions. That pattern reflects two interacting dynamics: first, mature replacement and retrofit cycles in institutional and corporate environments; second, incremental new demand driven by digital access requirements, hospitality and multi-family housing conversions.
Locker Locks Market
Important structural characteristics include:
- Relatively high market concentration—indicating scale advantages in manufacturing, distribution and brand-driven procurement.
- Product diversification across mechanical, electronic and hybrid systems—where different value propositions (cost, convenience, compliance) map to different buyer segments and procurement levers.
- Emerging cost complexities for networked systems—install-time cabling (PoE) versus battery-powered wireless solutions meaningfully changes total installed cost and upgrade pathways.
Drivers, constraints and regulatory overhangs
Demand drivers are a combination of secular and tactical factors: workplace reopenings and reconfigurations, multi-family property upgrades, locker-as-a-service deployments in shared-economy venues, and institutional investments in asset security. On the technology front, the adoption of Bluetooth, NFC and cloud-managed locker management platforms is accelerating, but buyers remain sensitive to life-cycle cost, interoperability and data-security assurances.
Two regulatory/standards developments deserve special attention for 2026 planning:
- Data privacy and audit trails: Enforcement and buyer expectations stemming from GDPR-like regimes are raising the bar for encrypted logs and proof-of-access. For vendors, this transforms software modules and firmware architecture from differentiation points into table stakes.
- Safety and access control standards: OSHA-style lockout/tagout requirements and CE conformity frameworks are tightening acceptance windows for new products in certain geographies. Compliance timelines and third-party testing windows must be integrated into product launch plans.
Competitive landscape — what to watch
The competitive map is balanced between long-established mechanical specialists and more recent electronic/smart entrants. Notable companies shaping market dynamics include:
- Master Lock Company (United States) — a legacy brand with broad commercial and consumer offerings, increasingly active in smart commercial locks and partnerships targeting multi-family and SMB segments.
- Abloy Oy (Finland) — recognized for high-security mechanical and hybrid electronic locking solutions, often positioned in high-assurance institutional installations.
- Codelocks (United Kingdom) — a fast-moving innovator in compact digital and kit-lock systems; recent launches broaden their addressable installations and suggest an aggressive mid-market push.
- Lowe & Fletcher, Digilock, EMKA, Hettich and Häfele — firms with strong OEM or distribution capabilities, supplying integrated furniture, cabinet and locker-specific hardware solutions.
- Allegion, Ojmar, LockeyUSA, Zephyr Lock — established access-control players increasingly layering smart features or distribution partnerships to defend installed bases.
- China-based suppliers (e.g., Be-Tech, MAKE, Ningbo Wangtong) — competitive on cost and feature-rich electronic options; critical as contract manufacturing and OEM-sourced components become more prominent in procurement decisions.
Recent product activity—multiple launches from both traditional names and newer entrants—indicates the market is in a phase of feature consolidation (miniaturization, dual-function locks, stronger enclosures) and platform evolution (integration with building management and locker-management SaaS). This intensifies competition on product roadmap, channel partner coverage and software ecosystems rather than on purely hardware price.
Strategic implications and recommended actions for 2026
For incumbent suppliers, challengers and buyers, the following decision levers will materially influence outcomes in 2026 and beyond:
- Portfolio strategy: Prioritize modular architectures that allow mechanical lockbacks and electronic upgrades without full cabinet replacement. This minimizes customer friction in upgrade cycles and protects installed-base value.
- Compliance-first product development: Embed encryption, audit trails and third-party certification plans into R&D roadmaps. Non-compliant launches risk procurement delays and contract penalties in regulated environments.
- Channel and service economics: Reconfigure go-to-market to favor value-added installers and systems integrators that can deliver turn-key locker systems—bundling hardware, cabling decisions (PoE vs. battery) and software subscription offerings.
- M&A and partnerships: Use M&A to close capability gaps—software platforms, secure cloud services, or regional distribution. For larger incumbents seeking growth, bolt-on acquisitions of niche smart-lock vendors or SaaS locker-management firms can accelerate access to recurring revenue models.
- Supply-chain resilience: Hedge component concentration, especially for electronics and battery modules. Consider dual-sourcing for critical subassemblies and negotiating long-lead commitments tied to compliance documentation.
- Pricing and TCO selling: Shift purchasing conversations to total-cost-of-ownership narratives that account for installation labor, cabling, firmware updates and data-compliance costs—this preserves margins on higher-value, integrated offerings.
What our full report delivers — practical, execution-ready content
This research is deliberately structured to be operational for 2026 planners. Highlights include:
- Quantitative market sizing and a transparent forecast model (2026–2032) built on validated install-base and replacement-rate assumptions.
- Scenario analyses mapping regulatory and technology adoption variants to revenue and margin outcomes—enabling contingency planning.
- Channel economics and buyer persona matrices that convert macro trends into procurement playbooks for sales, product management and M&A teams.
- Vendor scorecards and comparative capability maps that evaluate product breadth, compliance readiness and software ecosystems—designed to support short-listing and supplier negotiations.
- Implementation toolkits: sample RFP clauses for encrypted audit-trails and safety compliance, installation cost worksheets contrasting PoE vs. battery-powered architectures, and a checklist for field retrofits to minimize downtime.
Data integrity, methodology and what we intentionally withhold
Our base year is 2025; the historical window spans 2020–2025 and the forecast horizon is 2026–2032. We triangulated primary interviews, OEM public disclosures, installer surveys and transactional pricing data to arrive at the market model. To preserve the report’s commercial value and adhere to a “teaser” approach, this introduction omits the granular regional and application splits and specific segment revenue figures that are included only in the full report. The detailed segmentation, supplier share matrices (down to five-player concentration by subsegment), and the underlying model spreadsheets are accessible via the source download.
Quick read on near-term signals to act on in 2026
- Prioritize product launches that combine strong physical robustness with encrypted software logs—these will cross the compliance bar faster and shorten sales cycles.
- If you are a buyer, insist on testable audit trails and a documented CE/GDPR/OSHA compliance matrix during RFP evaluation to avoid post-deployment surprises.
- If you are a vendor, accelerate partnerships with locker-management SaaS providers or certify your APIs to be integrable with leading building-management platforms—this unlocks higher-margin recurring revenue.
- Evaluate aftermarket service and retrofit offers as a defensive play to monetize the large installed base while slowing customer churn.
Closing—how PW Consulting can accelerate your 2026 roadmap
Our Locker Locks Market study is designed to translate market metrics into executable choices. Whether your priority is defending share, entering new geographies, or building a software-enabled recurring business, the report supplies the data, competitive context and procurement instruments to reduce execution risk. For procurement teams, product executives, M&A sponsors and channel strategists, 2026 is a planning inflection: the decisions made now will determine who captures disproportionately more of the modest-but-stable growth that the market offers.
To access the full dataset, segmentation breakdowns, vendor scorecards and the forecast model, consult the PW Consulting report landing page (full access available for licensed clients). Our team is available for tailored briefings and to run custom scenario models aligned with your product and go-to-market priorities.
For detailed analysis of this topic, please visit the official page: Locker Locks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Voltage Cables Market to Grow to USD 63.81M by 2032 (6.08% CAGR)
By pmarketresearch, 2026-07-30
High Voltage Cables Market — Strategic Preview for 2026 Decision-Makers
As energy systems accelerate toward higher-capacity transmission, deeper subsea links and widespread renewable integration, decisions made in 2026 will set the competitive trajectory for the next decade. PW Consulting’s High Voltage Cables Market study (base year 2025; forecast period 2026–2032) synthesizes historical performance, a rigorous forecast framework and project-level intelligence to translate market signals into executable strategies. The market has expanded materially from the early 2020s — rising from roughly USD 25–26 million in 2020 to an estimated USD 42.4 million in 2025 — and is projected to continue growing through 2032, reaching about USD 63.8 million under our central case. The 2026–2032 compound annual growth rate (CAGR) underpins that trajectory at approximately 6.08%.
High Voltage Cables Market
Why this study matters in 2026
-
Timing: 2026 is a hinge year for capex cycles and project awards across offshore wind, long‑distance DC transmission and national grid reinforcements. Several high‑value projects that will consume high‑voltage (HV) cable capacity are moving from feasibility to firm procurement, making supplier selection, manufacturing commitments and installation scheduling urgent.
High Voltage Cables Market -
Input‑cost volatility: raw materials and installation inputs remain a critical margin driver. For example, copper wire pricing and availability materially affect tender pricing and sourcing strategies; industry indices showed copper electric wire costs near USD 416 per thousand linear feet in April 2026, creating immediate implications for bids, hedging and contract structure.
High Voltage Cables Market -
Regulatory and system‑operator momentum: major system owners continue to propose and sanction sizeable HVDC programmes — exemplified by a multi‑billion capital plan submitted for an HVDC upgrade between major islands — and cross‑TSO coordination initiatives are forming new infrastructure corridors, especially in the North Sea and other offshore zones. These are structural demand drivers, not one‑off phenomena.
-
Technology and execution complexity: recent project milestones, including world‑record subsea installation depths and multiple high‑voltage contract awards, demonstrate rapidly evolving technical capability among suppliers and raise the bar for delivery risk management and installation logistics.
What this report delivers (practical, operational intelligence)
-
Market sizing and granular forecasting: transparent methodology and scenario outputs that translate macro drivers into a validated, project‑level demand runway for 2026–2032 (base year 2025).
-
Supply‑side capability maps: manufacturing capacity, installation fleet availability, lead times, and an assessment of technological readiness across AC and DC product families.
-
Procurement and cost modelling toolkit: indexed cost build‑ups that incorporate raw material trends, manufacturing yield assumptions, transport and installation risk premia — designed to be drop‑tested against live tenders.
-
Project pipeline and tender tracker: a curated dataset of near‑term to mid‑term projects, procurement windows and counterparty profiles to prioritize commercial effort and resource allocation.
-
Commercial playbooks: tailored go‑to‑market strategies for suppliers, utilities and investors — from pricing templates and risk allocation clauses to JV frameworks for offshore installation.
-
Risk matrices and scenario stress tests: quantified implications of material price shocks, permit delays, and installation failures on cash flows and delivery schedules.
Competitive landscape — who matters and what they signal
The market exhibits moderate concentration at the top: the top three groups account for a substantial share of global volume and capability, while the top five capture just over half the market by revenue and capability metrics. This concentration creates a dual dynamic — a small set of suppliers able to execute very large, complex projects, and a long tail of regional manufacturers and integrators competing on lead time, local content and aftermarket services.
-
Nexans (Paris, France) — Demonstrated capability in deep subsea HVDC with recent installation milestones at world‑record depths. Their execution competence for complex subsea links makes them an obvious counterparty for projects requiring novel installation techniques and risk‑sharing structures.
-
Prysmian Group (Milan, Italy) — Continued focus on high‑voltage HVAC solutions for floating offshore wind and integrated offshore platforms. Prysmian’s portfolio suggests strategic emphasis on adaptable HVAC systems that reduce offshore interface complexity.
-
NKT A/S (Copenhagen, Denmark) — Large, firm contracts for HVDC power cable systems demonstrate a leaning toward utility‑scale grid reinforcement projects. Their recent award for a major grid reinforcement underscores appetite for long‑duration contracts with system operators.
-
Sumitomo Electric Industries Ltd (Tokyo, Japan) — Strong in very high‑voltage HVDC lines and major subsea link supply. Recent contract awards for 525 kV HVDC projects show the company’s technical positioning at the highest voltage classes.
-
LS Cable & System Ltd (Seoul, South Korea) — Growing presence in high‑voltage HVDC applications and strategic programmes in Asia; capabilities suggest a focus on large interconnector and national transmission projects.
-
Regional and specialist players — Several firms from established manufacturing hubs (including Italy, India and elsewhere) provide competitive depth up to specific voltage classes and are often preferred for local content, shorter lead times and aftermarket services.
Recent developments provide telling market signals: Nexans’ completion of a record‑depth subsea 500 kV HVDC installation (Jan 2026) confirms both technology maturity and the premium buyers will pay for proven installation capability; Sumitomo’s late‑2025 contract for a 525 kV HVDC Sea Link underscores high‑voltage demand in national interconnection projects; and NKT’s firm contract wins (Mar 2026) highlight sizeable programme awards becoming available to bidders in 2026.
Market dynamics and near‑term headwinds
-
Input price inflation and hedging complexity — Copper and polymer feedstock price swings compress margins and complicate fixed‑price contracting. Buyers and suppliers must consider indexation, pass‑through clauses, or hedged procurement strategies.
-
Manufacturing bottlenecks and lead times — High‑voltage cable production and jointing capacity are capital‑intensive; firms that secure long‑lead manufacturing slots will gain bidding advantage for multi‑year programmes.
-
Regulatory programme timing — Decisions by TSOs and national governments (including multi‑billion capex proposals and coordinated offshore initiatives) will create concentrated procurement windows that favor vertically integrated suppliers or consortiums.
-
Installation risk and technical escalation — Deepwater and ultra‑high voltage projects carry installation and testing complexity; record installations signal capability but also raise the stakes on insurance, indemnities and performance bonds.
Practical recommendations — what executives should do in 2026
-
Procurement readjustments — Move from single‑round, fixed‑price tenders to staged contracting with material price indexation and firm slots for critical long‑lead items. Shortlist suppliers with demonstrable recent installation performance.
-
Supply‑chain hedging — Lock in raw‑material forward contracts where justified; use layered buying to smooth exposure and include contingency margins in financial models.
-
Strategic partnerships — Pursue consortiums for high‑risk offshore or HVDC projects to combine manufacturing scale, installation vessels and local permitting expertise.
-
Capability building — For suppliers: invest selectively in high‑voltage HVDC manufacturing lines and jointing technology. For buyers: expand in‑house project‑management teams with subsea and HVDC execution experience.
-
M&A and market entry — Target acquisitions that provide either installation fleet access or specialized jointing/termination capabilities rather than pure volume players. Assess targets against capacity, certificates and recent project track record.
-
Scenario planning — Run stress tests for +20% raw material shock, 6–12 month permit delays and a concentrated procurement window to quantify working capital and schedule impacts before committing to awards.
How boards, CFOs and operations teams should use this research
-
Boards : Use the report’s scenario suite to validate strategic capital allocation, JV structures and M&A prioritization before approving multi‑year commitments.
-
CFOs : Leverage the procurement and cost‑modeling toolkit to refine bid/no‑bid thresholds, approve hedging instruments, and structure payment milestones tied to installation milestones and CPI‑linked indices.
-
Operations and procurement : Adopt the supplier capability matrices and project pipeline tracker to optimize lead‑time sequencing, prequalify partners and align internal resourcing to the procurement calendar.
Conclusion — a strategic preview, not the full map: This article has outlined the strategic contours derived from PW Consulting’s High Voltage Cables Market study and highlighted the core commercial and technical levers that will matter in 2026. We have deliberately presented top‑line market growth indicators and synthesized directional competitive and technical signals to support boardroom decision‑making. For the full, actionable intelligence — including project‑level demand schedules, downloadable financial models, voltage‑class build‑outs, regional pipelines, and supplier scoring matrices — access the comprehensive report and dataset. That is where programmatic procurement decisions, M&A screening and capital planning for the next decade are executable with confidence.
For detailed analysis of this topic, please visit the official page: High Voltage Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Drugs for Schistosomiasis Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a forward-looking briefing that situates the Drugs for Schistosomiasis market within the strategic decision cycle for 2026. This preview highlights the macro trajectory, risk vectors, competitive dynamics, and the actionable themes executives must address to convert epidemiological need into resilient commercial and public-health outcomes. It intentionally surfaces high-value signals and practical implications while reserving granular segmentation and proprietary model outputs for our full market study.
Drugs for Schistosomiasis Market
Why this market matters in 2026
Schistosomiasis remains a high-priority neglected tropical disease with concentrated programmatic spending, frequent mass drug administration (MDA) campaigns, and evolving pharmaceutical supply needs. The overall market shows steady, predictable expansion: from an estimated USD 118.5 Million in 2020 to USD 160.0 Million in our base year (2025), with a compounded annual growth rate of approximately 6.4% through the forecast window to 2032. Under our central forecast the market approaches a mid-to-high two-hundred million USD valuation by 2032, reflecting continued demand for praziquantel-based treatments, pediatric formulations, and emerging combination therapies.
Drugs for Schistosomiasis Market
For corporate leaders—pharma CEOs, commercial heads, supply-chain chiefs, and public-sector procurement officers—this trajectory matters because it combines programmatic predictability with episodic volatility. That combination creates differentiated opportunity windows for manufacturers, contract manufacturers, logistics providers, and private–public partnership investors who can align production, pricing and access strategies with MDA cycles and WHO-driven procurement channels.
Drugs for Schistosomiasis Market
Core dynamics shaping 2026 strategic choices
-
Demand stability vs. episodic shocks: Endemic-country programs and donor-funded MDA create a baseline, predictable demand profile. However, geopolitical tensions, export restrictions, and capacity constraints in specialized manufacturing periodically compress supply—generating short-term price and access shocks that can disrupt national elimination campaigns.
-
Product evolution and access policy: The arrival of pediatric dispersible formulations and WHO prequalification of newer treatment variants has shifted procurement preferences in favor of child-friendly therapies, changing tender dynamics and enabling preferential pricing frameworks in many endemic countries.
-
Competitive structure and cost pressure: Off-patent status for core molecules has fostered a robust generic supply base from cost-optimized manufacturers, increasing price competition for large tenders while concentrating premium value on differentiated formulations and supply reliability.
-
Distribution and last-mile requirements: MDA programs rely on a mix of institutional channels—hospital and community health platforms, government procurement routes, and NGO distribution networks—with growing attention to cold chain simplification, dosing accuracy for children, and on-the-ground logistics capacity.
What this means for strategic planning in 2026
-
Manufacturing and capacity decisions: Firms must balance capitalizing on baseline growth with resilience to episodic supply disruptions. Options include selective capacity expansion, dual-sourcing of active pharmaceutical ingredients (APIs), and strategic contract manufacturing partnerships that prioritize regulatory readiness (e.g., WHO prequalification) for high-volume tenders.
-
Portfolio and product strategy: Plain dose competition will intensify. Margin protection will come from pediatric formulations, combination therapies, and value-added services (e.g., packaging for MDA distribution, integrated training materials). Early investment in child-specific formulations and scalable blister/pediatric packaging is likely to accelerate tender share in the 2026–2028 window.
-
Procurement and pricing playbooks: Buyers—governments and donors—are increasingly awarding contracts based on a mix of price, supply assurance, and WHO prequalification status. Suppliers should construct tiered pricing structures that reflect long-term procurement commitments and include volume and delivery guarantees to win multiyear tenders while preserving commercial viability.
-
Partnership and access models: Success will depend on hybrid models combining commercial distribution with NGO and multilateral partnerships. Strategic alliances with program implementers and funders—particularly those focused on pediatric access—can accelerate adoption while sharing implementation risk.
-
M&A and licensing considerations: Given the market’s moderate scale and the concentration of capability in a subset of suppliers, targeted acquisitions or licensing arrangements—especially for pediatric formulations, WHO-prequalified lines, or regional manufacturing footholds—are an efficient route to scale and tender eligibility.
Competitive landscape: capabilities that matter in 2026
The market is anchored by a small group of established manufacturers and a broader field of generics that serve government procurements. Strategic differentiation is not purely about price; it is about supply reliability, regulatory positioning, and formulation innovation.
-
Large innovator and established suppliers: Global players with WHO-prequalified products and partnerships with implementation bodies are positioned to capture premium opportunities tied to pediatric and program-integrated deliveries. Recent distribution and partnership moves that target preschool-aged children reflect a strategic shift toward integrated public-health engagement models.
-
Generic manufacturers in cost-competitive markets: Established producers in India and East Asia have strong cost positions and are primary contenders for large-volume tenders. Patent expiries have enabled wider participation, making procurement dynamics highly price-sensitive for commoditized formulations.
-
Regional and emerging suppliers: Smaller regional players can win on agility, local regulatory knowledge, and faster lead times—but they must demonstrate consistent quality standards and tend to be disadvantaged in large multilateral tenders without prequalification credentials.
Notable recent developments underscore the market’s practical dynamics: targeted delivery of pediatric formulations in field studies, strategic partnerships between suppliers and elimination-focused NGOs, and episodic production discontinuations that require rapid procurement adjustments. These events crystallize the competitive premium on program-aligned supply models and regulatory readiness.
Report contents — what PW Consulting delivers
Our full Drugs for Schistosomiasis Market report goes beyond top-line forecasting to deliver operationally actionable intelligence for 2026 planning cycles. Key inclusions:
- Robust market-sizing and growth scenarios (historical baseline 2020–2025; detailed forecasts through 2032) with sensitivity analysis to key variables such as API cost, tender volumes, and geopolitical disruption intensity.
- Segmentation analysis across product type, distribution channels and end-user cohorts—presented with commercial-grade assumptions and an interactive dashboard that supports “what-if” tender and pricing modeling.
- Supply-chain and manufacturing capacity maps, including concentration risk heatmaps and recommended dual-sourcing strategies to mitigate single-point failures.
- An operational playbook for winning institutional procurement (tender-response checklists, pricing templates, compliance milestones including WHO prequalification pathways).
- Competitive profiles and strategic scorecards for the key incumbents and high-potential entrants, including assessment of R&D pipelines for pediatric and combination therapies, regulatory posture, and historical tender performance.
- Risk register and mitigation matrix covering regulatory changes, logistics interruptions, reputational exposures, and demand variability tied to program funding cycles.
- Investor and M&A guidance: valuation frameworks, target screening criteria, and integration checklists tailored to the sector’s scale and concentration dynamics.
How to use this intelligence in 90–180 day planning
-
90-day tactical moves: Secure contingent API contracts, validate WHO prequalification status for product lines, and structure price-volume commitments for near-term tenders. Initiate conversations with program partners to align clinical acceptability and distribution readiness for pediatric formulations.
-
180-day strategic moves: Commit to capacity investments or contract manufacturing agreements, deploy a segmented pricing strategy for institutional vs. private-channel customers, and finalize at least one collaboration or distribution partnership in an endemic region to establish a procurement track record.
Bottom line for 2026 decision-makers
The schistosomiasis drugs market is not a high-margin blockbuster sector, but it is strategically significant for companies that can combine product reliability, regulatory readiness, and programmatic alignment. The predictable baseline growth—anchored by steady program funding and evolving pediatric needs—creates a durable commercial case for investments that enhance supply resilience and formulation differentiation. Conversely, failure to secure quality-certified capacity or to partner effectively with procurement stakeholders will relegate suppliers to cyclical, price-driven tendering with narrow margins.
PW Consulting’s full market study contains the granular segmentation, tender-level benchmarking, and proprietary scenario outputs required to operationalize these recommendations. For commercial teams, supply-chain leaders, and strategic planners who must present a defensible 2026 plan to boards or donors, the detailed appendices and playbooks in our report are the tools to close the gap between strategy and execution.
Next steps
To access the full dataset, tender-level intelligence, and the executable playbooks referenced here, consult the PW Consulting report page for the Drugs for Schistosomiasis Market. Our team is prepared to run a condensed, client-specific workshop to translate the findings into a 12–24 month action plan tailored to your organization’s role in the value chain.
For detailed analysis of this topic, please visit the official page: Drugs for Schistosomiasis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com