

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Reusable Gloves Market Poised for 6.5% CAGR Through 2032

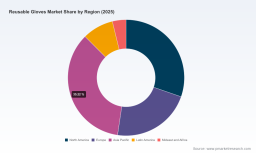
Reusable Gloves Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, judgment-driven preview of our full Reusable Gloves Market study — timed for executives making allocation, sourcing, and R&D decisions in 2026. This preview synthesizes the market trajectory, regulatory inflection points, supplier dynamics, and the practical tools included in the full report. It is intentionally directional: we reveal the macro context and strategic implications while preserving the granular segmentation and proprietary scenarios for subscribers who access the full dossier.
Reusable Gloves Market
Market Trajectory: Where demand is headed
The reusable gloves market has moved from niche cost-savings initiatives to a structural element of occupational safety and clinical supply strategies. On a macro level, the market expanded steadily through 2020–2025, reaching roughly USD 292 million in 2025. Our baseline forecast, incorporating supply-chain normalization, material-cost trends, and policy shifts, projects a compound annual growth rate (CAGR) of about 6.5% for 2026–2032 — bringing the market to an estimated USD 454 million by 2032 under the central case.
Reusable Gloves Market
That pace reflects a balance of forces: accelerating institutional adoption driven by lifecycle economics and sustainability targets, partially offset by continued competition from disposables for certain low-cost, single-use applications. The pattern of growth is not uniform; pockets of accelerated adoption exist where reuse protocols deliver measurable operating savings and compliance advantages. The full report models these pockets with scenario sensitivity and supplier-level impact assessments.
Reusable Gloves Market
Why 2026 is a strategic inflection year
-
Regulatory tightening: The FDA’s Quality Management System Regulation (QMSR) requiring ISO 13485:2016 compliance for medical glove manufacturing became effective in early 2026. For manufacturers and medical-supply procurement teams this raises compliance entry costs and shifts supplier economics — favoring players with established quality systems and capitalized manufacturing footprints.
-
Cost-benefit clarity: Institutional buyers report meaningful savings when migrating to reusable programs. Published field analyses indicate that well-designed reusable programs can cut hand-protection costs materially versus disposables — an especially compelling proposition for high-volume facilities trying to manage operating budgets.
-
Certification and infection control: For clinical use, reusable gloves must meet ASTM and EN standards for chemical permeation and dexterity. Compliance is now non-negotiable for infection control committees, and suppliers who can demonstrate certified performance gain access to hospital formularies at scale.
-
Operational realities: Reuse introduces upstream and downstream costs — notably laundering, inspection, and re-sterilization protocols that can add approximately 10–15% to operational labor costs for hospital programs. When these labor and logistics costs are modeled alongside per-use material savings, the economic case requires rigorous, site-level analysis.
Strategic implications for stakeholders
For executives, 2026 decisions should be framed not as binary “reuse versus disposable” choices but as system-level optimizations. Our research highlights five pragmatic moves:
-
Adopt a lifecycle procurement lens. Move beyond per-unit pricing to measures like cost per use, waste handling, and compliance risk. Organizations that integrate this into supplier RFQs gain a sustainable cost advantage.
-
Prioritize certified suppliers with scalable quality systems. The capital and procedural requirements implied by ISO 13485 compliance mean fewer low-cost entrants will be able to service clinical segments. This creates premium for established suppliers that can demonstrate repeatable, auditable quality.
-
Invest in centralized laundering and inspection protocols where volumes justify it. Centralization reduces per-use costs and improves traceability but requires upfront systems and governance investment. Our financial model shows payback timelines at the facility and network levels.
-
Leverage supplier partnerships for co-innovation. Material science advances (e.g., enhanced nitrile formulations, antimicrobial linings) and ergonomic design improvements are differentiators. Strategic suppliers are open to joint testing and shared risk pilots.
-
Validate sustainability and occupational safety metrics. Reusable programs reduce waste streams but shift environmental and operational footprints. Decision frameworks should include lifecycle carbon and labor implications to satisfy ESG and risk committees.
Competitive landscape — who matters and why
The market remains moderately fragmented: the three largest players account for a modest share of global revenue, and the five largest capture roughly one-third of the market, leaving substantial room for regional specialists and niche innovators. The competitive map is shaped by a few structural variables: product durability and performance, regulatory compliance and certification, manufacturing footprint, channel reach, and services such as laundering and end-to-end program support.
-
Ansell Ltd (Melbourne, Australia) — A recognized manufacturer across nitrile and latex reusable gloves, with product lines tailored to healthcare, laboratory, and industrial applications. Ansell’s advantage is a broad certified portfolio and established relationships in clinical procurement.
-
Honeywell International Inc. (Charlotte, NC, USA) — Focused on industrial and specialty segments, Honeywell leverages scale and distribution to serve cut-resistant and high-durability needs, emphasizing workplace safety programs and integrated PPE solutions.
-
Showa Group (Japan) — Known for chemical resistance and antimicrobial treatments across reusable nitrile and latex ranges. Showa’s R&D focus on material performance makes it a preferred supplier in environments with elevated chemical exposure risk profiles.
-
MAPA Professional GmbH (Germany) — Positions itself on durability and tactile performance for medical and laboratory markets, with localized manufacturing strengths in Europe that benefit buyers seeking shorter lead times and regulatory alignment.
-
Sempermed USA Inc. (Austria / US operations) — An established player servicing healthcare and industrial channels; its cross-border manufacturing footprint and medical-grade product lines align with buyers requiring certified, consistent supply.
-
Reflexx (Italy) — Specialist in multiple material technologies including nitrile, latex, and neoprene. Reflexx competes on product breadth and customizability for professional and medical applications.
Recent industry activity underscores the dynamic nature of the market. In 2025 several manufacturers launched new lines — for example, chemotherapy-rated nitrile gloves and low-protein latex examination gloves — reflecting both clinical demand and material innovation. These launches signal continued product-level differentiation rather than commoditization.
Where winners will emerge
Winning suppliers and buyers will be those who integrate three capabilities: certified product performance, supply reliability under evolving regulatory regimes, and services that lower the total cost of ownership (TCO) for end-users. The mid-term competitive advantage will accrue to organizations that can bundle high-performance materials with program services (e.g., laundering, traceability, warranty) and whose financial models make adoption economics transparent for clients.
What the full PW Consulting report delivers
The full study is designed as a decision-support toolkit for 2026 planning cycles. Key deliverables include:
-
A detailed market model (2020–2032) with central, upside, and downside scenarios, enabling sensitivity testing against material-cost shocks, regulatory adoption timelines, and labor-cost variations.
-
Supplier benchmarking scorecards that evaluate quality certifications, production capacity, lead times, channel reach, and service offerings.
-
Lifecycle cost calculators that quantify per-use economics, factoring in laundering, inspection labor, replacement rates, waste handling, and compliance expenditures.
-
Regulatory playbook and compliance checklist aligned to FDA QMSR/ISO 13485 and key ASTM/EN standards — designed for procurement and compliance teams drafting RFPs and supplier audits.
-
Commercial playbooks for OEMs and private-label entrants that map go-to-market choices, margin structures, and partnership models with service providers.
-
Case studies and pilot designs illustrating measurable pathways to up to 30% savings in hand-protection costs where programs are optimized — with sensitivity ranges and realistic operational assumptions.
How to use this preview in your 2026 planning
Use this analysis to set three immediate priorities for 2026: (1) audit supplier compliance and certification status against ISO 13485 and relevant ASTM/EN standards; (2) run a targeted lifecycle-cost pilot in high-volume sites to validate per-use equations while capturing laundering and labor overheads; and (3) reassess supplier contracts to include service-level agreements tied to traceability, durability, and program-support commitments.
These steps convert the macro growth trajectory and regulatory shifts into operational action — narrowing uncertainty while preserving optionality for different adoption speeds across regions and applications.
Conclusion — the tactical payoff
With the market expanding at a steady mid-single-digit CAGR and regulatory forces raising the bar for clinical-grade supply, 2026 is a year to convert strategy into operational protocols. The reusable gloves category is moving from cost-avoidance experiments to scaled program adoption where certified performance, supply reliability, and service-enabled economics determine who captures value.
For readers seeking the granular segmentation, supplier scorecards, and the full suite of modeling tools that underpin this preview, the complete PW Consulting Reusable Gloves Market report provides the necessary detail to implement and defend 2026 capital and procurement choices. Accessing the full report will unlock the proprietary scenarios, regional breakouts, and supplier-level financials we deliberately withheld from this preview to preserve its function as a strategic “trailer.”
For detailed analysis of this topic, please visit the official page: Reusable Gloves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com