

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Alternate Light Sources Market to Grow from USD 470.83 Million in 2025 to USD 694.05 Million by 2032 at a 5.72% CAGR
By pmarketresearch, 2026-08-12
Worldwide Alternate Light Sources Market — Strategic Briefing for 2026
Executive summary
PW Consulting’s latest market intelligence on Worldwide Alternate Light Sources (ALS) synthesizes five years of historical dynamics and a seven‑year forward view to equip executives with the evidence-based perspective required for 2026 decisions. Our assessment shows a resilient market trajectory: a measured expansion from a mid‑hundreds million USD base in 2020 to a substantively larger market in 2025, with the forecast driving continued growth through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.72%. Competitive concentration is moderate — a handful of leaders command a meaningful share while an active middle tier and small specialists continue to innovate. This briefing highlights the strategic choices that will matter next year and where our full report delivers the operational detail that decision-makers will need.
Disposable Hospital Curtain Market
Market trajectory and what the headline numbers mean for 2026
-
Momentum: After recovering and expanding across 2020–2025, the ALS market is positioned for steady expansion in 2026 as forensic, medical, and industrial use cases normalize and invest in upgraded, wavelength‑agile tools.
Worldwide Pro Audio Market -
Predictability: The 5.72% CAGR built into our 2026–2032 forecast reflects a market that is not hyper‑volatile but is responsive to technology refresh cycles (LED and laser advances), procurement cadences in public safety and healthcare, and episodic large tender opportunities.
Worldwide Automated Storage and Retrieval Systems (ASRS) for Cold Storage Food Facility Market -
Concentration: Market concentration metrics indicate opportunity for both incumbents and challengers — established specialist vendors maintain leadership through brand, validated workflows and field‑proven kits, while nimble entrants compete on price, form factor, or niche capability (e.g., laser modules, ruggedized systems).
Drivers and constraints
-
Technical innovation: Ongoing miniaturization and improved spectral control in LED and laser platforms are increasing the effectiveness of field ALS units and expanding lab capabilities for luminescence and fluorescence applications.
-
Procurement patterns: Law enforcement and forensic laboratories are beginning to layer lifecycle-centric procurement (purchase, calibration, PPE, and training) into budgeting, increasing the value of bundled offers and managed‑service models.
-
Regulatory and standards influence: Definitions and use cases codified by NIST, inclusion of portable forensic light kits in the U.S. DHS Authorized Equipment List, and SWGDE guidance on documentation and safety are formalizing buyer requirements — raising the bar for compliance and training documentation offered by vendors.
-
Health and safety considerations: Shortwave UV remains effective for certain evidence detection but carries occupational risk; suppliers and buyers must prioritize PPE, user training, and clear safety specifications to avoid liability and ensure operational continuity.
Strategic implications for 2026 decisions
-
Product roadmap prioritization: Firms should accelerate investment in multi‑wavelength LED platforms with modular filters and ruggedized enclosures. Product roadmaps that prioritize spectral agility, battery efficiency, and simplified field operation will capture procurement mandates emphasizing ease of use and lifecycle cost.
-
Commercial models: Growing institutional buyers favor bundled solutions (device + filter + training + calibration). Vendors that can demonstrate a low‑total‑cost‑of‑ownership offering will outcompete unit‑price focused suppliers in public sector tenders.
-
M&A and partnership playbook: Given moderate concentration, there is room for acquisitive scale plays (to expand geographic reach or add complementary product lines) and bolt‑on purchases that fill capabilities — e.g., compact lasers, specialized filters, or software for evidence documentation.
-
Go‑to‑market focus: Sales teams should emphasize compliance credentials (DHS AEL alignment, SWGDE best practices) and outcomes (reduced false negatives, faster on‑scene processing). Proof points such as validated lab studies and documented field deployments will shorten procurement cycles.
-
Risk mitigation: Buyers and vendors must embed safety and training into commercial terms. Shortwave UV specifications in contracts should include manufacturer‑mandated PPE, training modules, and service plans to minimize operational and legal risk.
Competitive landscape — how to read vendor capabilities in 2026
The sector is populated by a mix of legacy forensic specialists, instrumentation houses, and small, highly focused manufacturers. Our vendor analysis in the full report profiles each major supplier against a consistent set of criteria: product breadth, spectral capability, ruggedization, certification/compliance, service footprint, and reference installations. Highlights for boardroom consideration:
-
Foster + Freeman (UK) — A long-standing innovator in high‑intensity LED forensic light sources. Their Crime‑lite family, spanning handheld to multi‑spectral laboratory systems and laser offerings, exemplifies a premium, lab‑validated approach. Strategic managers should view them as a reference for multi‑wavelength, high‑performance positioning.
-
Labino AB (Sweden) — Known for waterproof, user‑friendly ALS kits designed for rapid crime scene deployment. Recent catalog updates reinforce an approach favoring simplicity and field reliability — attributes that resonate with first responders and international buyers with ruggedization requirements.
-
Sirchie (USA) — A broad portfolio targeting law enforcement with compact, tactical ALS solutions and UV offerings. Their positioning aligns with procurement teams seeking cost‑effective, field‑ready options and packaged training materials.
-
HORIBA Scientific / SPEX Forensics (USA) — Brings laboratory instrumentation expertise to the ALS category with products tailored for forensic laboratories. Their emphasis on documentation and instrument performance is a differentiator for institutional lab purchases.
-
FoxFury (USA) — Specialist in rugged, cordless forensic lighting; their product set targets investigators who prioritize portability and power. Organizations with austere field requirements should evaluate FoxFury as a prime candidate.
-
Lynn Peavey Company & UltraLite ALS (USA) — Distributors and focused suppliers of portable forensic solutions. They play an important role in localization of service, supply chain resilience, and bundled forensic consumables.
Recent developments shaping 2026 dynamics
-
Product refreshes: In early 2025 vendors released incremental and next‑generation products — from updated ALS kit catalogs to new multi‑spectral units — signaling continued investment in both field and lab segments.
-
Standards and lists: Inclusion of portable ALS components in recognized equipment lists and the prominence of NIST and SWGDE guidance are raising buyer expectations for documentation, safety, and interoperability.
-
Technology diffusion: LED and laser technologies are moving from premium lab boxes deeper into handheld and ruggedized formats, compressing the time between lab innovation and field availability.
What PW Consulting’s full report delivers (practical, executable content)
Our market study is intentionally operational. For decision‑makers considering investment, procurement, product development or M&A in 2026, the full report contains:
-
Robust market sizing and validated forecast (2026–2032) with scenario analysis calibrated to procurement cycles and technology adoption curves.
-
Commercial playbooks for suppliers and buyers — tender templates, contract clauses covering safety and lifecycle support, and pricing strategy frameworks.
-
Vendor scorecards and a shortlist methodology that maps capability gaps to acquisition targets or partnership candidates without relying on raw price competition.
-
Use‑case matrices showing which ALS attributes matter most by operational profile (forensic scene, lab, medical diagnostics, industrial inspection), and sample procurement spec language that aligns with NIST/DHS/SWGDE expectations.
-
Implementation checklists for safety & training, product validation protocols, and a calibration/service benchmarking tool for post‑purchase maintenance planning.
-
Risk registers and sensitivity analyses addressing regulatory shifts, supply chain fragility, and rapid obsolescence in spectral control technologies.
How to act in 90–180 days
-
Buyers: Run a short pilot that tests multi‑wavelength field kits against existing workflows; require suppliers to supply safety and training packages as part of the pilot scope.
-
Vendors: Accelerate development of bundled commercial offers (device + training + service). Use pilot results to build case studies that speak to compliance and outcome metrics.
-
Investors / M&A teams: Prioritize targets that provide modular capabilities (spectral modules, laser add‑ons, digital documentation tools) or add depth to a regional service footprint.
Conclusion — the strategic value of this report for 2026
As agencies and institutions move beyond pandemic‑era procurement rhythms and focus on capability consolidation, ALS suppliers and buyers face a year in which clarity of product value, compliance credentials, and lifecycle economics will drive competitive outcomes. PW Consulting’s Worldwide Alternate Light Sources Market report is designed to be a decision accelerator: it validates market direction with quantitative forecasting, converts standards and regulatory signals into procurement and product requirements, and supplies the playbooks necessary for tactical execution in 2026.
Next step
For access to the full dataset, vendor scorecards, procurement templates and the scenario models that underpin our 2026 recommendations, please consult the complete report page. PW Consulting’s analysts are available to brief executive teams and to tailor the findings into a workshop or procurement readiness program.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Lock with Cat’s Eye Market Poised for 13.5% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Smart Lock With Cat's Eye Market — Strategic Preview for 2026
PW Consulting presents a strategic preview of our definitive market study, "Worldwide Smart Lock With Cat's Eye Market." This briefing distills the macro trends, competitive dynamics, regulatory vectors, and actionable 2026 playbook that senior executives, product leaders, corporate development teams, and security integrators will rely on for decision-making. It intentionally refrains from publishing the granular segment tables and region/application splits contained in the full report — those are preserved for subscribers — while delivering the analytical signal you need to prioritize investments and mitigate near-term regulatory and competitive risk.
Worldwide Glass Serological Pipettes Market
Market trajectory at a glance
The smart lock market integrated with cat's eye (visual peephole) capabilities moved from an emergent niche in 2020 into a fast-scaling market by 2025. Our base-year accounting shows the market expanding from approximately USD 850 million in 2020 to USD 1,550 million in 2025 (USD, Million). Under the scenarios modeled in this study, market value continues to accelerate through the forecast window 2026–2032, reaching roughly USD 3.76 billion by 2032. The modeled compound annual growth rate for the forecast period is 13.5% — a rate that confirms this segment is transitioning from early-adoption to broad commercial adoption and commoditization pressures.
Worldwide Heparin Lithium Market
Why 2026 is a strategic inflection point
- Product-to-platform transition: The category is moving beyond isolated hardware features (camera resolution, lens angle) to integrated experiences that combine device-level intelligence, cloud services, and home-platform interoperability. This shift makes 2026 the year many product strategies must pivot from single-device feature races to ecosystem plays.
- Regulatory crystallization: Emerging privacy and tenant-protection rules in multiple jurisdictions will materially affect product design, deployment practices, and commercial contracts. Companies that treat compliance as an afterthought will face adoption headwinds.
- Channel and margin realignment: As consumer awareness rises and distribution broadens, price-sensitive channels will pressure hardware margins, while recurring-revenue services (video storage, verified visitor logs, platform subscriptions) will become the new battleground for lifetime value.
What our full report delivers (practical, transaction-ready content)
The PW Consulting report is structured for immediate use by leadership teams executing in 2026. Key deliverables include:
Coal Logistics Market
- Top-down market sizing and bottom-up scenario models calibrated to macro adoption curves, device replacement cycles, and policy scenarios — enabling sensitivity testing for P&L and capex plans.
- Risk matrices that quantify regulatory exposure across jurisdictions, with "decision triggers" for product lock-steps (e.g., camera disable modes, retention caps, anonymization defaults) that should be embedded in roadmaps.
- Technology roadmaps and vendor capability maps that cross-reference biometric modalities (including 3D face recognition), camera optics (field of view requirements), on-device AI inference capacity, and cloud integration constraints.
- Commercial playbooks for go-to-market: recommended channel mixes by buyer persona, pricing levers for hardware-plus-service offers, and retention strategies for subscription monetization.
- M&A & partnership screening tools: a prioritized shortlist of target archetypes, due-diligence checklists focusing on software IP, manufacturing scalability, and certification readiness.
- Supply chain and sourcing playbooks that outline contract manufacturing strategies, component concentration risks, and mitigants for camera sensor and secure-element shortages.
- Competitive benchmarking templates and a vendor scorecard you can use to accelerate vendor selection and procurement decisions.
Competitive landscape — who matters and why
The competitive set combines global hardware brands, telco-scale vendors, platform enablers, and specialized OEMs. Market concentration is moderate: our CR3 and CR5 analysis show that leading groups command a meaningful, but not overwhelming, share (CR3 ≈ 32.5%; CR5 ≈ 41.2%). This structure creates room for technology differentiation, regional champions, and targeted M&A.
- Xiaomi (Beijing, China) — Xiaomi has adopted a volume-led strategy paired with frequent product refreshes. Their recent launches (2025) focused on larger indoor display experiences, wide-angle cat's eye feeds, AI human detection, night vision, and a broad array of unlocking modes. Xiaomi’s go-to-market advantage is its integrated smart-home ecosystem and retail reach; their play demonstrates how consumer brands can drive category awareness rapidly.
- Huawei (Shenzhen, China) — Huawei emphasizes integrated surveillance-grade features and multi-modal unlocking with on-device AI detection. The company’s strategy targets premium home-security buyers and leverages its systems-engineering capabilities to embed wide-angle optics and advanced inference on-device, serving customers concerned with latency and privacy.
- Yale (ASSA ABLOY, USA/global) — Yale represents the incumbent security heritage brand that is migrating trust in mechanical and electromechanical security to connected solutions. Their portfolio priorities show that strong channel relationships and brand trust still matter for adoption in traditional homeowner and property-management segments.
- Tuya Inc. (Hangzhou, China) — Tuya is a platform enabler. Their value prop is rapid OEM enablement, cross-manufacturer interoperability, and a route to cloud/services monetization. For OEMs and smaller brands, platform partners like Tuya remain a fast path to feature parity without heavy up-front software investment.
- Specialized OEMs (PuXin Smart, Locstar, Botin Smart Technology) — These vendors spotlight how product-level innovation (e.g., 1M-pixel cameras, 1080p indoor screens, 3D face recognition integrations) can be commercialized through white-label and channel-focused strategies. They are also the most agile acquirers and partners for larger platforms seeking capacity or niche IP.
Technology and product trends to prioritize in 2026
- Edge-first AI for privacy and latency: Moving inference onto the device reduces bandwidth and retention risk while improving responsiveness for anti-spoofing and human-detection workflows.
- Wide-angle optics and UI design: Field-of-view claims are table stakes; the real differentiator is user experience — large indoor feeds, one-touch evidence export, and frictionless access logs.
- Interop-first product architecture: Open APIs and certified integrations with major smart-home platforms elevate resale and retention across channels.
- Hardware as a carrier for services: Monetizable services (secure cloud storage, verified visitor credentials, concierge integrations) should be mapped to three-year LTV scenarios to justify customer-acquisition spend.
Regulatory and privacy vectors — designing for compliance by default
Regulatory noise is no longer hypothetical. In several markets the legal framing around camera-equipped door devices is tightening. Our dynamics analysis highlights three themes:
- In some jurisdictions, existing standards still focus narrowly on mechanical safety and lack uniform guidance for camera recording, retention, or triggered capture — creating legal ambiguity for manufacturers and integrators.
- In regions governed by comprehensive data-protection laws (for example, GDPR-style regimes), device designers must ensure footage is strictly for private purposes and that optics avoid capturing neighbors or public spaces without clear legal bases.
- Localized statutes — such as tenant-data protections in certain urban centers — introduce requirements for consent, key-preservation, data minimization, and retention limitations that can alter product deployment economics.
For product and legal teams, the implication is straightforward: build privacy controls into UX flows, offer hardware-level camera-disable options, provide retention defaults aligned with the most stringent markets you plan to enter, and bake those constraints into your product requirement documents and contracts.
Actionable recommendations for corporate leaders in 2026
- Prioritize platform partnerships over point-feature races: If you are scaling, partner with platform enablers that reduce time-to-market while preserving pathways to proprietary services. If you are defending margin, invest in services that lock in recurring revenue.
- Adopt "privacy by default" product specs: Align firmware and cloud defaults to the strictest regulatory environment you serve. This reduces downstream retrofit costs and litigation risk.
- Refine go-to-market segmentation: Use the full report’s buyer-persona matrices to allocate channel investments toward high-LTV segments (e.g., property managers, smart-home premium buyers) where service monetization is realistic.
- Embed edge-AI and secure elements: Competitive advantage will accrue to products that deliver reliable on-device inference, anti-spoofing, and cryptographic key protection without increasing BOM beyond acceptable channel thresholds.
- Prepare an M&A playbook focused on capability gaps: Look for targets with verified software IP, proven manufacturing scale, or regional certifications that shorten time-to-market and regulatory approval cycles.
How the PW Consulting report powers your 2026 decisions
Our report provides the analytical instruments executives need to make high-stakes choices under uncertainty. Subscribers receive:
- Stress-tested forecasts (base, upside, downside) with sensitivity levers for pricing, conversion rates, and regulatory compliance costs;
- Vendor scorecards and procurement templates that accelerate vendor selection while protecting margin assumptions;
- Decision trees and implementation checklists for privacy-first feature rollouts and region-specific certification strategies;
- Transaction intelligence including valuation multiples for recent exits/acquisitions in adjacent categories and an M&A target heat map.
Importantly, this preview intentionally withholds the granular region, type, and application split tables and detailed unit-price thresholds that are included in the full report. Those tables are the output of our proprietary triangulation across shipment data, channel checks, and OEM interviews and are essential for tactical procurement and M&A diligence.
Concluding perspective
The smart lock market with integrated cat's eye capability is no longer an experimental niche — it is becoming a mainstream element of residential and commercial security portfolios. The growth profile is compelling, but the path to durable margin requires executives to master three disciplines in 2026: platform economics, privacy-compliant product design, and disciplined channel monetization. Companies that refactor roadmaps toward services and regulatory resilience will capture disproportionate value as the market scales at an anticipated 13.5% CAGR through 2032.
For boards, C-suite executives, and investors preparing capital allocation and product roadmaps for 2026, our full report supplies the granular segmentation, vendor benchmarks, and scenario tools necessary to convert this strategic preview into executable plans. To access the comprehensive dataset, strategic appendices, and vendor scorecards, refer to the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Lock With Cat's Eye Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Reusable Food Wrap Market to Rise from USD 245.0 Million in 2025 to USD 397.3 Million by 2032 at a 7.15% CAGR
By pmarketresearch, 2026-08-12
Worldwide Reusable Food Wrap Market: Strategic Imperatives for 2026 — A PW Consulting Outlook
Executive snapshot
As brands, manufacturers, and investors prepare their 2026 road maps, the reusable food wrap market presents a compelling mix of steady demand growth, regulatory tailwinds, and supply‑side complexity. Our latest PW Consulting report finds the global market expanding from roughly USD 173.5 million in 2020 to USD 245.0 million in 2025, with a forecast trajectory that anticipates continued expansion at a compound annual growth rate (CAGR) of 7.15% through the 2026–2032 window — reaching an estimated USD 397.3 million by 2032. These headline metrics frame a market that is maturing but still fragmented, where disciplined strategy can meaningfully move the needle on share and margin.
Solar Panel Recycling Management Market
Why this matters for 2026 decision‑makers
- Commercialization timing: A mid‑single digit CAGR masks pockets of accelerated adoption driven by policy shifts, retail assortment changes, and rising consumer interest in circular solutions. Companies that translate macro momentum into targeted GTM pilots in 2026 will be best positioned to scale in the second half of the decade.
- Regulatory acceleration: Emerging legislation in the United States — from statewide packaging mandates to single‑use restrictions — is already compressing runway for disposable alternatives and creating immediate demand avenues for reusable solutions. This dynamic reshapes procurement requirements for food service and retail buyers in the near term.
- Supply chain sensitivity: Raw material cost and availability are now first‑order considerations for product cost curves and margin planning. Volatility in beeswax pricing and diverse quality standards across sourcing geographies require active procurement strategies and scenario planning.
Data signals to watch — and act on
Several quantifiable indicators in our study have direct strategic implications for 2026 planning:
Worldwide Portable Flares Market
- Market scale and pace: The market’s progression from the mid‑hundreds of millions in 2020–2025 into the forecast period underscores sufficient consumer and commercial demand to justify investment in manufacturing scale, new SKUs, and channel expansion.
- Concentration and competitive structure: The sector remains relatively unconsolidated: the three‑firm and five‑firm concentration ratios indicate a market where incumbents coexist with numerous regional and niche players. That fragmentation creates M&A and partnership opportunities for companies aiming to build integrated platforms or secure distribution footholds.
- Raw material dynamics: Market intelligence shows transactional spikes and broad variance in beeswax pricing — for example, visible trades recorded at approximately USD 18.29/kg in late‑2025 contrasted with other reported average export price series. These differences reflect supply chain segmentation (spot trades vs. contract volumes) and imply that procurement sophistication — hedging, alternative raw materials, certification premiums — will directly influence cost competitiveness.
Regulatory context shaping demand in 2026
Policy measures are moving from aspirational goals toward enforceable standards. State‑level actions in the U.S. requiring recyclability/compostability of single‑use packaging and targeted bans on single‑use foodware are already influencing RFPs, buyer specifications, and retailer listings. For companies targeting commercial channels (food service, institutional procurement), compliance pathways and certification capabilities must be front‑and‑center in product development and sales messaging for 2026.
Worldwide Cherry Oil Market
Competitive landscape — practical insights
The market features a mixture of pioneering boutique brands, purpose‑led startups, and specialized manufacturers. Notable participants include established pioneers that have built brand equity around organic and certified supply chains, alongside large manufacturers offering OEM/ODM services with global compliance capabilities.
- Brands with strong storytelling and certification pedigree have an advantage in premium retail and direct‑to‑consumer channels. Their differentiation is rooted in material provenance, design, and lifestyle positioning.
- Manufacturer‑suppliers with scale and compliance credentials are winning institutional contracts and private‑label business, especially where price, minimums, and regulatory documentation matter.
- Across the value chain there is room for consolidation. Strategic buyers seeking rapid scale should evaluate bolt‑on acquisitions that bring manufacturing capacity, quality certifications, or distribution reach in key markets.
Profiles in our analysis include market pioneers known for organic, GOTS‑certified offerings; innovative zero‑waste brands building lifestyle portfolios; and major Asian manufacturers with LFGB/REACH/FDA capability that supply both branded and private‑label channels. The competitive map is a mosaic of brand equity, manufacturing competence, and channel intimacy.
What our full report delivers (practical, actionable content)
This research is designed as an operational toolkit for teams making 2026 commitments. Highlights include:
- Granular market sizing and a transparent forecasting model with scenario analysis and sensitivity testing to model material cost shocks and policy acceleration.
- Supply chain deep dives covering raw material markets, contract vs. spot dynamics, quality differentials, and a procurement playbook that outlines hedging, blended sourcing, and back‑to‑back contracts.
- Regulatory impact matrices mapping key jurisdictions to compliance actions and buyer requirements, enabling commercial teams to prioritize target accounts and tailor qualification documents.
- Channel profitability models by sales route (retail, DTC, food service, private label) with illustrative unit economics and SKU rationalization guidance.
- Competitive benchmarking of leading brands and manufacturers — capability heatmaps that compare certification, design IP, manufacturing scale, and channel penetration.
- M&A and partnership playbooks, including valuation frameworks, integration risk checklists, and a short list of acquisition archetypes that unlock rapid scale or capability.
- Primary research findings: buyer personas, procurement RFP excerpts, and 10 case studies showing how incumbents and challengers implemented rollouts with timeline and cost outcomes.
Strategic recommendations for 2026
- Prioritize procurement resilience: Establish multi‑tier supplier relationships for beeswax and alternative coatings, introduce minimum supply contracts, and budget for short‑term price stress in 2026 financial plans.
- Certify and document: Secure relevant material and process certifications (GOTS, FDA, LFGB, REACH where applicable) to unlock retail listings and institutional RFPs that will increasingly require documentary proof.
- Segment go‑to‑market by buyer need: Deploy distinct propositions for lifestyle retail (design, organic credentials), food service (durability, cost-per-use), and private label (price, lead times). Use pilots in high‑value accounts to refine pack formats and reuse messaging.
- Use policy as a growth lever: Map regulatory timelines to account prioritization — e.g., jurisdictions with imminent single‑use mandates should be targeted first for commercial partnerships and distribution investments.
- Evaluate strategic scale options: For mid‑sized players, assess M&A or joint ventures that add manufacturing capacity, compliance documentation, or access to institutional channels. For investors, target assets that combine brand premium with manufacturing control.
- Measure total cost of ownership for buyers: Create buyer tools that quantify cost‑per‑use and environmental benefits to dismantle price resistance in procurement processes.
Conclusion — the 2026 inflection point
The reusable food wrap market is entering a transitionary phase: robust headline growth, clear regulatory momentum, and supply‑side nuances that reward preparation and specialization. For companies willing to act in 2026 — by shoring up supply, certifying products, and aligning commercial models to buyer procurement cycles — the opportunity is to convert category growth into defensible, higher‑margin businesses.
Next steps — where to get the full intelligence
This article is a strategic preview designed to surface the most consequential decisions for 2026. Our complete Worldwide Reusable Food Wrap Market report provides the underlying datasets, regional and application splits, company revenue estimates, and downloadable financial models that support execution. To access the full report, detailed segment tables, and the proprietary scenario model, visit the PW Consulting report page or contact our market intelligence team.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting report: Worldwide Mosquito Repellent Water for Pregnant Women Market to expand at 7.5% CAGR through 2032
By pmarketresearch, 2026-08-12
Worldwide Mosquito Repellent Water For Pregnant Women Market: Strategic Preview for 2026 Decisions
PW Consulting today releases an executive preview of our newest market research: the Worldwide Mosquito Repellent Water For Pregnant Women Market. This briefing distills the report’s strategic implications for executive teams making portfolio, R&D, channel, and M&A decisions in 2026. It highlights the macro trajectory, key competitive dynamics, regulatory contours, and the practical playbook included in the full report—while intentionally withholding the granular segmentation matrices and country-level opportunity maps that are part of the paid deliverable.
Worldwide Cloud Management Platform (CMP) Market
Macro trajectory: a resilient, mid‑single‑digit market with clear upside
The segment has demonstrated steady expansion through the first half of the decade, rising from a modest base in 2020 to a materially larger global market by 2025. Our base-year model (2025) values the market at approximately USD 275 million, with projections pointing to sustained growth into the forecast window. Under our central scenario, the market grows at a compound annual growth rate (CAGR) of roughly 7.5% through 2032, arriving at a markedly larger market by the end of the period.
Worldwide Anti Mould Paints Market
For strategy teams, these high‑level dynamics matter: the category is not a hyper‑scale mass market yet, but it is large enough and growing quickly enough to justify dedicated product lines, targeted regulatory investments, and channel experiments—particularly for firms that can credibly address safety and efficacy for pregnant consumers.
Worldwide Jowar Flour Market
Drivers and structural dynamics shaping 2026 strategy
- Health‑first consumer framing. Pregnant consumers and their care networks are increasingly informed and risk‑averse, favoring products that are supported by authoritative guidance. Public health agencies and professional organizations continue to emphasize EPA‑registered repellents as the primary option for disease prevention in pregnancy when applied as directed.
- Regulatory clarity reduces ambiguity. Continued guidance from major health authorities reinforces the safety profile of a defined set of active ingredients when used according to label directions (for example, DEET up to 30% and alternatives such as picaridin and IR3535). That regulatory clarity lowers the bar for market entry while increasing the importance of proper labeling and regulatory compliance.
- Product differentiation through formulation science. Leading products combine proven actives with skin‑compatibility additives—e.g., humectants and dermatologically friendly bases—to address concerns around sensitivity, hydration, and odor for pregnant women. This creates a defensible R&D pathway beyond simply changing active ingredients.
- Channel evolution and trust signals. Pharmacies, prenatal care channels, and regulated online specialty retailers are becoming primary discovery and purchase points due to their ability to convey health‑safety credentials. Digital education (content and live support) is an increasingly important adjunct to product labels.
- Supply chain and raw material considerations. Demand for certain actives and compatibility agents is heightening sourcing risks and supplier bargaining dynamics, making early supplier diversification and strategic inventory decisions more critical for 2026.
Competitive landscape: incumbents, challengers, and how they are positioning
The market’s concentration is moderate: our competitive analysis indicates that the top three firms account for roughly one‑third of global industry revenue, with a top five presence approaching half of the total—an environment that favors both scale and agility. Below we summarize the competitive archetypes and strategic behaviors that corporate leaders must weigh when crafting plans for 2026.
- Global CPG incumbents (scale + regulatory muscle). Firms such as SC Johnson (OFF! brand) leverage robust regulatory teams, wide manufacturing footprints, and established trade partnerships. Their strength is in rapid label‑compliant product rollouts and shelf presence within conventional retail—useful where risk‑averse consumers seek familiar brands with authoritative backing.
- Specialist outdoor/repellent brands (technical credibility). Companies like Sawyer and Repel (Spectrum Brands) focus on efficacy messaging, often emphasizing specific active ingredients with well‑documented performance. Their channels blend outdoor specialty retail with pharmacy placements to reach both expectant mothers and broader protective users.
- Niche, pregnancy‑focused innovators. Players such as PARA'KITO and certain regional manufacturers have carved a niche by marrying family‑oriented safety messaging with product formats and marketing targeted at pregnant buyers; they often push formulation innovations and softer ingredient portfolios while relying on regional or online distribution to scale.
- Regionally focused OEMs and formulators. Some manufacturers are optimizing products for local consumer preferences (hydration, scent, application method) and regulatory thresholds—this gives them agility but creates challenges in scaling globally without additional compliance investments.
For decision‑makers, the takeaways are straightforward: incumbents compete on trust and reach; specialists compete on technical claims and channel targeting; and challengers compete on niche safety or formulation narratives. Winning in 2026 will require a hybrid approach that combines authoritative evidence, accessible channels, and product comfort.
Product and formulation trends to prioritize in 2026
- Evidence‑backed actives with user‑centric adjuncts. Products pairing proven repellents (e.g., regulated options supported by safety reviews) with skin‑care additives such as hyaluronic acid or other humectants are gaining traction. This is a tangible product playbook for brands seeking both clinical credibility and consumer comfort.
- Labeling, claims, and advisory tools. Transparent, clinically framed labeling that references regulatory guidance—backed by accessible educational assets for prenatal providers—drives uptake. Brands that invest in clear advisory tools for pregnant users accelerate adoption.
- Format experimentation. Spray and roll‑on formats optimized for even coverage, low inhalation exposure, and ease of application for pregnant users are favored. Packaging innovations that communicate dosing and precautions simply are powerful trust builders.
- Digital health integration. Integration of helplines, chat, and digital dosing reminders embedded in e‑commerce experiences supports conversion and repeat purchase among pregnant cohorts.
Strategic imperatives for 2026 corporate decision‑makers
As companies set budgets and allocate resources for 2026, the following strategic imperatives should be considered. Each recommendation is linked to practical implications and near‑term actions that PW Consulting’s full report unpacks in operational detail.
- Prioritize regulatory and labeling investments. Secure EPA/region‑equivalent registration where feasible; invest in labeling that explicitly addresses pregnancy safety per authoritative guidance. Immediate action: allocate budget and project timelines for registrations and third‑party safety reviews.
- Develop differentiated formulation roadmaps. Create product roadmaps that pair validated actives with skin‑care adjuncts to address pregnant consumers’ sensitivity concerns. Immediate action: establish cross‑functional R&D sprints to test combinations that do not compromise repellent efficacy.
- Channel‑led go‑to‑market strategies. Prioritize pharmacy and prenatal‑care channels alongside high‑quality e‑commerce to capture both point‑of‑care purchase and pre‑purchase digital research behavior. Immediate action: pilot co‑promotions with prenatal clinics and targeted digital education campaigns.
- Hedge supply and build sourcing resilience. Identify single‑source dependencies for key actives and negotiate multi‑tier supplier agreements. Immediate action: conduct a supplier concentration risk assessment and model inventory buffers for 2026‑2027.
- Use acquisition and partnership selectively. Given moderate market concentration, acquisitions of niche formulators or partnerships with prenatal health platforms can accelerate market entry with manageable capital outlay. Immediate action: develop an M&A criteria matrix focused on regulatory dossiers, formulation IP, and channel access.
What PW Consulting’s full report delivers (practical, transaction‑grade tools)
The complete report is designed as a tactical playbook for B2C and B2B leaders. Key deliverables include:
- Proprietary market model and scenario forecasts (2026–2032) with sensitivity testing for disease‑outbreak shocks, regulatory changes, and channel shifts.
- Competitive benchmarking dashboards covering product portfolios, claims, pricing bands, and route‑to‑market strategies—presented for major competitors and regional leaders.
- Go‑to‑market playbooks for launching pregnancy‑targeted formulations across channel archetypes, including step‑by‑step marketing and regulatory timelines.
- R&D prioritization matrices and cost‑benefit analyses for formulation options (including clinical evidence investment recommendations and timelines for claim substantiation).
- Supply chain risk maps and mitigation strategies, including supplier scorecards and inventory posture scenarios aligned to 2026 purchasing cycles.
- M&A screening models tailored to this segment—quickly flagging targets that provide regulatory dossiers, differentiated formulations, or superior channel access.
We have intentionally withheld the detailed segmentation tables, country‑level opportunity maps, and full competitor revenue splits in this preview. Those granular insights, which form the core of decision‑grade intelligence for 2026 planning, are accessible in the full paid report and interactive data package.
Final assessment: why 2026 is a pivotal execution year
The convergence of clearer regulatory guidance, shifting prenatal consumer expectations, and favorable market growth dynamics makes 2026 a pivotal year for companies that want to convert strategic intent into tangible share gains. The market’s mid‑single‑digit CAGR and moderate concentration profile create a unique window where both established players and well‑capitalized challengers can achieve outsized returns from targeted investments in safety, formulation, and channel credibility.
For executive teams, the core decision is not whether to participate; it is how to allocate finite resources—between regulatory certification, formulation development, channel partnerships, and M&A—to build a credible, trust‑based franchise for pregnant consumers. Our full report supplies the playbooks, models, and competitor intelligence to convert those strategic choices into 2026 operational plans.
How to access the full intelligence
PW Consulting offers customized briefings and packaged intelligence subscriptions for executives and investment teams preparing 2026 budgets. To obtain the full Worldwide Mosquito Repellent Water For Pregnant Women Market report, including interactive datasets and competitor scorecards, please visit our research portal or contact our client services team for a tailored walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Mosquito Repellent Water For Pregnant Women Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Indirect Auto Finance Market Poised to Reach USD 474.0 Billion by 2032
By pmarketresearch, 2026-08-12
Indirect Auto Finance Market — 2026 Strategic Outlook
PW Consulting’s new Indirect Auto Finance Market report provides a focused, decision-grade view for executives preparing 2026 strategies. Built on rigorous historical analysis and forward-looking scenario modeling, the study distills the macro trajectory, competitive dynamics, regulatory inflection points, and practical playbooks that lenders, OEM captives, dealers, and fintech partners will need to navigate accelerating complexity in dealer-originated consumer vehicle finance.
Public Safety Dispatch Consoles Market
Executive snapshot
The indirect auto finance ecosystem has entered a renewed growth phase after a period of volatility. Our model shows the market expanding from approximately USD 168.45 Billion in 2020 to roughly USD 298.5 Billion in 2025, with a base-year profile calibrated to 2025 financials. Looking forward, the market is projected to compound at an annualized rate of 6.85% across the 2026–2032 forecast window, reaching an estimated USD 474.0 Billion by 2032 under the central scenario. These headline metrics frame the strategic choices facing market participants in 2026: scale, capital sourcing, credit appetite, and digital distribution will determine winners and laggards.
Avocado Butter Market
Why this report matters for 2026 decision cycles
-
Timing: Boards and C-suite teams setting budgets and product roadmaps for 2026 must align capital plans with an industry that is both growing and re-pricing risk. Our report translates macro growth into actionable pathways for origination, securitization, and capital deployment.
Luxury Home Audio Market -
Regulatory shift-readiness: With material regulatory activity affecting how nonbank originators are defined and supervised, institutions must be ready to redesign compliance and reporting functions. The report offers scenario-driven impact assessments to prioritize one- and two-year remediation steps.
-
Dealer-channel economics: Since the vast majority of auto loans continue to be originated via dealer channels, optimizing dealer-lender bilateral economics—without sacrificing credit performance—will be a core lever. The report supplies a modular toolkit for reconfiguring dealer incentives, repricing mechanisms, and inventory funding strategies.
-
Competitive positioning: A rising share of dealer-originated volume is shifting toward banks and non-captive lenders. The report maps competitive vectors for captives, banks, and independents and provides playbooks to defend or accelerate market share.
What’s inside: practical, implementable content
This is not a brochure—our research is purpose-built to put plans into motion. Key deliverables include:
-
Validated market sizing and near-term forecasts (2026–2032) with sensitivity cases for demand shocks, rate movements, and affordability stress.
-
Scenario playbooks: three calibrated scenarios (central, downside, upside) with quantified impacts on originations, loss rates, and funding needs to inform capital planning and stress testing.
-
Operational playbooks for dealer-originated flows: step-by-step approaches for improving conversion, reducing charge-offs, and shortening time-to-fund while maintaining compliance.
-
Regulatory impact matrix and remediation roadmap: prioritized actions to respond to changing definitions of “larger participants,” disclosure expectations, and fair lending interpretations.
-
Product and pricing playbooks: modular templates for rate-card design, risk-based pricing governance, and dealer compensation structures aligned with portfolio objectives.
-
Capital and funding strategies: decision frameworks for whole-loan sales, securitization tranches, warehouse lines, and bilateral funding to optimize cost of capital under different originations mixes.
-
Technology & data roadmaps: recommended investments in decisioning engines, dealer portals, and performance analytics to compress loss cycles and uplift throughput.
-
Competitive intelligence appendices: curated profiles and strategic positioning assessments of principal active players in the indirect channel.
Competitive landscape — who matters and why
The indirect auto finance space is meaningfully concentrated, but still offers room for disruption. The top three providers account for a substantial share of market volume, and the top five consolidate over half of all activity—an important contextual fact when setting share targets or evaluating M&A. Market concentration creates advantages in scale for distribution, capital access, and dealer reach, while also leaving white space for specialized providers and digital challengers to capture niche or underserved segments.
We profile the strategic orientations of core market participants to help clients benchmark positioning:
-
Ally Financial — a leading non-captive lender that leverages broad dealer networks and depth in retail installment and floorplan financing. Their scale in dealer relationships and treasury functions provides a template for integrated dealer financing strategies.
-
Capital One Auto Finance — bank-affiliated, emphasizing competitive rates and digital approval experiences. Their model underscores how digital conditional-approval frameworks shorten the buyer journey and increase cross-sell.
-
Toyota Financial Services, GM Financial, Ford Motor Credit, American Honda Finance — captive finance arms that use brand-aligned product bundles, lease options, and loyalty-focused underwriting to preserve OEM sales economics. Captives remain pivotal for OEM go-to-market control and price elasticity management.
-
Chase Auto Finance and Wells Fargo Auto — large-bank lender profiles that combine dealer distribution with balance-sheet scale and sophisticated funding programs.
-
Westlake Financial Services — an independent specialist that demonstrates how underwriting specialization and dealer-focused servicing can profitably address higher-risk segments underserved by prime lenders.
Recent market intelligence points to structural movement: independent analyses published in early 2026 indicate banks and non-captive lenders are gaining share in dealer-originated volume, and dealer-related finance debt has shown double-digit year-over-year growth in certain channels. For strategy teams, this underlines two imperatives—first, sharpen the distributor value proposition; second, revisit capital and risk-allocation frameworks to monetize growing dealer pipelines.
Regulation and macro dynamics that will shape 2026 outcomes
The policy and macro backdrop is rapidly evolving and must be integral to any 2026 plan. Highlights from our Dynamics analysis include:
-
Supervisory redefinition risk: Regulatory attention on thresholds for “larger nonbank auto finance participants” creates potential new compliance and reporting obligations for firms crossing originations thresholds. This is already influencing originator behavior when sizing dealer relationships and balance-sheet deployments.
-
Fair-lending interpretation changes: A notable policy development clarified the scope of disparate impact claims under ECOA in late 2025, altering litigation and supervision risk profiles for indirect channels where dealer markup and discretion are present.
-
Demand sensitivity: Market intelligence suggests a modest near-term moderation in originations due to affordability pressures—some forecasts point to a small downtick in 2026 origination volumes. Our scenarios quantify the impact on revenue, loss ratios, and capital needs so leaders can stress-test budgets.
-
Dealer origination dominance: Independent research continues to validate that the majority of auto loans are dealer-originated and subsequently placed with lenders, reinforcing the strategic importance of dealer experience management and reseller economics.
Strategic imperatives for market participants in 2026
Based on our integrated market, competitive, and regulatory analysis, PW Consulting recommends four priority moves for executives setting 2026 agendas:
-
Recalibrate origination footprint: Actively manage dealer relationships and channel incentives to optimize mix and preserve access to high-conversion partners. Consider selective expansion into underserved dealer cohorts where pricing power can be sustained.
-
De-risk through capital architecture: Diversify funding sources and prepare contingency securitization pathways to insulate originations from short-term liquidity stress. Capital planning should be scenario-driven and integrated with product/design decisions.
-
Hardwire regulatory readiness: Run targeted gap analyses against likely supervisory thresholds and fair-lending controls; prioritize remediations that reduce operational friction without materially sacrificing revenue.
-
Accelerate digital dealer integration: Invest in decisioning engines, real-time funding, and dealer UX to compress cycle times, reduce fallout, and limit dealer discretion in markup—thereby improving credit outcomes and reducing supervisory attention.
How this report is structured to support execution
Every chapter of the report is aligned to execution. Market-sizing and forecasting modules feed into the capital and stress-test appendices; competitive landscaping includes actionable diagnostics and countermeasures; regulatory assessments are prioritized by likelihood and business impact, with concrete implementation timelines. The result is a concise, prioritized roadmap for 90-, 180-, and 365-day actions that managers can fold into operating plans.
Next steps
For teams preparing 2026 budgets, product launches, or dealer-partner strategies, this report functions as both an early-warning system and an operations manual. PW Consulting’s analysts are available to run customized slices of the model—tailoring scenarios to specific origination mixes, funding structures, and regulatory exposures—so firms can convert strategic clarity into measurable actions.
To access the full set of forecasts, scenario outputs, and implementation playbooks, request the complete Indirect Auto Finance Market report on our website. The executive summary in this release previews the strategic logic and highlights the high-level forecasts; the full report contains the granular decision-support models and step-by-step playbooks necessary to operationalize a winning 2026 strategy.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ox Bezoars (Cow Bezoars) Market Reaches USD 1,288.6 Million in 2025, Set to Expand at a 9.0% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Ox Bezoars (Cow Bezoars) Market: Strategic Imperatives for 2026 — PW Consulting Exclusive Preview
PW Consulting today releases an executive preview of our forthcoming Worldwide Ox Bezoars (Cow Bezoars) Market report. As the industry transitions from traditional supply chains toward biotechnological sourcing and tighter regulatory oversight, this preview outlines the strategic value the full report will deliver to boardrooms and investor committees preparing decisions in 2026.
Worldwide Mirrorless Cameras Market
Why this market matters in 2026
Ox bezoars occupy a unique intersection between centuries-old Traditional Chinese Medicine (TCM) practice and modern pharmaceutical interest. Over the last half-decade the global market has expanded materially. Using 2025 as our analytical base year, PW Consulting’s modeling shows sustained growth driven by demand diversification, product innovation, and supply-side evolution. Our base-to-forecast work projects a compound annual growth rate (CAGR) of approximately 9.0% across the 2026–2032 forecast window, with the industry more than doubling in total revenue over the longer term under our central case.
Worldwide 3D Design Software Market
For decision-makers in 2026, this dynamic presents a set of clear choices: pursue scale via upstream supply integration, invest in in-vitro and synthetic alternatives to address sustainability and traceability concerns, or target premiumization and clinical research partnerships that can unlock higher margin channels. Each option carries distinct operational, regulatory and capital implications — and our full report translates those implications into executable plans.
Worldwide Solid End Mills Market
Snapshot of market structure and concentration
The ox bezoar ecosystem is neither purely fragmented nor tightly monopolized. Market concentration metrics indicate a moderate level of aggregation at the top: the three largest participants account for a substantial portion of revenues, while the top five increase that share meaningfully. For strategists, this profile signals an industry where scale matters, but nimble entrants and differentiated producers still have room to shape niches.
Implication: incumbents can protect margins through scale and established routes-to-market, while challengers can win by addressing structural weaknesses — quality assurance, traceability, or scalable cultivated supply.
Regulatory and sustainability dynamics shaping 2026 strategy
- Regulatory recognition within TCM frameworks: Ox bezoars are classified as traditional Chinese medicine materials under national pharmacopeias, bringing a baseline requirement for authentication and quality-control protocols for pharmaceutical or medical use. Buyers and manufacturers must build compliance programs that meet these specific pharmacopoeial requirements.
- Western regulatory stance: Major regulatory agencies such as the FDA and EMA currently do not recognize ox bezoars as approved pharmaceuticals. In many markets they remain herbal or supplement ingredients without a standardized Western drug status. This restricts certain commercialization pathways but also creates an opportunity for firms investing in clinical substantiation to achieve first-mover regulatory advantage.
- Export and conservation constraints: Exports of cattle-derived materials face international conservation-related regulation, including coverage under multilateral agreements that aim to prevent overexploitation. Exporters, traders, and downstream processors must weave compliance into supply-chain design to avoid trade interruptions.
Collectively, these dynamics mean that 2026 strategic plans must integrate regulatory monitoring, traceability systems, and scenario-based compliance playbooks as operational fundamentals — not afterthoughts.
Key market drivers and risk vectors
- Demand-side diversification: Traditional medicinal use continues to underpin demand, but modern pharmaceuticals and laboratory research are emerging as higher-margin and higher-growth end markets. Strategic investors should map adjacent pharmaceutical opportunities that require clinical data and tighter quality controls.
- Supply-side innovation: In-vitro cultivation and biofabrication technologies are moving from pilot to commercial scale. These approaches promise to mitigate scarcity, reduce ecological pressure, and offer consistent quality — however, scale-up economics and regulatory acceptance remain gating factors.
- Traceability and authentication: Quality assurance technologies — from DNA barcoding to spectroscopy-driven fingerprinting — are rapidly becoming de facto requirements for premium buyers and exporters. Firms that deploy robust QA+traceability systems can command price premia and reduce transaction friction.
- Price and supply volatility: Traditional supply is subject to livestock cycles, regional export controls, and seasonal availability. Buyers should embed hedging strategies and diversified sourcing to protect margins.
- Reputational and conservation risk: Overharvesting concerns attract scrutiny from regulators, NGOs and consumers. Brands must proactively demonstrate sustainable sourcing or transition plans to avoid reputational damage.
What PW Consulting’s full report delivers (practical, decision-grade content)
Our full Worldwide Ox Bezoars Market report is designed for executives making capital allocation, M&A, product development, or market-entry decisions in 2026. It goes beyond forecast tables to deliver an operational playbook. Highlights include:
- Scenario-based revenue and margin models calibrated to 2026 planning horizons (base, upside, downside), with sensitivity drivers and stochastic risk overlays.
- Supply-chain risk matrix mapping geographic sourcing nodes, export control implications, and mitigation levers (vertical integration, diversification, inventory strategy).
- Go-to-market playbooks for three archetype entrants: incumbent producer, biotech cultivator, and specialty pharmaceutical partner — each with recommended timelines, required CAPEX, and go/no-go triggers.
- Regulatory roadmap and compliance checklist for major export/import jurisdictions, including authentication and quality standard templates aligned with pharmacopeial requirements.
- Commercial benchmarks for pricing tiers, contract structures, and premiumization levers — framed to help procurement teams negotiate durable supplier agreements.
- Technology assessment of cultivated and synthetic pathways, including TRL (technology readiness level), scale-up challenges, and partner ecosystems for manufacturing and IP licensing.
- M&A playbook and valuation heuristics tailored to this market’s concentration profile — how to size synergies, identify bolt-ons, and evaluate roll-up strategies in a moderately concentrated market.
- Executive dashboards and KPI sets — designed for monthly and quarterly board reporting to track progress against 2026 strategic initiatives.
Competitive implications and recommended 2026 moves
While we withhold specific segment-level disclosures in this preview, the structural insights point to a small set of high-impact actions that will separate winners from laggards in 2026:
- Invest in traceable, certified supply: Firms securing authenticated supply chains (including cultivated sources where feasible) will reduce regulatory friction and create defensible price positioning.
- Pursue selective clinical validation: For participants aiming at modern pharmaceutical channels, targeted clinical programs — even small, rigorous studies — can convert TCM demand into regulated pharmaceutical opportunity.
- Partner for scale: New entrants should consider strategic partnerships with established distributors or contract manufacturers to accelerate market access while deferring heavy CAPEX.
- Hedge resource risk: Procurement strategies that include inventory optimization, multi-source contracts, and alternative-material R&D will protect margins in the face of export controls or supply shocks.
- Prepare for premiumization: Product differentiation through certified sourcing, GMP-compliant processing, and clinical backing can create higher-margin product tiers that insulate against commodity price compression.
Strategic value to 2026 corporate planning
For corporate planners, the report’s most immediate value is actionable clarity. The market’s projected growth trajectory and concentration characteristics enable realistic capacity and capex planning; the regulatory overlays determine compliance-driven timelines; and the technology outlook clarifies R&D roadmaps. Combined, these elements let boards answer three priority 2026 questions with evidence-based confidence:
- Should we vertically integrate supply or source from certified partners?
- Where do we allocate R&D dollars between cultivated/synthetic pathways and clinical validation for higher-margin channels?
- Which M&A targets or strategic alliances offer the most accretive path to secure supply and distribution?
What this preview does — and does not — disclose
This preview is deliberately calibrated as a strategic teaser: we provide market-scale context, growth dynamics, and prescriptive frameworks to demonstrate the report’s value for 2026 decision-making. To preserve the integrity of our client-grade intelligence and to encourage direct engagement, we do not disclose detailed subsegment or region/application-level breakdowns in this release. Those granulated data, company profiles, and price curves are available in the full report.
Next steps — where to get the complete intelligence
PW Consulting’s full Worldwide Ox Bezoars (Cow Bezoars) Market report contains the granular segmentation, supplier and product-level benchmarks, and downloadable decision-support tools referenced above. For procurement teams, corporate strategists, private equity investors and regulatory managers preparing 2026 plans, the full report converts industry signals into executable programs.
Reach out to PW Consulting to request the detailed report package, including our scenario models and an executive briefing tailored to your organization’s strategic posture.
About PW Consulting
PW Consulting is a global strategy firm advising CEOs and boards across specialty natural products, pharmaceutical adjacent markets, and biofabrication sectors. Our advisory combines market forecasting, regulatory intelligence and transaction support to help clients convert emerging-market growth into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Ox Bezoars (Cow Bezoars) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Smart Solar Urban Equipment Market to Expand at a 15.02% CAGR, Powering Global Urban Sustainability
By pmarketresearch, 2026-08-12
Worldwide Smart Solar Urban Equipment Market — Strategic Imperatives for 2026
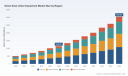
PW Consulting’s new market study on Worldwide Smart Solar Urban Equipment distills seven years of historical observation (2020–2025) and a forward-looking forecast (2026–2032) into an actionable intelligence pack for executives, investors, city planners, and systems integrators preparing strategy in 2026. The market has matured from an early commercial phase into a scale-up opportunity: our base-year assessment shows industry revenue at USD 1,142.8 Million in 2025 and a near-term projection of USD 1,342.9 Million in 2026, with a 2026–2032 compound annual growth rate (CAGR) of 15.02% that takes the market to roughly USD 3,043.7 Million by 2032. That macro trajectory changes how boards frame capital allocation, partnership choices, and pilot-to-scale timelines in 2026 — and our report is designed to convert those high-level signals into executable decisions.
Worldwide Moving Software Market
Why the timing matters: macro signals shaping 2026 choices
-
Demand inflection. Historic growth through 2025 demonstrates clear momentum for smart solar furnishings, off-grid street lighting, kiosks and integrated waste/charging networks. The transition from one-off pilots to portfolio procurement is underway, meaning 2026 is the window when pilots must demonstrate repeatable unit economics if vendors expect pipeline acceleration.
Smart Network Managed Switches Market -
Unit-cost and supply drivers. Utility-scale PV installed cost benchmarks and module spot pricing continue to ripple into product cost models. Recent utility-scale averages (reported by LBNL) and module spot price differentials between global and U.S. markets highlight persistent cost arbitrage and local-content implications that buyers and manufacturers must model into 2026 procurement strategies.
Worldwide Source Code Management Software Market -
Policy and trade dynamics. Tariff episodes and rapid global PV additions — with concentration in a handful of manufacturing geographies — create procurement and risk-management priorities for manufacturers and municipal buyers. Targeted incentive programs at state and local levels provide near-term co-funding windows that can materially improve project IRRs for 2026 deployments.
-
Market structure. Measured concentration in this market remains low-to-moderate: the top three and top five supplier groups account for a modest share of total market revenue, leaving room for regional champions and niche platform players to scale rapidly through services, integration, and performance contracts in 2026.
What the report delivers — practical modules for operational strategy
-
Proprietary market-sizing and demand model: a transparent methodology with scenario outputs (conservative, base, upside) for 2026–2032 to help finance teams stress-test capex and OPEX assumptions.
-
Buyer and procurement playbooks: step-by-step RFQ templates, performance-based contract clauses, warranty and service-level schedules, and procurement evaluation rubrics tailored to municipal and commercial buyers.
-
Technology and product taxonomy: a practical decision matrix that maps solar urban equipment types to service bundles (lighting, charging, connectivity, waste management) and anticipated maintenance profiles.
-
TCO and pricing sensitivity tool: inputs reflect real-world component cost trends and regional pricing levers so CFOs can model CAPEX vs. OpEx trade-offs for 2026 buying cycles.
-
Vendor due-diligence pack: scorecards, reference-check templates, and integration risk checklists for shortlisting and piloting suppliers.
-
Commercialization playbooks: channel strategies, subscription/lighting-as-a-service (LaaS) models, and municipal partnership frameworks to accelerate revenue conversion.
-
Regulatory & incentive compendium: an up-to-date library of tariffs, grants, and local funding instruments that create immediate arbitrage opportunities for projects commencing in 2026.
-
Case studies and pilot blueprints: deconstructed deployments with measured KPIs on uptime, energy yield, and citizen engagement to reduce time-to-scale risk.
Competitive landscape — who to watch and how to position
The report profiles leading technology suppliers and integrators active in smart solar urban equipment. Key archetypes include platform-lean providers that combine IoT, connectivity and service contracts; high-efficacy off-grid lighting specialists; modular urban-furniture manufacturers; and smart waste and compaction system providers. Representative companies discussed in the report illustrate these archetypes and their go-to-market approaches — from firms emphasizing full-stack city deployments and subscription-based lighting to suppliers focused on high-performance, rapid-deploy systems for events and infrastructure.
-
Platform-and-services players are differentiating through integrated IoT, remote asset management and multi-service revenue streams (connectivity, environmental sensing, security). These suppliers are positioned to win long-term service contracts in municipalities seeking single-vendor responsibility.
-
Product-specialist vendors are competing on efficiency, reliability and ease of deployment: high-lumen LEDs, robust energy storage and designs supporting extended autonomy reduce O&M friction and appeal to departments of transportation and parks authorities where trenching and mains connections are cost-prohibitive.
-
Niche system suppliers — for example in solar-powered waste compactors — are gaining traction by addressing specific urban pain points and integrating telemetry that optimizes collection routes, creating defensible value-propositions for cities with constrained waste budgets.
Recent vendor activity underlines these dynamics: product catalog updates emphasizing deployability and event-grade performance; high-visibility installations approaching completion; and thought leadership publications shaping municipal procurement priorities. These developments provide clues about which competitors are moving towards platformization versus product specialization — a critical distinction when designing partnerships or M&A screens in 2026.
Key risk vectors for 2026 and recommended mitigations
-
Supply-cost volatility: module and component price differentials across markets can erode margins. Mitigation: adopt multi-sourcing, commit to forward purchase agreements, and explore localized assembly to capture incentive regimes and reduce tariff exposure.
-
Trade and regulatory shifts: tariffs and compliance regimes can change supplier economics rapidly. Mitigation: include contractual pass-through clauses and maintain inventory buffers for critical components.
-
Procurement inertia and integration risk: municipalities often require extended evaluation cycles and proof-of-concept outcomes. Mitigation: design 90–180 day pilots with predefined KPIs, performance-based payments, and standardized interface specifications for rapid replication.
-
Aftermarket and O&M surprises: field reliability will determine long-term TCO. Mitigation: instrument systems with remote monitoring from day one and price service-level agreements to align incentives on uptime.
How Boards and strategic teams should use this report in 2026
-
Investor diligence and portfolio allocation: use scenario outputs and vendor scorecards to size addressable markets and set realistic pace for Series A/B capex deployment.
-
OEM and integrator growth planning: adopt the go-to-market playbooks to pick initial verticals where payback is fastest, then scale via channel partnerships supported by our procurement templates.
-
City and municipal strategy: leverage the procurement and pilot blueprints to unlock local incentive co-funding windows and structure performance-based contracts that limit political and budget risk.
-
M&A and partnership screening: apply our consolidation scenarios and concentration metrics to identify attractive targets that fill capability or geographic gaps while keeping integration risk quantifiable.
Why PW Consulting’s study is different
This report couples a transparent, reproducible market model (historical 2020–2025 calibration and 2026–2032 scenario outputs) with hands-on procurement and commercialization tools. We combine vendor-level diligence, a curated incentive and regulatory tracker, and a practical TCO engine that embeds recent component-cost intelligence and trade exposures. Importantly, our approach is deliberately practitioner-focused: instead of publishing raw, uncontextualized split tables in this announcement, we present synthesized guidance and diagnostic tools in the full report that convert market-level trends into immediate operational steps for 2026.
Next steps and how to access the intelligence you need
Executives and procurement leads preparing 2026 strategies should treat this report as the playbook for converting market growth into repeatable revenue or reliable public services. To preserve competitive value for clients and purchasers, we have intentionally withheld the detailed segmentation tables from this press release — the full vendor scorecards, regional and application split matrices, and financial-model workbooks are included in the complete report and online portal.
Contact PW Consulting or visit our report landing page to request the executive summary, schedule a briefing, or license the dataset and scenario tools. For teams with immediate pilot or procurement decisions in 2026, our analysts are available for rapid workshops to map the report’s tools to your specific operating environment and to design a 90–180 day evidence plan that de-risks scale-up.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Solar Urban Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Child‑Resistant Blister Lidding Film Market Poised for Growth at a 6.94% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Child-Resistant Blister Lidding Film Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Child-Resistant Blister Lidding Film Market provides a forward-looking, operationally focused briefing designed to inform boardroom decisions in 2026. Anchored on a base year of 2025, the study synthesizes five years of historical performance (2020–2025) with a detailed forecast through 2032. The market grew from a subdued base in 2020 to an estimated USD 975.0 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.94% through the forecast horizon, reaching roughly USD 1,559.1 million by 2032. This briefing distils the report’s most consequential insights — enough to act on now — while reserving the full segmentation tables and supplier scorecards for the full report.
Vessel Diesel Particulate Filters Market
Why this report matters for 2026 strategic planning
-
Timing-sensitive capital allocation: With mid-single-digit CAGR and accelerating demand pockets, decisions on capacity expansion, conversion investments, and acquisition targets in 2026 will determine market share capture through the next cycle.
Cell Identification and Characterization Testing Services Market -
Regulatory risk and compliance as business risk: Child-resistant lidding is governed by high-stakes protocols whose compliance timelines and testing regimes directly affect product time-to-market and commercialization costs.
Medical Soft Skin Adhesive Market -
Commercial differentiation: Innovations in recyclability, senior-friendly ergonomics, and barrier performance are converging with customer and regulator expectations. Firms that translate these features into validated value propositions will command price premia.
-
Procurement and sourcing resilience: Feedstock volatility and logistics tightness will be pivotal to margin preservation in 2026. The report quantifies exposure by feedstock and proposes hedging and supplier-diversification playbooks.
Key data-driven takeaways
-
Structured growth with pockets of acceleration: The market’s projected growth to about USD 1.56 billion by 2032 (CAGR ~6.94%) is neither uniform nor random — it reflects structural drivers such as an aging population mix, steady pharmaceutical demand (Rx and OTC), and rising regulatory enforcement globally.
-
Regulation is a material growth lever and constraint: Child-resistant packaging must meet protocol thresholds such as the U.S. CPSC Protocol 1700.20 (designed to limit a child’s ability to access contents) and established adult-use durability standards like EN 14375, which specifies rigorous adult usability criteria. These standards raise the technical bar for product design, testing, and validation cycles.
-
Raw material dynamics matter more than ever: Primary substrates remain aluminum foil laminated with PET or PVC at typical foil thicknesses of roughly 9–20 microns. Recent commodity data point to aluminum trading near levels that materially alter unit economics (reference: aluminum price data as reported in early-2026 commodity summaries). Procurement strategy, contract tenor, and opportunistic hedging will be decisive in 2026.
-
Policy and taxation introduce asymmetric cost pressure: Macro policies such as the UK Plastic Packaging Tax (noted at c. £217.85 per tonne for packaging with limited recycled content) and EU mandates for recycled content in plastics through 2030 are already changing supplier product roadmaps and capital plans.
-
Margin bifurcation driven by sustainability and function: Products that successfully combine high-barrier performance with mono-material recyclability or meaningful recycled content are beginning to capture higher commercial traction. Conversely, legacy multi-layer laminates without clear end-of-life pathways are increasingly exposed to regulatory and commercial discounting.
Competitive landscape — what incumbents and challengers are doing
The competitive field comprises global converters, specialty film houses, and regional specialists. While the market is not a pure commodity, it exhibits moderate concentration with a handful of established suppliers exerting outsized influence on standards, certification pathways, and distribution channels.
-
Amcor plc (Melbourne, Australia) — A large integrated supplier leveraging global scale to commercialize recyclable child-resistant lidding films. Recent product launches indicate a strategic focus on sustainable formulations that meet pharmaceutical barrier requirements while reducing lifecycle impact.
-
Constantia Flexibles (Vienna, Austria) — Known for high-barrier aluminum lidding foils and multi-layer films, actively showcasing innovations at key trade events and maintaining deep relationships with pharma packagers seeking tested, high-integrity solutions.
-
Tekni-Plex (Wayne, PA, USA) — Focuses on thermoformable lidding and senior-friendly peel mechanics; certification updates underscore attention to regulatory compliance and user-centric design tradeoffs.
-
Winpak Ltd. (Winnipeg, Canada) — Emphasizes high puncture resistance and medical-grade performance, which appeals to markets with heavy sterility and handling demands.
-
Alpine Packaging, ProAmpac, Hood Packaging, Sonoco Products Company — These and other regional players specialize in customization, speed-to-market, and niche features such as peel-reseal mechanisms, recyclable laminates, and tailored barrier properties.
Collectively, leading suppliers are differentiating along three vectors: (1) regulatory-certified child-resistance and adult-usability balance, (2) sustainability credentials and recyclability, and (3) service and supply-chain reliability. The most successful players in 2026 will be those that can simultaneously demonstrate certified performance and an economically viable path to lower environmental impact.
Report content — practical, actionable modules
The full PW Consulting report is structured for execution. Key, plug-and-play deliverables included are:
-
Market forecast engine with scenario overlays (base, regulatory-accelerated, and substitution-accelerated scenarios) to stress-test investments and commercial plans.
-
Regulatory compliance matrix that maps global standards (including CPSC and EN frameworks), test pass/fail implications, certification timelines, and recommended pre-submission test plans to accelerate approvals.
-
Supplier scorecards and plant-capacity mapping derived from primary interviews — enabling rapid shortlisting for procurement, trial runs, and dual-sourcing strategies.
-
Raw-material exposure dashboard that models aluminum price sensitivity, feedstock substitution pathways (e.g., PET monomaterials), and tax/policy impacts such as plastic taxes and recycled-content mandates.
-
Commercial playbooks for segmentation, pricing sensitivity analyses, and channel strategies for pharma OEMs, contract packagers, and OTC brands.
-
M&A and JV playbook with target typologies, valuation yardsticks, and integration checklists focused on capability, regulatory foothold, and geographic access.
-
Operational KPIs and pilot templates to de-risk time-to-market for new lid formulations, including sample test protocols aligned with major regulatory methods.
2026 roadmap — operational priorities for executives
-
Prioritize validated sustainable formats: Begin 2026 with a portfolio triage that isolates SKUs vulnerable to near-term policy headwinds (e.g., single-use multi-layer laminates without clear recycling pathways) and accelerate pilots for recyclable or recycled-content alternatives.
-
Lock in raw-material strategy: Negotiate multi-year arrangements or financial hedges for aluminum and critical film substrates; consider alternate substrate trials where barrier and test compliance permit.
-
Invest in testing and certification front-loading: Secure lab capacity and pre-certification runs to compress approval lead times. Passing recognized protocols (CPSC, EN) on first submission yields meaningful commercial advantage.
-
Design for the end-user: Balance child-resistance with senior usability — products that fail adult-usability criteria risk commercial rejection even if technically child-resistant.
-
Operationalize supplier risk management: Establish dual-sourcing for critical SKUs, map logistics pinch-points, and maintain buffer strategies calibrated to product-criticality.
-
Scan for inorganic moves: 2026 is likely to see opportunistic M&A and strategic partnerships focused on proprietary chemistries, recyclable laminate technologies, and regional capacity expansion — prepare acquisition filters and integration plans now.
How PW Consulting supports execution
PW Consulting delivers not just a market snapshot but a practitioner’s toolkit: bespoke scenario modeling, due-diligence support for transactions, sourcing optimization, and tailored regulatory roadmaps. Our engagement teams combine packaging engineers, regulatory specialists, and commercial strategists who translate the report’s insights into executable plans aligned with 2026 budgets and KPIs.
Next steps
This briefing offers a strategic overlay designed to accelerate 2026 decision-making. For access to the full dataset, including granular segmentation, supplier scorecards, plant-level capacity maps, and the scenario-ready forecast engine, consult the full Worldwide Child-Resistant Blister Lidding Film Market report. PW Consulting can provide an executive briefing and an implementation workshop to convert insights into a one-year operational plan that aligns with your capital and market priorities.
Contact PW Consulting to schedule a briefing and gain full access to the models and templates that will make 2026 a year of measurable advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Child Resistant Blister Lidding Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com