

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Alternate Light Sources Market to Grow from USD 470.83 Million in 2025 to USD 694.05 Million by 2032 at a 5.72% CAGR

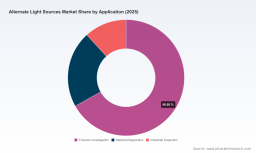
Worldwide Alternate Light Sources Market — Strategic Briefing for 2026
Executive summary
PW Consulting’s latest market intelligence on Worldwide Alternate Light Sources (ALS) synthesizes five years of historical dynamics and a seven‑year forward view to equip executives with the evidence-based perspective required for 2026 decisions. Our assessment shows a resilient market trajectory: a measured expansion from a mid‑hundreds million USD base in 2020 to a substantively larger market in 2025, with the forecast driving continued growth through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.72%. Competitive concentration is moderate — a handful of leaders command a meaningful share while an active middle tier and small specialists continue to innovate. This briefing highlights the strategic choices that will matter next year and where our full report delivers the operational detail that decision-makers will need.
Disposable Hospital Curtain Market
Market trajectory and what the headline numbers mean for 2026
-
Momentum: After recovering and expanding across 2020–2025, the ALS market is positioned for steady expansion in 2026 as forensic, medical, and industrial use cases normalize and invest in upgraded, wavelength‑agile tools.
Worldwide Pro Audio Market -
Predictability: The 5.72% CAGR built into our 2026–2032 forecast reflects a market that is not hyper‑volatile but is responsive to technology refresh cycles (LED and laser advances), procurement cadences in public safety and healthcare, and episodic large tender opportunities.
Worldwide Automated Storage and Retrieval Systems (ASRS) for Cold Storage Food Facility Market -
Concentration: Market concentration metrics indicate opportunity for both incumbents and challengers — established specialist vendors maintain leadership through brand, validated workflows and field‑proven kits, while nimble entrants compete on price, form factor, or niche capability (e.g., laser modules, ruggedized systems).
Drivers and constraints
-
Technical innovation: Ongoing miniaturization and improved spectral control in LED and laser platforms are increasing the effectiveness of field ALS units and expanding lab capabilities for luminescence and fluorescence applications.
-
Procurement patterns: Law enforcement and forensic laboratories are beginning to layer lifecycle-centric procurement (purchase, calibration, PPE, and training) into budgeting, increasing the value of bundled offers and managed‑service models.
-
Regulatory and standards influence: Definitions and use cases codified by NIST, inclusion of portable forensic light kits in the U.S. DHS Authorized Equipment List, and SWGDE guidance on documentation and safety are formalizing buyer requirements — raising the bar for compliance and training documentation offered by vendors.
-
Health and safety considerations: Shortwave UV remains effective for certain evidence detection but carries occupational risk; suppliers and buyers must prioritize PPE, user training, and clear safety specifications to avoid liability and ensure operational continuity.
Strategic implications for 2026 decisions
-
Product roadmap prioritization: Firms should accelerate investment in multi‑wavelength LED platforms with modular filters and ruggedized enclosures. Product roadmaps that prioritize spectral agility, battery efficiency, and simplified field operation will capture procurement mandates emphasizing ease of use and lifecycle cost.
-
Commercial models: Growing institutional buyers favor bundled solutions (device + filter + training + calibration). Vendors that can demonstrate a low‑total‑cost‑of‑ownership offering will outcompete unit‑price focused suppliers in public sector tenders.
-
M&A and partnership playbook: Given moderate concentration, there is room for acquisitive scale plays (to expand geographic reach or add complementary product lines) and bolt‑on purchases that fill capabilities — e.g., compact lasers, specialized filters, or software for evidence documentation.
-
Go‑to‑market focus: Sales teams should emphasize compliance credentials (DHS AEL alignment, SWGDE best practices) and outcomes (reduced false negatives, faster on‑scene processing). Proof points such as validated lab studies and documented field deployments will shorten procurement cycles.
-
Risk mitigation: Buyers and vendors must embed safety and training into commercial terms. Shortwave UV specifications in contracts should include manufacturer‑mandated PPE, training modules, and service plans to minimize operational and legal risk.
Competitive landscape — how to read vendor capabilities in 2026
The sector is populated by a mix of legacy forensic specialists, instrumentation houses, and small, highly focused manufacturers. Our vendor analysis in the full report profiles each major supplier against a consistent set of criteria: product breadth, spectral capability, ruggedization, certification/compliance, service footprint, and reference installations. Highlights for boardroom consideration:
-
Foster + Freeman (UK) — A long-standing innovator in high‑intensity LED forensic light sources. Their Crime‑lite family, spanning handheld to multi‑spectral laboratory systems and laser offerings, exemplifies a premium, lab‑validated approach. Strategic managers should view them as a reference for multi‑wavelength, high‑performance positioning.
-
Labino AB (Sweden) — Known for waterproof, user‑friendly ALS kits designed for rapid crime scene deployment. Recent catalog updates reinforce an approach favoring simplicity and field reliability — attributes that resonate with first responders and international buyers with ruggedization requirements.
-
Sirchie (USA) — A broad portfolio targeting law enforcement with compact, tactical ALS solutions and UV offerings. Their positioning aligns with procurement teams seeking cost‑effective, field‑ready options and packaged training materials.
-
HORIBA Scientific / SPEX Forensics (USA) — Brings laboratory instrumentation expertise to the ALS category with products tailored for forensic laboratories. Their emphasis on documentation and instrument performance is a differentiator for institutional lab purchases.
-
FoxFury (USA) — Specialist in rugged, cordless forensic lighting; their product set targets investigators who prioritize portability and power. Organizations with austere field requirements should evaluate FoxFury as a prime candidate.
-
Lynn Peavey Company & UltraLite ALS (USA) — Distributors and focused suppliers of portable forensic solutions. They play an important role in localization of service, supply chain resilience, and bundled forensic consumables.
Recent developments shaping 2026 dynamics
-
Product refreshes: In early 2025 vendors released incremental and next‑generation products — from updated ALS kit catalogs to new multi‑spectral units — signaling continued investment in both field and lab segments.
-
Standards and lists: Inclusion of portable ALS components in recognized equipment lists and the prominence of NIST and SWGDE guidance are raising buyer expectations for documentation, safety, and interoperability.
-
Technology diffusion: LED and laser technologies are moving from premium lab boxes deeper into handheld and ruggedized formats, compressing the time between lab innovation and field availability.
What PW Consulting’s full report delivers (practical, executable content)
Our market study is intentionally operational. For decision‑makers considering investment, procurement, product development or M&A in 2026, the full report contains:
-
Robust market sizing and validated forecast (2026–2032) with scenario analysis calibrated to procurement cycles and technology adoption curves.
-
Commercial playbooks for suppliers and buyers — tender templates, contract clauses covering safety and lifecycle support, and pricing strategy frameworks.
-
Vendor scorecards and a shortlist methodology that maps capability gaps to acquisition targets or partnership candidates without relying on raw price competition.
-
Use‑case matrices showing which ALS attributes matter most by operational profile (forensic scene, lab, medical diagnostics, industrial inspection), and sample procurement spec language that aligns with NIST/DHS/SWGDE expectations.
-
Implementation checklists for safety & training, product validation protocols, and a calibration/service benchmarking tool for post‑purchase maintenance planning.
-
Risk registers and sensitivity analyses addressing regulatory shifts, supply chain fragility, and rapid obsolescence in spectral control technologies.
How to act in 90–180 days
-
Buyers: Run a short pilot that tests multi‑wavelength field kits against existing workflows; require suppliers to supply safety and training packages as part of the pilot scope.
-
Vendors: Accelerate development of bundled commercial offers (device + training + service). Use pilot results to build case studies that speak to compliance and outcome metrics.
-
Investors / M&A teams: Prioritize targets that provide modular capabilities (spectral modules, laser add‑ons, digital documentation tools) or add depth to a regional service footprint.
Conclusion — the strategic value of this report for 2026
As agencies and institutions move beyond pandemic‑era procurement rhythms and focus on capability consolidation, ALS suppliers and buyers face a year in which clarity of product value, compliance credentials, and lifecycle economics will drive competitive outcomes. PW Consulting’s Worldwide Alternate Light Sources Market report is designed to be a decision accelerator: it validates market direction with quantitative forecasting, converts standards and regulatory signals into procurement and product requirements, and supplies the playbooks necessary for tactical execution in 2026.
Next step
For access to the full dataset, vendor scorecards, procurement templates and the scenario models that underpin our 2026 recommendations, please consult the complete report page. PW Consulting’s analysts are available to brief executive teams and to tailor the findings into a workshop or procurement readiness program.
For detailed analysis of this topic, please visit the official page: Worldwide Alternate Light Sources Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com