

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smart Solar Urban Equipment Market to Expand at a 15.02% CAGR, Powering Global Urban Sustainability

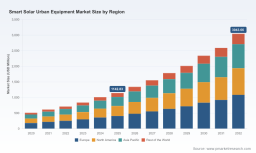
Worldwide Smart Solar Urban Equipment Market — Strategic Imperatives for 2026
PW Consulting’s new market study on Worldwide Smart Solar Urban Equipment distills seven years of historical observation (2020–2025) and a forward-looking forecast (2026–2032) into an actionable intelligence pack for executives, investors, city planners, and systems integrators preparing strategy in 2026. The market has matured from an early commercial phase into a scale-up opportunity: our base-year assessment shows industry revenue at USD 1,142.8 Million in 2025 and a near-term projection of USD 1,342.9 Million in 2026, with a 2026–2032 compound annual growth rate (CAGR) of 15.02% that takes the market to roughly USD 3,043.7 Million by 2032. That macro trajectory changes how boards frame capital allocation, partnership choices, and pilot-to-scale timelines in 2026 — and our report is designed to convert those high-level signals into executable decisions.
Worldwide Moving Software Market
Why the timing matters: macro signals shaping 2026 choices
-
Demand inflection. Historic growth through 2025 demonstrates clear momentum for smart solar furnishings, off-grid street lighting, kiosks and integrated waste/charging networks. The transition from one-off pilots to portfolio procurement is underway, meaning 2026 is the window when pilots must demonstrate repeatable unit economics if vendors expect pipeline acceleration.
Smart Network Managed Switches Market -
Unit-cost and supply drivers. Utility-scale PV installed cost benchmarks and module spot pricing continue to ripple into product cost models. Recent utility-scale averages (reported by LBNL) and module spot price differentials between global and U.S. markets highlight persistent cost arbitrage and local-content implications that buyers and manufacturers must model into 2026 procurement strategies.
Worldwide Source Code Management Software Market -
Policy and trade dynamics. Tariff episodes and rapid global PV additions — with concentration in a handful of manufacturing geographies — create procurement and risk-management priorities for manufacturers and municipal buyers. Targeted incentive programs at state and local levels provide near-term co-funding windows that can materially improve project IRRs for 2026 deployments.
-
Market structure. Measured concentration in this market remains low-to-moderate: the top three and top five supplier groups account for a modest share of total market revenue, leaving room for regional champions and niche platform players to scale rapidly through services, integration, and performance contracts in 2026.
What the report delivers — practical modules for operational strategy
-
Proprietary market-sizing and demand model: a transparent methodology with scenario outputs (conservative, base, upside) for 2026–2032 to help finance teams stress-test capex and OPEX assumptions.
-
Buyer and procurement playbooks: step-by-step RFQ templates, performance-based contract clauses, warranty and service-level schedules, and procurement evaluation rubrics tailored to municipal and commercial buyers.
-
Technology and product taxonomy: a practical decision matrix that maps solar urban equipment types to service bundles (lighting, charging, connectivity, waste management) and anticipated maintenance profiles.
-
TCO and pricing sensitivity tool: inputs reflect real-world component cost trends and regional pricing levers so CFOs can model CAPEX vs. OpEx trade-offs for 2026 buying cycles.
-
Vendor due-diligence pack: scorecards, reference-check templates, and integration risk checklists for shortlisting and piloting suppliers.
-
Commercialization playbooks: channel strategies, subscription/lighting-as-a-service (LaaS) models, and municipal partnership frameworks to accelerate revenue conversion.
-
Regulatory & incentive compendium: an up-to-date library of tariffs, grants, and local funding instruments that create immediate arbitrage opportunities for projects commencing in 2026.
-
Case studies and pilot blueprints: deconstructed deployments with measured KPIs on uptime, energy yield, and citizen engagement to reduce time-to-scale risk.
Competitive landscape — who to watch and how to position
The report profiles leading technology suppliers and integrators active in smart solar urban equipment. Key archetypes include platform-lean providers that combine IoT, connectivity and service contracts; high-efficacy off-grid lighting specialists; modular urban-furniture manufacturers; and smart waste and compaction system providers. Representative companies discussed in the report illustrate these archetypes and their go-to-market approaches — from firms emphasizing full-stack city deployments and subscription-based lighting to suppliers focused on high-performance, rapid-deploy systems for events and infrastructure.
-
Platform-and-services players are differentiating through integrated IoT, remote asset management and multi-service revenue streams (connectivity, environmental sensing, security). These suppliers are positioned to win long-term service contracts in municipalities seeking single-vendor responsibility.
-
Product-specialist vendors are competing on efficiency, reliability and ease of deployment: high-lumen LEDs, robust energy storage and designs supporting extended autonomy reduce O&M friction and appeal to departments of transportation and parks authorities where trenching and mains connections are cost-prohibitive.
-
Niche system suppliers — for example in solar-powered waste compactors — are gaining traction by addressing specific urban pain points and integrating telemetry that optimizes collection routes, creating defensible value-propositions for cities with constrained waste budgets.
Recent vendor activity underlines these dynamics: product catalog updates emphasizing deployability and event-grade performance; high-visibility installations approaching completion; and thought leadership publications shaping municipal procurement priorities. These developments provide clues about which competitors are moving towards platformization versus product specialization — a critical distinction when designing partnerships or M&A screens in 2026.
Key risk vectors for 2026 and recommended mitigations
-
Supply-cost volatility: module and component price differentials across markets can erode margins. Mitigation: adopt multi-sourcing, commit to forward purchase agreements, and explore localized assembly to capture incentive regimes and reduce tariff exposure.
-
Trade and regulatory shifts: tariffs and compliance regimes can change supplier economics rapidly. Mitigation: include contractual pass-through clauses and maintain inventory buffers for critical components.
-
Procurement inertia and integration risk: municipalities often require extended evaluation cycles and proof-of-concept outcomes. Mitigation: design 90–180 day pilots with predefined KPIs, performance-based payments, and standardized interface specifications for rapid replication.
-
Aftermarket and O&M surprises: field reliability will determine long-term TCO. Mitigation: instrument systems with remote monitoring from day one and price service-level agreements to align incentives on uptime.
How Boards and strategic teams should use this report in 2026
-
Investor diligence and portfolio allocation: use scenario outputs and vendor scorecards to size addressable markets and set realistic pace for Series A/B capex deployment.
-
OEM and integrator growth planning: adopt the go-to-market playbooks to pick initial verticals where payback is fastest, then scale via channel partnerships supported by our procurement templates.
-
City and municipal strategy: leverage the procurement and pilot blueprints to unlock local incentive co-funding windows and structure performance-based contracts that limit political and budget risk.
-
M&A and partnership screening: apply our consolidation scenarios and concentration metrics to identify attractive targets that fill capability or geographic gaps while keeping integration risk quantifiable.
Why PW Consulting’s study is different
This report couples a transparent, reproducible market model (historical 2020–2025 calibration and 2026–2032 scenario outputs) with hands-on procurement and commercialization tools. We combine vendor-level diligence, a curated incentive and regulatory tracker, and a practical TCO engine that embeds recent component-cost intelligence and trade exposures. Importantly, our approach is deliberately practitioner-focused: instead of publishing raw, uncontextualized split tables in this announcement, we present synthesized guidance and diagnostic tools in the full report that convert market-level trends into immediate operational steps for 2026.
Next steps and how to access the intelligence you need
Executives and procurement leads preparing 2026 strategies should treat this report as the playbook for converting market growth into repeatable revenue or reliable public services. To preserve competitive value for clients and purchasers, we have intentionally withheld the detailed segmentation tables from this press release — the full vendor scorecards, regional and application split matrices, and financial-model workbooks are included in the complete report and online portal.
Contact PW Consulting or visit our report landing page to request the executive summary, schedule a briefing, or license the dataset and scenario tools. For teams with immediate pilot or procurement decisions in 2026, our analysts are available for rapid workshops to map the report’s tools to your specific operating environment and to design a 90–180 day evidence plan that de-risks scale-up.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Solar Urban Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com