

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Reusable Food Wrap Market to Rise from USD 245.0 Million in 2025 to USD 397.3 Million by 2032 at a 7.15% CAGR

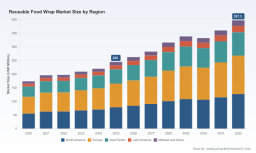
Worldwide Reusable Food Wrap Market: Strategic Imperatives for 2026 — A PW Consulting Outlook
Executive snapshot
As brands, manufacturers, and investors prepare their 2026 road maps, the reusable food wrap market presents a compelling mix of steady demand growth, regulatory tailwinds, and supply‑side complexity. Our latest PW Consulting report finds the global market expanding from roughly USD 173.5 million in 2020 to USD 245.0 million in 2025, with a forecast trajectory that anticipates continued expansion at a compound annual growth rate (CAGR) of 7.15% through the 2026–2032 window — reaching an estimated USD 397.3 million by 2032. These headline metrics frame a market that is maturing but still fragmented, where disciplined strategy can meaningfully move the needle on share and margin.
Solar Panel Recycling Management Market
Why this matters for 2026 decision‑makers
- Commercialization timing: A mid‑single digit CAGR masks pockets of accelerated adoption driven by policy shifts, retail assortment changes, and rising consumer interest in circular solutions. Companies that translate macro momentum into targeted GTM pilots in 2026 will be best positioned to scale in the second half of the decade.
- Regulatory acceleration: Emerging legislation in the United States — from statewide packaging mandates to single‑use restrictions — is already compressing runway for disposable alternatives and creating immediate demand avenues for reusable solutions. This dynamic reshapes procurement requirements for food service and retail buyers in the near term.
- Supply chain sensitivity: Raw material cost and availability are now first‑order considerations for product cost curves and margin planning. Volatility in beeswax pricing and diverse quality standards across sourcing geographies require active procurement strategies and scenario planning.
Data signals to watch — and act on
Several quantifiable indicators in our study have direct strategic implications for 2026 planning:
Worldwide Portable Flares Market
- Market scale and pace: The market’s progression from the mid‑hundreds of millions in 2020–2025 into the forecast period underscores sufficient consumer and commercial demand to justify investment in manufacturing scale, new SKUs, and channel expansion.
- Concentration and competitive structure: The sector remains relatively unconsolidated: the three‑firm and five‑firm concentration ratios indicate a market where incumbents coexist with numerous regional and niche players. That fragmentation creates M&A and partnership opportunities for companies aiming to build integrated platforms or secure distribution footholds.
- Raw material dynamics: Market intelligence shows transactional spikes and broad variance in beeswax pricing — for example, visible trades recorded at approximately USD 18.29/kg in late‑2025 contrasted with other reported average export price series. These differences reflect supply chain segmentation (spot trades vs. contract volumes) and imply that procurement sophistication — hedging, alternative raw materials, certification premiums — will directly influence cost competitiveness.
Regulatory context shaping demand in 2026
Policy measures are moving from aspirational goals toward enforceable standards. State‑level actions in the U.S. requiring recyclability/compostability of single‑use packaging and targeted bans on single‑use foodware are already influencing RFPs, buyer specifications, and retailer listings. For companies targeting commercial channels (food service, institutional procurement), compliance pathways and certification capabilities must be front‑and‑center in product development and sales messaging for 2026.
Worldwide Cherry Oil Market
Competitive landscape — practical insights
The market features a mixture of pioneering boutique brands, purpose‑led startups, and specialized manufacturers. Notable participants include established pioneers that have built brand equity around organic and certified supply chains, alongside large manufacturers offering OEM/ODM services with global compliance capabilities.
- Brands with strong storytelling and certification pedigree have an advantage in premium retail and direct‑to‑consumer channels. Their differentiation is rooted in material provenance, design, and lifestyle positioning.
- Manufacturer‑suppliers with scale and compliance credentials are winning institutional contracts and private‑label business, especially where price, minimums, and regulatory documentation matter.
- Across the value chain there is room for consolidation. Strategic buyers seeking rapid scale should evaluate bolt‑on acquisitions that bring manufacturing capacity, quality certifications, or distribution reach in key markets.
Profiles in our analysis include market pioneers known for organic, GOTS‑certified offerings; innovative zero‑waste brands building lifestyle portfolios; and major Asian manufacturers with LFGB/REACH/FDA capability that supply both branded and private‑label channels. The competitive map is a mosaic of brand equity, manufacturing competence, and channel intimacy.
What our full report delivers (practical, actionable content)
This research is designed as an operational toolkit for teams making 2026 commitments. Highlights include:
- Granular market sizing and a transparent forecasting model with scenario analysis and sensitivity testing to model material cost shocks and policy acceleration.
- Supply chain deep dives covering raw material markets, contract vs. spot dynamics, quality differentials, and a procurement playbook that outlines hedging, blended sourcing, and back‑to‑back contracts.
- Regulatory impact matrices mapping key jurisdictions to compliance actions and buyer requirements, enabling commercial teams to prioritize target accounts and tailor qualification documents.
- Channel profitability models by sales route (retail, DTC, food service, private label) with illustrative unit economics and SKU rationalization guidance.
- Competitive benchmarking of leading brands and manufacturers — capability heatmaps that compare certification, design IP, manufacturing scale, and channel penetration.
- M&A and partnership playbooks, including valuation frameworks, integration risk checklists, and a short list of acquisition archetypes that unlock rapid scale or capability.
- Primary research findings: buyer personas, procurement RFP excerpts, and 10 case studies showing how incumbents and challengers implemented rollouts with timeline and cost outcomes.
Strategic recommendations for 2026
- Prioritize procurement resilience: Establish multi‑tier supplier relationships for beeswax and alternative coatings, introduce minimum supply contracts, and budget for short‑term price stress in 2026 financial plans.
- Certify and document: Secure relevant material and process certifications (GOTS, FDA, LFGB, REACH where applicable) to unlock retail listings and institutional RFPs that will increasingly require documentary proof.
- Segment go‑to‑market by buyer need: Deploy distinct propositions for lifestyle retail (design, organic credentials), food service (durability, cost-per-use), and private label (price, lead times). Use pilots in high‑value accounts to refine pack formats and reuse messaging.
- Use policy as a growth lever: Map regulatory timelines to account prioritization — e.g., jurisdictions with imminent single‑use mandates should be targeted first for commercial partnerships and distribution investments.
- Evaluate strategic scale options: For mid‑sized players, assess M&A or joint ventures that add manufacturing capacity, compliance documentation, or access to institutional channels. For investors, target assets that combine brand premium with manufacturing control.
- Measure total cost of ownership for buyers: Create buyer tools that quantify cost‑per‑use and environmental benefits to dismantle price resistance in procurement processes.
Conclusion — the 2026 inflection point
The reusable food wrap market is entering a transitionary phase: robust headline growth, clear regulatory momentum, and supply‑side nuances that reward preparation and specialization. For companies willing to act in 2026 — by shoring up supply, certifying products, and aligning commercial models to buyer procurement cycles — the opportunity is to convert category growth into defensible, higher‑margin businesses.
Next steps — where to get the full intelligence
This article is a strategic preview designed to surface the most consequential decisions for 2026. Our complete Worldwide Reusable Food Wrap Market report provides the underlying datasets, regional and application splits, company revenue estimates, and downloadable financial models that support execution. To access the full report, detailed segment tables, and the proprietary scenario model, visit the PW Consulting report page or contact our market intelligence team.
For detailed analysis of this topic, please visit the official page: Worldwide Reusable Food Wrap Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com