

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Smart Lock with Cat’s Eye Market Poised for 13.5% CAGR Through 2032

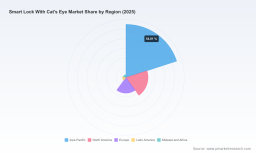
Worldwide Smart Lock With Cat's Eye Market — Strategic Preview for 2026
PW Consulting presents a strategic preview of our definitive market study, "Worldwide Smart Lock With Cat's Eye Market." This briefing distills the macro trends, competitive dynamics, regulatory vectors, and actionable 2026 playbook that senior executives, product leaders, corporate development teams, and security integrators will rely on for decision-making. It intentionally refrains from publishing the granular segment tables and region/application splits contained in the full report — those are preserved for subscribers — while delivering the analytical signal you need to prioritize investments and mitigate near-term regulatory and competitive risk.
Worldwide Glass Serological Pipettes Market
Market trajectory at a glance
The smart lock market integrated with cat's eye (visual peephole) capabilities moved from an emergent niche in 2020 into a fast-scaling market by 2025. Our base-year accounting shows the market expanding from approximately USD 850 million in 2020 to USD 1,550 million in 2025 (USD, Million). Under the scenarios modeled in this study, market value continues to accelerate through the forecast window 2026–2032, reaching roughly USD 3.76 billion by 2032. The modeled compound annual growth rate for the forecast period is 13.5% — a rate that confirms this segment is transitioning from early-adoption to broad commercial adoption and commoditization pressures.
Worldwide Heparin Lithium Market
Why 2026 is a strategic inflection point
- Product-to-platform transition: The category is moving beyond isolated hardware features (camera resolution, lens angle) to integrated experiences that combine device-level intelligence, cloud services, and home-platform interoperability. This shift makes 2026 the year many product strategies must pivot from single-device feature races to ecosystem plays.
- Regulatory crystallization: Emerging privacy and tenant-protection rules in multiple jurisdictions will materially affect product design, deployment practices, and commercial contracts. Companies that treat compliance as an afterthought will face adoption headwinds.
- Channel and margin realignment: As consumer awareness rises and distribution broadens, price-sensitive channels will pressure hardware margins, while recurring-revenue services (video storage, verified visitor logs, platform subscriptions) will become the new battleground for lifetime value.
What our full report delivers (practical, transaction-ready content)
The PW Consulting report is structured for immediate use by leadership teams executing in 2026. Key deliverables include:
Coal Logistics Market
- Top-down market sizing and bottom-up scenario models calibrated to macro adoption curves, device replacement cycles, and policy scenarios — enabling sensitivity testing for P&L and capex plans.
- Risk matrices that quantify regulatory exposure across jurisdictions, with "decision triggers" for product lock-steps (e.g., camera disable modes, retention caps, anonymization defaults) that should be embedded in roadmaps.
- Technology roadmaps and vendor capability maps that cross-reference biometric modalities (including 3D face recognition), camera optics (field of view requirements), on-device AI inference capacity, and cloud integration constraints.
- Commercial playbooks for go-to-market: recommended channel mixes by buyer persona, pricing levers for hardware-plus-service offers, and retention strategies for subscription monetization.
- M&A & partnership screening tools: a prioritized shortlist of target archetypes, due-diligence checklists focusing on software IP, manufacturing scalability, and certification readiness.
- Supply chain and sourcing playbooks that outline contract manufacturing strategies, component concentration risks, and mitigants for camera sensor and secure-element shortages.
- Competitive benchmarking templates and a vendor scorecard you can use to accelerate vendor selection and procurement decisions.
Competitive landscape — who matters and why
The competitive set combines global hardware brands, telco-scale vendors, platform enablers, and specialized OEMs. Market concentration is moderate: our CR3 and CR5 analysis show that leading groups command a meaningful, but not overwhelming, share (CR3 ≈ 32.5%; CR5 ≈ 41.2%). This structure creates room for technology differentiation, regional champions, and targeted M&A.
- Xiaomi (Beijing, China) — Xiaomi has adopted a volume-led strategy paired with frequent product refreshes. Their recent launches (2025) focused on larger indoor display experiences, wide-angle cat's eye feeds, AI human detection, night vision, and a broad array of unlocking modes. Xiaomi’s go-to-market advantage is its integrated smart-home ecosystem and retail reach; their play demonstrates how consumer brands can drive category awareness rapidly.
- Huawei (Shenzhen, China) — Huawei emphasizes integrated surveillance-grade features and multi-modal unlocking with on-device AI detection. The company’s strategy targets premium home-security buyers and leverages its systems-engineering capabilities to embed wide-angle optics and advanced inference on-device, serving customers concerned with latency and privacy.
- Yale (ASSA ABLOY, USA/global) — Yale represents the incumbent security heritage brand that is migrating trust in mechanical and electromechanical security to connected solutions. Their portfolio priorities show that strong channel relationships and brand trust still matter for adoption in traditional homeowner and property-management segments.
- Tuya Inc. (Hangzhou, China) — Tuya is a platform enabler. Their value prop is rapid OEM enablement, cross-manufacturer interoperability, and a route to cloud/services monetization. For OEMs and smaller brands, platform partners like Tuya remain a fast path to feature parity without heavy up-front software investment.
- Specialized OEMs (PuXin Smart, Locstar, Botin Smart Technology) — These vendors spotlight how product-level innovation (e.g., 1M-pixel cameras, 1080p indoor screens, 3D face recognition integrations) can be commercialized through white-label and channel-focused strategies. They are also the most agile acquirers and partners for larger platforms seeking capacity or niche IP.
Technology and product trends to prioritize in 2026
- Edge-first AI for privacy and latency: Moving inference onto the device reduces bandwidth and retention risk while improving responsiveness for anti-spoofing and human-detection workflows.
- Wide-angle optics and UI design: Field-of-view claims are table stakes; the real differentiator is user experience — large indoor feeds, one-touch evidence export, and frictionless access logs.
- Interop-first product architecture: Open APIs and certified integrations with major smart-home platforms elevate resale and retention across channels.
- Hardware as a carrier for services: Monetizable services (secure cloud storage, verified visitor credentials, concierge integrations) should be mapped to three-year LTV scenarios to justify customer-acquisition spend.
Regulatory and privacy vectors — designing for compliance by default
Regulatory noise is no longer hypothetical. In several markets the legal framing around camera-equipped door devices is tightening. Our dynamics analysis highlights three themes:
- In some jurisdictions, existing standards still focus narrowly on mechanical safety and lack uniform guidance for camera recording, retention, or triggered capture — creating legal ambiguity for manufacturers and integrators.
- In regions governed by comprehensive data-protection laws (for example, GDPR-style regimes), device designers must ensure footage is strictly for private purposes and that optics avoid capturing neighbors or public spaces without clear legal bases.
- Localized statutes — such as tenant-data protections in certain urban centers — introduce requirements for consent, key-preservation, data minimization, and retention limitations that can alter product deployment economics.
For product and legal teams, the implication is straightforward: build privacy controls into UX flows, offer hardware-level camera-disable options, provide retention defaults aligned with the most stringent markets you plan to enter, and bake those constraints into your product requirement documents and contracts.
Actionable recommendations for corporate leaders in 2026
- Prioritize platform partnerships over point-feature races: If you are scaling, partner with platform enablers that reduce time-to-market while preserving pathways to proprietary services. If you are defending margin, invest in services that lock in recurring revenue.
- Adopt "privacy by default" product specs: Align firmware and cloud defaults to the strictest regulatory environment you serve. This reduces downstream retrofit costs and litigation risk.
- Refine go-to-market segmentation: Use the full report’s buyer-persona matrices to allocate channel investments toward high-LTV segments (e.g., property managers, smart-home premium buyers) where service monetization is realistic.
- Embed edge-AI and secure elements: Competitive advantage will accrue to products that deliver reliable on-device inference, anti-spoofing, and cryptographic key protection without increasing BOM beyond acceptable channel thresholds.
- Prepare an M&A playbook focused on capability gaps: Look for targets with verified software IP, proven manufacturing scale, or regional certifications that shorten time-to-market and regulatory approval cycles.
How the PW Consulting report powers your 2026 decisions
Our report provides the analytical instruments executives need to make high-stakes choices under uncertainty. Subscribers receive:
- Stress-tested forecasts (base, upside, downside) with sensitivity levers for pricing, conversion rates, and regulatory compliance costs;
- Vendor scorecards and procurement templates that accelerate vendor selection while protecting margin assumptions;
- Decision trees and implementation checklists for privacy-first feature rollouts and region-specific certification strategies;
- Transaction intelligence including valuation multiples for recent exits/acquisitions in adjacent categories and an M&A target heat map.
Importantly, this preview intentionally withholds the granular region, type, and application split tables and detailed unit-price thresholds that are included in the full report. Those tables are the output of our proprietary triangulation across shipment data, channel checks, and OEM interviews and are essential for tactical procurement and M&A diligence.
Concluding perspective
The smart lock market with integrated cat's eye capability is no longer an experimental niche — it is becoming a mainstream element of residential and commercial security portfolios. The growth profile is compelling, but the path to durable margin requires executives to master three disciplines in 2026: platform economics, privacy-compliant product design, and disciplined channel monetization. Companies that refactor roadmaps toward services and regulatory resilience will capture disproportionate value as the market scales at an anticipated 13.5% CAGR through 2032.
For boards, C-suite executives, and investors preparing capital allocation and product roadmaps for 2026, our full report supplies the granular segmentation, vendor benchmarks, and scenario tools necessary to convert this strategic preview into executable plans. To access the comprehensive dataset, strategic appendices, and vendor scorecards, refer to the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Smart Lock With Cat's Eye Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com