

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Rack‑mounted Full Liquid CDU Market to Nearly Double from USD 105.0 Million in 2025 to USD 203.45 Million by 2032 at a 9.85% CAGR — North America (~42%) and Liquid‑to‑Liquid CDUs (~68.5%) Drive Demand
By pmarketresearch, 2026-08-12
PW Consulting Releases Strategic Brief: Rack-mounted Full Liquid CDU Market — A Decision-Grade Preview for 2026
PW Consulting’s latest industry study on the Rack-mounted Full Liquid Coolant Distribution Unit (CDU) market delivers executive-grade intelligence designed to influence procurement, engineering and capital-allocation decisions in 2026. Our analysis synthesizes historical build rates (2020–2025), near-term market sizing and a 2026–2032 forecast horizon, and couples quantitative projections with operational playbooks for data center owners, hyperscalers, OEMs and systems integrators. This release is a curated preview: it exposes the strategic findings and actionable recommendations you need to decide quickly, while preserving the report’s granular tables and vendor-level scorecards for subscribers.
Driven Hydraulic Wrench Market
Market at a Glance — Why 2026 Is a Pivotal Year
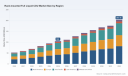
The rack-mounted full liquid CDU market has moved from an early adoption phase into a structured growth market. PW Consulting estimates the market value reached USD 105.0 Million (base year 2025) and is forecast to grow at a compound annual growth rate (CAGR) of 9.85% over the 2026–2032 period, roughly doubling in value by 2032. This trajectory reflects a confluence of forces: the accelerated deployment of GPU-dense AI racks and HPC clusters, tighter facility reliability standards, and a shift toward higher coolant temperatures and direct-to-chip heat extraction strategies.
Ionizing Radiation Precision Instruments Market
Concentration metrics in the competitive landscape indicate a moderately consolidated market: the top three suppliers account for just under half of market revenue, while the top five push well beyond the halfway mark. This structure creates clear zones of competition — entrenched leaders who control scale and channel access, and nimble challengers who compete on modularity, thermal performance or integration services.
Worldwide Parenteral Nutrition Fat Emulsion Market
What the Report Delivers — Practical, Executable Assets
- Operational Playbooks: Installation-validated checklists for rack-level CDU deployment (electrical, hydraulic, piping isolation and commissioning sequences), plus integration blueprints for direct-to-chip and cold-plate architectures.
- Procurement & Vendor Selection Toolkit: RFP templates, evaluation rubrics, SLA clause libraries and spare-parts agreements tailored to rack-mounted CDU lifecycles.
- TCO & Scenario Models: Proprietary total-cost-of-ownership calculators that factor CapEx, energy impacts, fluid chemistry, maintenance regimes and asset modularity; editable scenario files for sensitivity analysis across electricity prices, inlet approach temperatures and failure rates.
- Regulatory & Standards Roadmap: Compliance checklists and adoption pathways aligned with the latest ASHRAE TC 9.9 guidance and forthcoming addenda to Standard 127 — essential for separating Facility Water Systems (FWS) and Technology Cooling Systems (TCS) and for credible performance certification.
- Supplier Scorecards & Shortlists: A synthesized vendor assessment across technology fit, scalability, service footprint and supply-chain risk — enabling rapid down-selection for pilots and production rollouts.
- Executive Briefings & Board-Ready Slides: Decision-support packages focused on purchase timing, financing alternatives, and integration timelines for AI/HPC procurement cycles.
Strategic Implications for 2026 Decision-Makers
- Operational resilience over lowest upfront price: With ASHRAE guidance emphasizing separation of FWS and TCS, data center operators should prioritize CDUs that offer certified isolation barriers, redundant or hot-swappable pumping, and clear serviceability access. The report maps failure-mode impacts to service-level targets so CFOs and CTOs can align on acceptable residual risk.
- Design for modular scale: GPU and accelerator densities are evolving quickly. Units that support modular scaling — from rack-level up to multi-rack clusters with predictable hydraulic balancing — reduce retrofit costs and shorten time-to-capacity.
- Thermal strategy matters: Narrow approach temperatures and elevated water operating points unlock higher free-cooling and waste-heat recovery opportunities. However, these choices carry implications for fluid selection, certification and supplier life-cycle support; our TCO models quantify the break-even across common design options.
- Supply-chain & materials vigilance: Global phase-downs of certain refrigerants and evolving supplier certification requirements raise component lead times and compliance costs. Procurement teams should integrate material-certification clauses into long-term contracts and build multi-sourcing where practical.
- Choose partners with end-to-end capabilities: Integration risk is frequently the largest hidden cost. Vendors that combine CDU hardware with controls, lifecycle services and rapid global spare-part support deliver lower total operational disruption during scale-up and peak load migration.
Competitive Landscape — Who Matters and Why
PW Consulting’s market mapping identifies a diverse set of influential suppliers, each presenting different value propositions for 2026 deployments:
- CoolIT Systems (Calgary, Canada) — Known for high-performance in-rack CDUs (CHx200, CHx80) optimized for dense HPC and AI servers; strength lies in compact liquid-to-liquid modules designed for direct integration with high-power servers.
- Super Micro Computer / Supermicro (San Jose, USA) — Offers in-rack and in-row CDUs with redundant, hot-swappable pumps and very high unit capacities; their systems are attractive to integrators needing rack-level resilience and vendor-aligned server fitment.
- DCX Liquid Cooling Systems (Warsaw, Poland) — Focuses on compact, high-capacity liquid-to-liquid CDUs (HYDRO CDU1) for AI centers where per-rack power density and minimized footprint are decisive.
- LiquidStack (Carrollton, USA) — Delivers solutions supporting narrow approach temperatures and elevated water operation for ultra-high-density deployments, with offerings that scale to very high per-unit capacities.
- Flex (via JetCool) (Austin, USA) — Recently launched modular rack-level CDU platforms that emphasize scalability (announced 2025), signaling a move towards large-scale, OEM-backed modular solutions for hyperscalers.
- Motivair (by Schneider Electric) (Lancaster, USA) — Recently announced scalable CDUs targeting next-generation AI deployments (January 2026), leveraging Schneider’s systems integration depth for floor-to-rack solutions.
- Asetek (Denmark) — Competes on warm-water InRackCDU systems for efficient, serviceable rack cooling where moderate per-rack capacities are the design point.
- nVent (Minneapolis, USA), Dell Technologies (Round Rock, USA), Eaton (Dublin/US operations) — These established players bring reliability, channel reach and integration services; they are frequently preferred when operators prioritize vendor consolidation and enterprise-grade support.
Recent product moves — such as Flex’s modular launch in late 2025 and Motivair’s high-capacity MCDU announcement in early 2026 — highlight a competitive emphasis on modular scalability and higher per-rack capacities. Dell’s continued promotion of rack-mount RCDU solutions reinforces that major OEMs are actively positioning to supply integrated server/CDU stacks for AI and HPC customers.
Regulatory & Standards Context — What Keeps Risk Managers Awake
Two regulatory trends should be part of every 2026 procurement checklist. First, ASHRAE TC 9.9’s recent emphasis on CDU-based isolation between Facility Water Systems and Technology Cooling Systems elevates design review requirements for third-party certs and field commissioning documentation. Second, updates to ASHRAE Standard 127 (with new test-method addenda covering liquid-to-liquid CDUs) will change how suppliers’ performance claims are validated — and therefore how buyers compare products on an apples-to-apples basis.
Finally, environmental policy levers — including the Kigali Amendment’s phase-down of specific refrigerants — are increasing certification and compliance costs for thermal components and may alter supplier cost structures and lead times. Our report provides mitigation strategies, recommended contractual protections and sourcing pathways that limit exposure to material-driven cost escalation.
How PW Consulting’s Report Supports Tactical Pilots and Strategic Roadmaps
- Pilot-to-Production Playbook: Stepwise adoption templates for moving from single-rack pilots to row- and room-level liquid cooling mosaics, with staged capital outlays and operational checkpoints.
- Vendor Negotiation Guides: Benchmarked service windows, warranty terms and spare-part policies distilled from supplier interviews and primary deployments.
- Integration Checklists: Controls interoperability, telemetry expectations and cybersecurity hardening for CDU control systems and BMS/EMS integration.
- Scenario-Based Risk Matrices: Energy-price sensitivity, elevated-water-performance scenarios and maintenance staffing models that reveal the levers with the largest impact on cost of operations.
Next Steps — Where to Find the Full Intelligence
This release is a strategic preview intended to orient 2026 decisions and highlight the areas where immediate action yields disproportionate value. The full PW Consulting Rack-mounted Full Liquid CDU Market report contains the detailed regional and application splits, vendor line-item revenue forecasts, downloadable TCO spreadsheets, vendor scorecards and procurement templates reserved for report subscribers. These elements are intentionally withheld from this public summary to preserve the proprietary analytics and to enable clients to act on validated, decision-grade intelligence.
Contact PW Consulting or visit our report page to access the full dataset, schedule a private briefing, or engage our consultants for a customized vendor selection and pilot plan. In a market evolving as quickly as rack-mounted liquid CDUs, timely insight and disciplined execution will separate winners from laggards in 2026.
For detailed analysis of this topic, please visit the official page: Rack-mounted Full Liquid CDU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Video Inspection Robot Market to Reach USD 4,158.62 Million by 2032, Expanding at a 7.85% CAGR (2026–2032)
By pmarketresearch, 2026-08-12
Video Inspection Robot Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Brief
As infrastructure owners, industrial operators, and technology investors plan for the next chapter of capital allocation and operational modernization, PW Consulting releases a targeted industry brief that synthesizes multi-year market dynamics and delivers an actionable roadmap for decisions to be taken in 2026. Our Video Inspection Robot Market report — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — frames opportunity and risk across technology, supply chains, regulation, and competitive positioning. At the macro level, the market has expanded materially from our 2025 base and is forecast to grow at a compound annual growth rate (CAGR) of 7.85% through the forecast period, reflecting accelerating investment in remote visual inspection, robotics autonomy, and data-driven asset management.
Worldwide Benchtop Hydrogen Analyzers Market
Why this brief matters for 2026 decision-makers
-
Timing: 2026 will be a decision-heavy year for procurement cycles and deployment pilots. Organizations that move beyond vendor demonstrations to structured pilots with well-defined success metrics will secure earlier operational benefits and superior negotiating leverage.
Story Puzzle Game Market -
Capital allocation: With the market set on a mid-single-digit to high-single-digit growth trajectory, executives must choose between buying mature systems, co-developing specialized platforms, or adopting robotics-as-a-service models. Each path has distinct implications for CAPEX, OPEX, and balance-sheet exposure.
1G6P Lens Market -
Regulatory and supply risks: New trade and regulatory actions, coupled with sensor and optics supply constraints, are compressing lead times and increasing components’ unit cost volatility. Procurement teams need hedging strategies that go beyond single-source buying.
-
Data monetization and asset intelligence: Video inspection platforms are becoming conduits for condition-based maintenance and GIS-enrichment. How organizations design their data ingestion, labeling, and analytics pipelines will determine the long-term ROI of robotics investments.
What’s inside the PW Consulting brief (practical content highlights)
-
Executive synthesis: A concise view of market size, growth trajectory, and high‑level segmentation dynamics to support board-level briefings and investor memos.
-
Technology maturity map: Comparative assessment of mobility platforms (crawlers, pole systems, aerial drones), onboard imaging and sensor suites (HD video, sonar, laser profiling), autonomy stacks (path planning, SLAM, defect recognition), and communications approaches (wireless, tethered, edge-cloud). Each technology is scored for readiness, integration complexity, and expected TCO impact.
-
Vendor diligence templates: Rapid supplier scorecards, contract negotiation checklists, test-and-acceptance protocols, and field validation playbooks to reduce procurement cycle time and mitigate integration risk.
-
Implementation playbooks: Step-by-step deployment roadmaps by use case (e.g., sewers and pipeline inspection, confined space inspection, large‑diameter asset monitoring) including pilot sizing, metrics for go/no-go decisions, and maintenance scheduling guidance.
-
Regulatory impact and scenario planning: Structured scenarios that quantify the operational impact of tariff regimes, import controls, and certifications (e.g., ATEX/IECEx) on sourcing strategies and total cost of ownership.
-
Financial tools: ROI and payback calculators, service model comparisons (capex vs. robotics-as-a-service), and sensitivity analyses that stress-test vendor pricing and component-cost inflation.
-
M&A and partnership playbook: Criteria for evaluating acquisition targets and technology partnerships, and a shortlist of capability gaps that are most valuable to bolt-on or co-develop.
Competitive landscape — what to watch
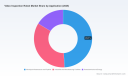
The market remains fragmented with a modest level of concentration: the top three suppliers account for under one quarter of industry sales and a top five concentration below forty percent. That structure creates room for both focused niche players and global integrators to capture value.
-
Envirosight LLC (Randolph, NJ) continues to push the boundary on integrated inspection platforms with HD imaging and AI-assisted defect detection embedded in field-capable crawlers. Their recent product introduction further crystallizes the shift from manual video logs to automated defect recognition workflows, making them a benchmark for municipal and utility procurement teams seeking vendor maturity.
-
Deep Trekker Inc. (Kitchener, ON) remains differentiated by hybrid underwater and confined-space platforms that combine mobility engineering with proven HD optics. Their systems are often selected for cross-environment use cases where robustness and ease-of-deployment matter more than peak autonomy.
-
IBAK Helmut Hunger GmbH & Co. KG (Kiel, Germany) has advanced panoramic video and 3D laser profiling integration, signaling a move toward high-fidelity condition assessment packages that support advanced asset modeling and rehabilitation planning.
-
CUES Inc. , RedZone Robotics , Mini-Cam Ltd. , and iPEK each bring distinctive approaches—truck-mounted systems, large-diameter automation, compact drain crawlers, and modular CCTV platforms respectively—highlighting the spectrum of form factors buyers must evaluate.
-
Waygate Technologies (Baker Hughes) illustrates how industrial multinationals are applying remote visual inspection expertise to hazardous and certified environments; their recent deployment of explosion-proof robotic systems underscores demand for certified offerings in energy and petrochemical sectors.
-
Wuhan Easy-Sight and other Asia-based manufacturers remain competitive on price and increasingly on feature parity; however, buyers must overlay geopolitical and tariff considerations into sourcing decisions.
Recent market moves and implications
-
Product innovation is active: Several vendors launched new platforms or upgrades in 2025–2026 that embed AI, panoramic 3D profiling, wireless telemetry, and intrinsically safe certifications. Buyers should adopt evaluation frameworks that prioritize integration capability and lifecycle update paths over one-off feature sets.
-
Regulatory trade actions are reshaping sourcing: Investigations and tariffs initiated in 2025 impacting robotics and related components increase the probability that procurement teams will incur higher landed costs or face longer lead times. Scenario-based sourcing and dual-sourcing strategies are no longer optional for critical programs.
-
Supply-chain constraints around precision optics and sensors remain the primary operational choke point. Teams that invest in early qualification of alternative suppliers and component-substitution testing will shorten deployment cycles and reduce schedule risk.
Strategic recommendations for 2026 — six concrete moves
-
Conduct a 90‑day supplier stress test: Simulate procurement cycles under tariff and lead‑time stress to identify single points of failure. Prioritize vendors that can produce certified alternatives or have regional manufacturing footprints.
-
Run two parallel pilots: one focused on operational maturity (scheduling, integration with CMMS/GIS) and another focused on analytics (AI defect recognition, dataset labeling). Require vendors to deliver exportable video/data deliverables to avoid lock-in.
-
Implement a modular procurement clause: Specify interchangeability of core elements (cameras, processors, comms) to foster competitive upgrade paths and reduce total upgrade costs over the asset lifecycle.
-
Negotiate outcome-based contracts for high-volume programs: Tie a portion of vendor compensation to agreed uptime, inspection throughput, or defect-detection accuracy to align incentives and shift risk to suppliers.
-
Invest in a data strategy and governance model: Define labeling standards and data storage schemas now so inspection outputs can be monetized or repurposed across asset management, planning, and regulatory reporting functions.
-
Evaluate strategic M&A or JV options to fill capability gaps (e.g., autonomy, laser profiling, explosion-proof certifications) rather than relying solely on long, uncertain internal development cycles.
How PW Consulting’s dataset supports these decisions
Our brief pairs a quantitative top-down market sizing with practical, operationally oriented deliverables. We provide the high-level market scale and the growth rate context you need to prioritize portfolios and scenario-plan for 2026, while delivering the playbooks, scorecards, and procurement templates organizations require to convert strategy into executed programs. To preserve our role as an unbiased advisor and to protect proprietary client workflows, deeper segmentation matrices, vendor market shares, and precise pricing benchmarks are made available exclusively in the full report and accompanying data package.
Final note — the “trailer” approach
This industry brief is designed as a high-value preview: it demonstrates the analytical depth and practical orientation of PW Consulting’s Video Inspection Robot Market report while intentionally withholding proprietary subsegment tables and granular vendor share figures. If your organization is preparing a 2026 procurement cycle, an investment evaluation, or an asset digitalization roadmap, the full report contains the detailed datasets, scenario models, and negotiation templates required to act with confidence.
To request the complete report, data workbook, and an executive briefing tailored to your organization’s operating context, visit our report page or contact the PW Consulting industry desk. Time-sensitive regulatory shifts and component shortages make rapid access to validated market intelligence a competitive advantage — now is the moment to convert insight into decisive action.
For detailed analysis of this topic, please visit the official page: Video Inspection Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cordless Telephone Battery Market to Edge Down in 2026–2032 (CAGR −0.51%); 2025 Revenue USD 485.5 Million — Ni‑MH Dominates at USD 397.64M, Aftermarket USD 411.47M, Europe Leads with USD 151.01M
By pmarketresearch, 2026-08-12
Worldwide Cordless Telephone Battery Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
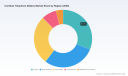
The Worldwide Cordless Telephone Battery market is at an inflection point. While the installed base of DECT and low‑power cordless handsets supports a stable replacement economy, regulatory shifts and emerging DECT NR+ deployments are reshaping product requirements and supplier economics. Our PW Consulting report — based on a 2025 base year and a 2026–2032 forecast horizon — shows a 2025 market size of approximately USD 485.5 Million and a modest compound annual growth rate of -0.51% across the forecast period. This headline stability masks short‑term volatility and structural changes that will determine winners and losers in 2026 and beyond.
Wearable Smart Wristbands Market
Why this matters for 2026 planning
For executive teams responsible for product strategy, supply chain, and channel go‑to‑market, the cordless battery market no longer permits a "set and forget" approach. A near‑term rebound in 2026 (reflected in our top‑line projections) coexists with longer‑term downward pressure driven by device energy‑efficiency standards, shifting battery chemistry economics, and channel dynamics between aftermarket replacement and OEM supply. In practice, that means decisions made in the coming 12 months — component sourcing, warranty policy, and aftermarket engagement — will materially affect profitability and market positioning through 2028.
Worldwide Fire Department Software Market
What the macro data tells us
Key macro signals from the dataset and modelling underpin three practical conclusions for strategists:
Worldwide Bot Management Solution Market
- Stability with episodic volatility: The overall market base (2025) and the near‑term model show a bounce and subsequent oscillation in revenues rather than a monotonic decline. Tactical inventory and procurement flexibility will therefore outperform rigid annual contracting models.
- Low but negative long‑term drift: The slight negative CAGR across 2026–2032 indicates a gradual contraction driven by efficiency improvements, longer handset lifecycles, and regulatory energy benchmarks — not a sudden structural collapse. Firms should prioritize margin protection and cost containment over aggressive volume expansion.
- Concentration matters: Market concentration metrics in our analysis (CR3 ~38.5%, CR5 ~52.2%) reveal a mid‑consolidated sector where top vendors exert meaningful influence without forming a closed oligopoly. This creates fertile ground for mid‑sized players and nimble specialists to expand via targeted product or channel plays.
Regulatory and technology inflection points
Regulation and standards are the proximate drivers of technical specification changes that downstream battery suppliers will need to absorb. The EU Ecodesign rules (effective June 2025) introduce explicit expectations for energy efficiency and minimum battery cycle life performance, and base station standby power caps create a tighter energy budget across cordless ecosystems. Meanwhile, the progression toward DECT NR+ (spectrum and system updates rolled forward in late 2025) unlocks new handset capabilities but also raises implications for duty cycles and battery endurance.
Product launches such as Fanvil’s W610D demonstrate the pace at which handset OEMs are integrating higher performance cordless subsystems. Taken together, these developments move battery requirements from pure energy capacity metrics toward a richer set of attributes: cycle life under real‑world duty profiles, standby/active power interplay, thermal stability, and compliance documentation.
Supply chain and material dynamics
Cordless telephone batteries continue to be dominated by mature chemistries that balance cost, safety, and lifecycle for low‑power applications. In this market context, lithium‑ion price deflation at the consumer‑electronics level has limited immediate effect on the segment because product designers have not broadly shifted to Li‑ion for legacy DECT handsets. Geopolitical tensions and tariffs on critical minerals do meaningfully shape broader battery supply chains; however, cordless telephone packs typically exhibit lower exposure to those concentrated raw materials than, for example, EV or grid‑scale battery sectors. For procurement teams, the priorities are therefore:
- diversifying qualified NiMH and small‑format Li‑ion cell suppliers,
- maintaining robust secondary sources for cells and pack assembly, and
- locking technical specifications and test protocols that align with impending Ecodesign and DECT NR+ requirements to avoid costly late‑stage redesigns.
Competitive landscape — who matters and why
The market is a mix of retail/aftermarket specialists, traditional cordless OEMs, and battery manufacturers. Each cluster requires a different strategic posture:
- Retail and aftermarket specialists (examples: Interstate Batteries, BatteryClerk, Batteries Plus) — these players excel in channel reach, replacement compatibility, and brand trust among consumers and small businesses. For OEMs, partnerships or white‑label agreements with these distributors remain attractive routes to extend product life and recapture end‑of‑life value.
- Integrated handset OEMs (examples: VTech, Panasonic, AT&T) — OEMs control specification and have the most direct route to standardize compliant battery packs for new handset lines. They are also the primary locus for embedding Ecodesign compliance into new releases and shaping the market’s technical bar.
- Contract manufacturers and cell suppliers (examples: Shenzhen Tcbest Battery, EnerSys) — these vendors provide the manufacturing capacity and engineering know‑how necessary for scale and customized pack solutions. Their role becomes pivotal when OEMs pursue rapid spec changes to meet regulation or new DECT features.
Our report contains concise strategic profiles of these firms, highlighting supply strengths, channel footprints, and M&A posture — enabling quick benchmarking and partner selection in 2026.
Commercial dynamics: aftermarket vs OEM
The aftermarket replacement economy remains the primary margin and volume engine for the cordless battery market. OEM replacement and bundled supply are strategically important for new handset launches and brand‑protected channels. For 2026, the tactical priorities differ by role:
- Retailers and aftermarket specialists should invest in warranty clarity, compatibility search tools, and compliance labeling to capture consumers trading up under Ecodesign awareness.
- OEMs need to accelerate battery validation programs and consider extended service/recertification offers to capture lifecycle revenue while conserving device longevity in a regulation‑tightened environment.
Practical recommendations for 2026
Leaders who intend to use 2026 to build durable advantage should prioritize five actions:
- Operationalize regulation: Build a cross‑functional Ecodesign readiness program (product, test labs, compliance, marketing) with a 6–12 month roadmap and clear acceptance criteria linked to warranty and R&D budgets.
- Flexible sourcing: Move to smaller, more frequent cell procurement contracts with dual qualified suppliers to buffer short‑term swings while maintaining price discipline.
- Aftermarket monetization: For OEMs, create certified replacement programs and trade‑in pathways that capture revenue and reduce gray‑market leakage.
- Portfolio triage: Apply a profitability heatmap across SKU families to decide which battery technologies and handset lines justify engineering investment versus those better suited to aftermarket replacement strategies.
- M&A and partnerships: Given mid‑market concentration, identify tuck‑in targets among regional pack assemblers or aftermarket specialists to accelerate channel scale and technical capabilities.
What PW Consulting’s report delivers
Our Worldwide Cordless Telephone Battery Market report is designed as a practical playbook for 2026. It includes:
- Top‑line forecasts and scenario modelling (base case, high demand, regulation‑forced redesign) for 2026–2032, with stress testing for energy‑efficiency and unit‑life assumptions.
- Supplier and channel heatmaps with qualitative supplier capability assessments and an M&A watchlist.
- Regulatory impact matrix (including Ecodesign obligations and DECT NR+ implications) that links compliance actions to capex and product timelines.
- Operational annexes: test protocols, recommended battery validation matrices, warranty framing templates, and an aftermarket monetization playbook.
- Executive dashboards and a downloadable scenario model so commercial teams can run "what‑if" cases specific to their product and region strategies.
How to use this insight in the boardroom
Board conversations in 2026 should move beyond positional statements about "market decline" to granular decisions tied to procurement cadence, product roadmap triage, and channel economics. Use the report’s scenario tool to quantify the P&L impact of: changing minimum cycle life requirements, supplier consolidation, and an increasing share of sales moving to certified replacement channels. That work will identify whether to accelerate R&D (for regulated compliance), de‑risk supply, or double down on aftermarket services.
Next steps and where to find the full segmentation
In keeping with our "trailer" approach, this release highlights the strategic takeaways and supporting context you need to prioritize 2026 actions while deliberately reserving the granular, segment‑level tables and model outputs for the full report. For access to detailed region, chemistry and channel split data, downloadable models, and vendor scorecards, please visit the PW Consulting report page or contact our industrial practice team for a tailored briefing.
Prepared by PW Consulting — Senior Strategy & Industry Analysis. For executive briefings or bespoke modelling workshops tied to this market, our team is available to support rapid, board‑level decision cycles in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Cordless Telephone Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects 7.85% CAGR for Worldwide Veterinary Glucometers Market During 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Veterinary Glucometers Market — Strategic Outlook for 2026: PW Consulting Report Preview
Executive summary
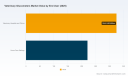
PW Consulting’s new market study on Worldwide Veterinary Glucometers provides a targeted, decision-ready briefing for executives planning product, commercial, and M&A strategies in 2026. The veterinary glucometers market has matured into a predictable growth opportunity: after expanding through 2020–2025 and reaching an estimated market size of USD 545.6 Million in our 2025 baseline, the market is forecast to continue at a robust compound annual growth rate (CAGR) of 7.85% through our 2026–2032 modeling horizon, approaching roughly USD 926 Million by 2032. For leadership teams evaluating near-term investments, this trajectory frames how quickly incremental innovations — especially around continuous glucose monitoring (CGM), species-specific algorithms, and connected care — can scale commercial returns.
Aircraft Lift Control Devices Market
Why this preview matters for 2026 decision cycles
- Timing of strategic moves: With a clear upward trajectory from the 2025 baseline into 2026, the window for first-mover advantage on clinic-directed CGM products and integrated digital services is narrowing. Executives who align R&D and distribution decisions to calendar-2026 launch windows can capture premium adoption among progressive veterinary networks.
- Capital allocation prioritization: Our scenario work shows that incremental investments in species-specific calibration, clinical validation, and vet-facing software yield outsized returns versus equivalent spend on general-purpose human meters repurposed for animals.
- Channel and partnership sequencing: The market’s current structure — moderately concentrated among a few global animal-health majors and specialized device providers — favors hybrid strategies combining direct distribution to veterinary hospitals with distributor-led clinic and retail channels for home care adoption.
What the full report contains (practical deliverables)
This preview highlights strategic findings; the complete PW Consulting report delivers the operational tools that business and product teams will use to execute against them. Key deliverables include:
Worldwide Video Lottery Terminals (VLT) Market
- Dynamic market model (2020–2032) with downloadable scenario tabs (base, conservative, accelerated) enabling sensitivity testing of price, adoption and reimbursement levers.
- Go-to-market playbooks tailored to four commercial archetypes — global animal-health incumbent, hospital-focused specialist, digital-native CGM entrant, and distributor-led aggregator — with roll-out timelines calibrated to 2026 regulatory and purchasing cycles.
- Product feature and technical benchmarking, showing where species-specific calibration, sample volume, connectivity, and analytics deliver the greatest clinical and commercial delta.
- Regulatory and validation checklist for veterinary devices, including sample study designs to verify species-specific accuracy against laboratory reference methods and guidance on where ISO 15197 performance verification matters.
- Pricing elasticity and reimbursement matrix that models out-of-pocket versus clinic-procured adoption scenarios for companion-animal versus herd applications.
- Competitive playbooks and M&A screening filters with candidate lists and illustrative valuation ranges based on product portfolio complementarity and distribution footprint.
Market structure and competitive dynamics — how to read the competitive map
Our concentration analysis shows a market where the top three players capture a clear majority of revenue, and the top five extend that dominance further. This structure creates both defensive and offensive strategic implications: incumbents benefit from scale and established clinic relationships, while agile specialists can win on product differentiation and clinic-directed CGM offerings.
Multispecific Antibody Development Platform Market
Leading firms profiled in-depth include animal-health majors and focused device makers. Their strengths, strategies, and likely near-term moves are summarized below — the full report contains comparative scorecards, channel overlap maps, and launch-timing matrices for each named competitor.
- Zoetis — With AlphaTrak 3, Zoetis has leveraged species-specific algorithms and a pet-owner / clinician mobile app to entrench its position in companion-animal glycemic monitoring. Its playbook emphasizes integrated clinical workflows and data-sharing between clinics and owners, a model other incumbents are trying to emulate.
- i-SENS — i-SENS’ veterinary-calibrated meter (VetMate) represents the strategy of translating human-glucose sensing expertise into validated veterinary use with focused calibration for dogs and cats; it competes primarily on cost and distribution breadth.
- Nova Biomedical — Nova Vet’s combined glucose/ketone meters position the company to serve both companion and herd-related use cases, an approach that diversifies revenue streams but requires differentiated go-to-market motions.
- Universal Biosensors — PETRACKR focuses on handheld point-of-care tools with multi-pet profile management, targeting clinic workflows where repeat testing and patient tracking matter most.
- ALR Technologies (GluCurve), Adapet Medical — These entrants are accelerating the CGM shift for pets. ALR’s recent internal manufacturing validation and planned relaunch, and Adapet’s integrated monitoring of glucose, activity, and feeding data, underscore the sector’s technological pivot toward continuous, clinic-managed solutions.
- UltiMed / Advocate, MAI Animal Health, Woodley Equipment — These companies emphasize validated, species-specific handheld meters and accessories that support both clinical and at-home testing; they represent critical distribution nodes for broadening home-care adoption.
Regulatory and clinical validation: non-negotiables for 2026
Regulatory expectations and clinical best practices are central drivers of procurement decisions in veterinary medicine. Our report synthesizes current regulatory guidance and recent validation literature to provide a pragmatic pathway for CE-marking and for meeting expectations in major markets. Key regulatory realities include:
- Species-specific calibration and validation — devices must demonstrate accuracy against laboratory reference methods in the animal matrices they target (dog, cat, horse), and clinicians will expect documented, peer-reviewed comparators.
- Standards alignment — where ISO 15197 accuracy criteria can be applied or adapted to veterinary matrices, adherence materially improves purchaser confidence.
- Clinical trial design — the report includes templates for pivotal validation studies sized to support both veterinary-clinic adoption and distributor purchasing decisions, reducing time-to-order through pre-validated evidence packages.
Tech and product trends that will shape 2026 wins
Three clusters of innovation will disproportionately influence outcomes in 2026:
- Continuous Glucose Monitoring (CGM) for clinic-directed care: CGM systems designed specifically for pets are moving from niche to mainstream. These devices require clinic-directed distribution and support; companies that align manufacturing, training, and distribution with major veterinary distributors will scale fastest.
- Species-specific analytics and low-sample-volume meters: Companion-animal meters that minimize sample volume and provide species-calibrated outputs reduce clinical friction and improve owner adherence — direct drivers of retention and recurring consumables revenue.
- Connected care and data services: The value proposition increasingly includes cloud analytics, vet-owner sharing, and care-path orchestration. Monetization models extend beyond device sales to subscription-based analytics and clinic licensing.
Commercial implications and recommended plays for 2026
- For incumbents: Protect clinical relationships by bundling validated CGM pilots with training and data services for high-volume clinics. Use scale to negotiate distributor exclusivity in priority geographies and to rationalize consumables pricing.
- For challengers and startups: Focus on clinical evidence that demonstrates parity with leading handheld meters and highlight unique data features (e.g., integrated feeding/activity signals). Consider selective regional launches via partner clinics to build clinical case series prior to national rollouts.
- For distributors and retailers: Align inventory strategies to support hybrid purchasing — clinic procurement for CGM devices and retail/home options for validated handheld meters — and develop product education cohorts to accelerate vet endorsement.
- For investors and M&A teams: Target targets that bring either validated CGM IP, species-specific algorithm portfolios, or high-margin consumables with sticky clinic workflows; use the report’s M&A filters to screen and prioritize opportunities by time-to-market and channel fit.
Risk considerations and mitigation
Key risks include regulatory delays in local markets, off-label use of human flash glucose systems that can depress veterinary-specific device uptake, and supply-chain constraints for sensors and test strips. The full report offers mitigation playbooks, including tactical manufacturing redundancy plans, regulatory filing roadmaps, and clinical-education programs that reduce the attractiveness of off-label substitutes.
Next steps — how to use this preview
This preview is designed to inform 2026 planning conversations and to prioritize actions for product, commercial, and corporate development teams. For teams ready to act, the full PW Consulting report supplies the granular data, segmentation tables, competitor scorecards, and downloadable financial model necessary to build business cases, investment memos, and launch plans. Because the most actionable intelligence is in the fine-grained splits and scenario work, we intentionally withheld granular segmentation figures from this preview; the full dataset and model are available on the report landing page.
Recent developments highlighted in the report
- ALR Technologies completed internal manufacturing testing for its GluCurve Pet CGM in late 2025 and is planning a phased relaunch into Canada and the US in early 2026 — a development that shifts competitive dynamics for clinic-directed CGM solutions.
- Zoetis’ earlier launch of AlphaTrak 3 and its integrated mobile app illustrates the competitive edge obtained by coupling species-specific measurement with digital care pathways — a model the report evaluates for replication and defense strategies.
Get the full intelligence
To convert these insights into executable plans for 2026, PW Consulting’s full report and model provide the referenced segmentation detail, vendor-level financial benchmarks, and policy-readiness checklists. Access to the complete study includes one-on-one analyst time for bespoke scenario runs tailored to your portfolio and priority markets.
PW Consulting — from validated market sizing to tactical playbooks, we equip leaders to turn the veterinary glucometers market’s growth trajectory into sustained competitive advantage in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Veterinary Glucometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MRI-Compatible IV Infusion Pumps Market Poised for 8.6% CAGR (2026–2032)
By pmarketresearch, 2026-08-12
Worldwide MRI Compatible IV Infusion Pumps Market — Strategic Imperatives for 2026
PW Consulting today releases a strategic industry briefing accompanying our full market research report on the Worldwide MRI Compatible IV Infusion Pumps Market. Built for executive teams, corporate development functions, and health system procurement leaders, this briefing distills why 2026 will be a pivotal year for competitive positioning, capital allocation, and regulatory strategy in a market that is accelerating toward clinical mainstreaming.
Worldwide Linear Ultrasound Transducers Market
Snapshot: A market maturing at commercial and clinical frontiers
Our analysis uses 2025 as the base year and models the market through 2032. The global market for MRI-compatible IV infusion pumps—measured in USD millions—grew from USD 312.45 Million in 2020 to USD 465.00 Million in 2025. Under our central scenario, the market continues to expand at a compound annual growth rate (CAGR) of 8.6% across the forecast window (2026–2032), reaching an estimated USD 828.44 Million by 2032. This trajectory reflects a convergence of clinical demand, regulatory clarity, and targeted procurement programs that together lower barriers to in-scanner infusion therapy.
Worldwide Handwritten Notes Software Market
What is driving the next phase of adoption?
- Clinical demand for simultaneous imaging and therapy: Increasing MRI throughput, advanced interventional MRI workflows, and growth in pediatric/neonatal imaging heighten the clinical value of infusion devices that can safely operate in high-field environments.
- Regulatory and procurement tailwinds: Recent regulatory clearances and public procurement decisions recognizing non-magnetic solutions are creating reference cases that shorten the approval pathway and buying cycles for early adopters.
- Product innovation unlocking new use cases: Advances in non-magnetic drive systems (including ultrasonic motors), integrated drug libraries, wireless control interfaces, and systems-level shielding are shifting the value conversation from “if” to “how” to use infusion pumps in and around the MRI bore.
- Capital planning and replacement cycles: Hospital capital planning frameworks and useful-life benchmarks—commonly applied in the sector—are prompting refresh cycles in 2026 for infusion hardware purchased in the previous decade, creating demand windows for vendors with robust total-cost-of-ownership (TCO) propositions.
Regulatory and procurement context — why 2025–2026 matter
Two regulatory facts have immediate strategic implications. First, the FDA’s 510(k) pathway for MRI-compatible infusion pumps remains the primary route to U.S. market access; recent clearances demonstrate the agency’s expectations for device performance and human factors evidence. Second, public-health procurement authorities are increasingly willing to recognize unique clinical needs through sole-source or specialized procurement justifications when a truly non-magnetic solution is demonstrably unique.
Cold Atom Gravimeter Market
For market entrants and incumbents alike, the practical consequence is that a well-executed regulatory dossier (with strong human factors and clinical validation) plus targeted reference deployment can materially shorten sales cycles and support premium pricing—if supported by demonstrable patient-safety and workflow benefits.
Competitive landscape: consolidation, niche leadership, and product differentiation
The MRI compatible infusion pump market is highly concentrated, with the top three players commanding the vast majority of commercial revenues and the top five extending that dominance further. This concentration reflects significant technical barriers—validated non-magnetic actuation, MRI safety testing up to high gauss levels, and documented clinical workflows—that favor specialized suppliers and established infusion-platform vendors able to invest in certification and field support.
Key vendor archetypes identified in our report:
- Specialist non-magnetic innovators — Companies focused specifically on MRI-safe pump platforms have technological and regulatory advantages in the in-bore and near-bore use cases. Recent product clearances from such specialists create important commercial references.
- Large infusion-platform incumbents — Global infusion manufacturers leverage wide hospital footprints and integrated infusion management systems to sell MRI-aware solutions as part of broader therapy bundles.
- System integrators and shielding suppliers — Vendor solutions that pair infusion pumps with shielded carts or dedicated MRI-room platforms are establishing differentiated value propositions for complex multi-pump workflows.
Representative firms covered in the report include specialized innovators headquartered in the United States with cleared MRI offerings, legacy infusion systems vendors with MRI-compatible variants, and European and North American manufacturers offering integrated shielding solutions. Recent milestones in the competitive set—the granting of a 510(k) clearance for a next-generation non-magnetic pump system in May 2025 and a subsequent sole-source procurement intent from a major U.S. healthcare purchaser in early 2026—illustrate how regulatory milestones can immediately translate into procurement advantages for niche leaders.
Strategic implications for corporate decision-makers in 2026
As organizations plan priorities for 2026, the report highlights concrete actions across four decision vectors: product strategy, commercial go-to-market, regulatory and clinical evidence, and corporate development.
- Product strategy: Invest in non-magnetic actuation, robust drug libraries, intuitive wireless control, and modular shielding options. Prioritize human factors engineering early in development to de-risk 510(k) submissions and to shorten time-to-reference sites.
- Commercialization & partnerships: Forge alliances with imaging OEMs, MRI-focused systems integrators, and high-volume imaging centers. Design bundled offers that address workflow friction points—cabinetized carts, centralized monitoring, and MRI-safe tubing management—rather than standalone pumps alone.
- Regulatory & clinical evidence: Allocate budget to pre-market studies that align with FDA Total Product Life Cycle expectations and establish early clinical references in academic centers able to publish outcomes. These references accelerate adoption among health systems and support higher reimbursement or procurement prioritization.
- Corporate development: For incumbents seeking rapid capability upgrades, targeted acquisitions or minority investments in specialist non-magnetic pump makers can be a faster route to validated technology and installed-clinic references than greenfield R&D.
Risk matrix: what keeps CFOs and CPOs awake at night?
- Regulatory delay risk: Complex human factors expectations and the need for MRI-specific safety testing can extend approval timelines if not anticipated.
- Procurement variability: Differences in public and private procurement policies—especially where sole-source justifications are involved—mean that commercial success can hinge on a small number of early institutional wins.
- Clinical adoption hurdles: The incremental complexity of in-bore infusion workflows requires investment in training and change management; the cost of inadequate training can blunt adoption.
- Supply chain and component risk: Specialty components for non-magnetic actuation and shielding can face constrained supplier availability; suppliers should build redundancy into sourcing strategies.
What PW Consulting’s full report delivers — and why the granular data matters
Our full market study (base year 2025; forecast 2026–2032) combines a rigorous topline forecast with deep, actionable modules designed for strategy execution:
- Detailed market-sizing and growth scenarios with sensitivity analysis under alternative adoption and reimbursement assumptions.
- Segment-level analyses covering device types, clinical applications, and regional dynamics (note: segment-level numerical breakdowns are covered in the full report).
- Vendor scorecards and product benchmarking against safety, performance, usability, and service metrics.
- Regulatory pathway maps and clinical evidence templates tailored to 510(k) submissions and human-factors planning.
- Procurement playbooks for hospital purchasing groups and public health authorities, including negotiation levers and total-cost-of-ownership models built around common capital-life benchmarks.
- M&A and partnership targets identified by strategic fit and integration risk, with modeled impact on market share and revenue synergies.
To preserve the strategic value of this briefing and to support competitive decision-making, we have intentionally withheld detailed granular splits and proprietary scenario outputs from this press summary. The full dataset, vendor-by-vendor performance matrices, and downloadable financial models are available through the PW Consulting report portal.
Conclusion — why 2026 is a make-or-break year
For executives evaluating capital allocation and go-to-market strategy, 2026 presents a window of opportunity: regulatory clarity and early procurement precedents are converting a historically niche capability into an investable clinical platform. Companies that align product development with rigorous human factors data, secure early clinical references, and craft bundled workflow solutions will capture disproportionate upside in a market that is forecast to nearly double in revenue through 2032 at an 8.6% CAGR.
PW Consulting’s full report equips decision-makers with the quantitative forecasts, vendor intelligence, and tactical playbooks required to act in 2026 with confidence. For access to the complete study, including our proprietary models and vendor scorecards, please consult the PW Consulting report release page.
For detailed analysis of this topic, please visit the official page: Worldwide MRI Compatible IV Infusion Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cupping Therapy Kits Market Poised for 5.8% CAGR in 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Cupping Therapy Kits Market: Strategic Preview for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s senior industry analyst, I present a guided preview of our newest market research — the Worldwide Cupping Therapy Kits Market report (base year 2025). This briefing highlights the strategic signals that matter for boardrooms, corporate strategy teams, and private investors planning moves in 2026. It demonstrates the report’s practical value without disclosing the full, proprietary segmentation tables and financial matrices reserved for the full publication.
Mini LiDAR Market
Why this market matters in 2026
Cupping therapy kits sit at the intersection of traditional medicine, consumer wellness, and clinical rehabilitation. After recovering from early-pandemic volatility, the global market expanded from an estimated USD 145.2 Million in 2020 to USD 192.48 Million in 2025. Under the conservative scenarios modeled in our forecast, the market continues to grow through the 2026–2032 window at a compound annual growth rate (CAGR) of 5.8%, reaching an expected market size above USD 285 Million by 2032.
Worldwide Journal Software Market
That trajectory is meaningful for three categories of decision-makers:
Canopy Light Market
- Manufacturers seeking scale efficiencies and product differentiation
- Distributors and service providers building integrated recovery suites
- Healthcare institutions and payors evaluating inclusion in care pathways
Market dynamics shaping 2026 strategies
Our sector analysis identifies five converging dynamics companies must internalize before committing capital:
- Product innovation and material evolution: Manufacturers are diversifying from traditional glass cups into silicone, thermoplastic and hybrid systems that prioritize safety, durability, and user comfort. Innovations in pump ergonomics, magnetic attachments, and shock/heat-resistant materials are enabling broader clinical adoption and home-use positioning.
- Clinical integration and reimbursement signals: Cupping therapy is increasingly embedded within rehabilitation and pain-management protocols. Industry billing practices reference existing physical-medicine CPT codes in certain settings, and institutional purchasers (including public health systems) are evaluating reimbursement pathways — a trend that materially affects procurement strategies for clinics and device suppliers.
- Regulatory clarity and standards: Cupping kits continue to be regulated predominantly as Class I medical devices in major markets, with relevant ISO standards for air-extraction and glass cupping devices in place. This creates a baseline compliance expectation but also opens opportunities for early movers who obtain voluntary quality certifications and robust clinical claims.
- Channel and education ecosystem: Sellers that bundle education (continuing education units, practitioner training) with product offerings are winning higher retention and premium pricing, especially in practitioner-targeted segments.
- Fragmented competitive structure: Market concentration remains low relative to many medical-device subsegments. Our concentration indices indicate a fragmented supplier base, creating opportunity for consolidation and for specialized incumbents to capture niche premium roles.
What the PW Consulting report delivers — practical, actionable content
This study was built to guide real-world decisions. The full report includes:
- Detailed market sizing and trend validation (historical 2020–2025 and modeled forecasts 2026–2032), with sensitivity scenarios and upside/downside drivers.
- Proprietary forecast model delivered in Excel, enabling users to re-run scenarios after adjusting pricing, adoption curves, or regulatory assumptions.
- Supply chain maps and cost-driver analysis from raw materials to finished-packaging decisions, including labor, logistics, and tooling considerations.
- Channel and commercialization playbooks for clinic, sports-rehab, and direct-to-consumer (D2C) routes to market — including pricing benchmarks, bundling strategies, and education-led retention models.
- Regulatory and reimbursement navigators: step-by-step compliance checklists for major markets, ISO alignment guidance, and payer engagement briefs for institutional sales teams.
- Customer segmentation frameworks and buyer-persona profiles tailored to practitioners, physiotherapists, and informed consumers who buy at-home kits.
- Strategic M&A and partnership screening matrix highlighting target profiles for tuck-ins, technology acquisitions, and distribution alliances.
- Risk matrices, mitigation options, and contingency plans for supply shocks, regulatory shifts, and reputational risks related to clinical safety concerns.
- Primary interview insights: synthesized perspectives from practitioners, procurement officers, and senior product managers collected during our 2025–2026 fieldwork.
Competitive landscape — who to watch and why
The market features a mix of established equipment producers, specialized silicone and glass manufacturers, and distributors bundling education and clinical services. The landscape’s fragmentation, reflected in modest top-three and top-five concentration ratios, leaves room for brand differentiation and vertically integrated models.
- EarthSpa R&D (United States) — Known for handblown glass and in-house plastic pump systems, EarthSpa’s positioning centers on ’made-in’ quality and practitioner trust. Expect continued focus on premium clinical channels and design-protected products.
- Lhasa OMS (United States) — A diversified supplier with product lines spanning silicone, glass, and magnetic offerings; appeals to licensed acupuncturists and integrative health clinics via combined product-and-education programs.
- HawkGrips (United States) — Emphasizes dynamic cupping for sports recovery and clinical CEU-backed programs; a playbook for companies seeking to monetize education alongside hardware.
- Thysol US / FASCIQ (United States) — Targets fascia and massage therapy markets with premium silicone solutions; strong channel affinity with manual-therapy professionals.
- Kangzhu (China, via Taizhou Xinkang) — Original maker of classically engineered plastic vacuum systems and pumps; cost-competitive manufacturing with regulatory credentials in markets requiring Class I registration.
- Boen Medical (China) — Glass cupping specialist positioned for scale; relevant to buyers prioritizing traditional materials and lower-cost clinical inventories.
- MMT Cupping, Cupping International, Performance Health and others — A diverse group of suppliers and distributors that combine product breadth, clinical distribution networks, and rehabilitation-focused kits.
Recent product moves underline the market’s dual emphasis on performance and home-wellness adoption. Notable developments in 2025–2026 include expanded integrated recovery kits for physiotherapy, new ergonomic professional pumps, and refreshed silicone/magnetic product waves across Asia-Pacific. These moves validate our hypothesis that packaging, training, and system-level integration are as important as cup design itself.
Strategic implications: six priority actions for 2026
Based on our modeling and field interviews, companies should prioritize the following:
- Clarify target customer economics: Build P&L models for practitioner bundles versus D2C offerings; quantify lifetime value differences driven by recurring consumables and training revenues.
- Invest in validated clinical evidence: Short, focused clinical studies and documented case series will materially accelerate institutional adoption and payer conversations.
- Design supply resilience into product roadmaps: Dual-source critical components, standardize materials to reduce regulatory complexity, and consider regional assembly to shorten lead times.
- Differentiate through services: Offer CEU-accredited training, digital rehabilitation protocols, and telehealth-enabled onboarding to capture higher-margin accounts.
- Pursue pragmatic M&A and partnerships: Target acquisitions that fill distribution gaps, add clinical evidence capacity, or incorporate complementary modalities for integrated recovery kits.
- Prepare for regulatory and reimbursement evolution: Invest in compliance documentation, ISO alignment, and payer-engagement templates to move quickly if CPT coding and benefits change regionally.
How PW Consulting’s report accelerates execution
For strategy teams, the full report is a decision-enabler rather than an academic exercise. The integrated Excel model lets executives test: (a) price-elasticity in home versus professional channels; (b) the impact of unit-cost reductions from regional manufacturing; and (c) the ROI of bundling training with hardware. Our M&A screening tool surfaces targets aligned to four acquisition archetypes (scale, capability, channel, and technology) and ranks them against five execution risks.
Closing perspective and next step
The Worldwide Cupping Therapy Kits Market is moving from niche therapeutic practice toward broader clinical and consumer adoption. The path to 2026 is navigable for organizations that act now: solidify clinical credibility, build resilient supply and manufacturing strategies, and monetize services around hardware. Fragmentation creates opportunity — for first movers who integrate product, education, and clinical partnerships, and for investors seeking consolidation opportunities.
To access the full dataset, segmented forecasts, valuation matrices, and the downloadable forecast model, visit the PW Consulting report page. The detailed splits and proprietary financials are intentionally reserved for the comprehensive report to preserve client value and enable confident execution planning.
For detailed analysis of this topic, please visit the official page: Worldwide Cupping Therapy Kits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Conjunctivitis Ophthalmic Drugs Market Valued at USD 5,466.5 Million in 2025, Poised for Further Growth
By pmarketresearch, 2026-08-12
Worldwide Conjunctivitis Ophthalmic Drugs Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market intelligence on the Worldwide Conjunctivitis Ophthalmic Drugs Market synthesizes multi-year observed performance with scenario-driven forecasts to 2032. Our analysis shows a resilient expansion of the overall market from just over USD 4.2 billion in 2020 to USD 5.47 billion in 2025, with a continued upward trajectory across the 2026–2032 forecast window. The market’s compound annual growth rate (CAGR) over the forecast period stands at 5.51%, underpinned by persistent demand in allergic and infectious indications, product innovation, and an evolving competitive and regulatory landscape.
Worldwide Scanning Lenses Market
Why this report matters for 2026 strategy
-
Actionable foresight: We translate broad-market momentum into discrete strategic options that are executable within 12–24 months — from lifecycle management and portfolio prioritization to targeted M&A and market-entry sequencing.
RV Backup Power System Market -
Investment prioritization: The report frames where to allocate R&D and commercial resources to capture disproportionate value as category dynamics shift (e.g., branded innovation vs. generic displacement, novel delivery forms vs. traditional drops).
Worldwide Ball Joints Market -
Risk calibration: We quantify systemic exposures — regulatory timing, reimbursement hurdles, and API supply constraints — and map mitigation levers correlated with upside scenarios.
Report scope and practical contents
-
Market sizing and trend analysis: Year-on-year market sizing from 2020 through 2025, with forward projections through 2032. Our models reconcile historical sales, launch trajectories, and expected therapeutic substitution dynamics to produce base, upside, and downside cases.
-
Competitive benchmarking: Detailed company profiles, commercial footprint assessments, and capability matrices covering global innovators, specialty ophthalmology firms, and major generic/contract manufacturers.
-
Clinical and pipeline intelligence: Assessment of late‑stage assets, delivery technologies (including ocular inserts and intracanalicular systems), and the potential commercial impact of recently approved or launched products.
-
Regulatory, reimbursement & payer playbook: Jurisdiction-specific timelines and reimbursement sensitivities, plus recommended dossier content and real‑world evidence strategies to accelerate formulary access.
-
Go‑to‑market blueprints: Channel segmentation, clinician and patient adoption drivers, and tactical launch plans calibrated to diverse healthcare systems.
-
Commercial financial models: Scenario-ready revenue models and margin stress tests designed for M&A diligence, licensing negotiations, and internal capital allocation.
Note: In this briefing we present high-level conclusions and strategic guidance. The full report contains granular segment tables, country-level forecasts, product-level unit and value estimates, and downloadable financial models — access details are provided at the end of this release.
Market dynamics shaping 2026 decisions
-
Innovation in delivery formats is changing the clinical and commercial calculus. Intracanalicular inserts and long-acting formulations continue to gain attention for their adherence benefits, especially in allergic indications where episodic symptoms and patient compliance have historically limited therapeutic impact.
-
Genericization remains a major force. The recent acceleration of generic ophthalmic launches amplifies pricing pressure for established branded drops and shortens the effective exclusivity period for commodity anti-infectives and anti-allergy agents. This dynamic makes early lifecycle actions — such as formulation improvements, device-enabled delivery, and line extensions — strategically valuable.
-
Regulatory and reimbursement constraints differ significantly by product type. High-value differentiated products that deliver demonstrable clinical or economic value (e.g., reduced clinic visits, fewer antibiotic courses, or improved pediatric tolerability) retain stronger payer negotiating positions than incremental improvements in commodity drops.
-
Supply‑chain resilience for ophthalmic APIs is now table stakes. A concentrated API sourcing base for core molecules raises operational risk and necessitates contingency planning and supplier diversification for both branded and generic manufacturers.
Competitive landscape: implications for incumbents and challengers
The market exhibits moderate concentration: the leading three firms account for a meaningful share of value, and the top five control a clear majority of the market’s commercial heft. This structure creates both defensive advantages for incumbents and openings for focused challengers. Key dynamics include:
-
Established global players (e.g., companies with deep ophthalmic franchises and OTC/ Rx convergence) can leverage scale in distribution, clinical relationships, and regulatory experience to defend branded positions and accelerate new launches.
-
Specialty ophthalmology firms and innovative midsize players are the most likely sources of differentiated assets — whether novel molecules, biologics for severe allergic phenotypes, or device-integrated delivery systems. Strategic partnerships or licensing transactions with these players can be a rapid route to pipeline refreshment.
-
Large generics manufacturers and regional players are making the market more price-competitive at the base of the value chain, forcing branded companies to prioritize premium product segments and patient-centric differentiators.
Representative company positioning observed in our study:
-
Companies with established anti-allergy drops benefit from broad physician familiarity and strong retail presence, but face intensified generic erosion unless supported by new evidence or delivery innovations.
-
Firms active in anti-infectives continue to compete on speed of onset, preservative-free formulations, and cost-competitiveness — attributes that are decisive in acute care settings.
-
Specialty innovators focused on severe allergic conditions and novel delivery platforms are positioned to capture premium segments if they can secure favorable reimbursement and demonstrate measurable healthcare-system benefits.
Recent developments and strategic takeaways
-
Generic launches and approvals that expanded the availability of core anti-infectives increase the urgency for branded players to accelerate lifecycle programs and explore device differentiation or combination formulas.
-
Regulatory approvals for innovative formulations and new indications (including pediatric label extensions in select jurisdictions) create new commercial opportunities but also raise the bar for evidence generation and payer engagement.
-
Ongoing regulatory nuances — for example, procedural requirements associated with certain implants and pediatric insertion considerations — amplify the need for clinical training programs and tailored reimbursement strategies.
Recommended 2026 playbook
-
Prioritize portfolio triage: Identify high-return assets and deprioritize commodity lines unlikely to withstand intensified generic competition. Use our financial model to simulate outcomes under multiple pricing and market-access scenarios.
-
Invest selectively in delivery innovation: Intracanalicular inserts and extended‑release platforms can create durable differentiation. Evaluate partnership or acquisition targets that provide clinical credibility and rapid time-to-market.
-
Strengthen payer engagement: Develop dossiers that quantify system-level benefits (reduced clinic follow-ups, adherence-driven outcome improvements). Early engagement with key payers can materially improve market access timelines.
-
Secure API supply: Implement dual-sourcing strategies and contract manufacturing agreements to mitigate raw-material shortages and price volatility.
-
Adopt targeted M&A and licensing: Use bolt-on acquisitions to shore up gaps in therapeutic class coverage or to secure differentiated delivery technologies rather than broad, high-cost diversification.
How PW Consulting supports executive/action teams
-
Proprietary market and product models calibrated to real-world sales and launch evidence.
-
Rapid diligence packages for M&A screening, including red-team analysis and integration playbooks.
-
Regulatory and reimbursement route-mapping with bespoke payer evidence plans and KOL engagement strategies.
-
Commercial launch accelerators covering pricing, distribution, and specialist training programs tailored to ophthalmology stakeholders.
Our full Worldwide Conjunctivitis Ophthalmic Drugs Market report contains the granular, actionable data and the downloadable financial models necessary to execute the above recommendations. For senior teams preparing 2026 budgets, the report serves as both a tactical manual and a strategic scoreboard: it translates market momentum into high-confidence choices while preserving the detailed segment intelligence your teams require to operationalize those choices. To request the complete report, data tables, and a tailored briefing, please visit our publication page or contact PW Consulting’s Ophthalmology Practice.
For detailed analysis of this topic, please visit the official page: Worldwide Conjunctivitis Ophthalmic Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ovum Egg Banking Market Valued at USD 5,464.34 Million in 2025, Poised to Reach USD 12,462.51 Million by 2032 at a 12.48% CAGR
By pmarketresearch, 2026-08-12
Worldwide Ovum Egg Banking Market — Strategic Imperatives for 2026
PW Consulting’s new market study, “Worldwide Ovum Egg Banking Market (Base year 2025; Forecast 2026–2032)”, synthesizes proprietary models, primary interviews and regulatory analysis to deliver a decision-grade briefing for executive teams preparing strategies for 2026. The ovum egg banking market has moved from a high-growth niche into mainstream strategic planning for fertility providers, employers and investors. Our macro modelling shows the market expanding from roughly USD 3.12 billion in 2020 to USD 5.46 billion in 2025, and, under our central scenario, accelerating to a multi‑billion-dollar industry by 2032 at a compound annual growth rate (CAGR) of 12.48% (USD million basis). This release highlights the report’s strategic value while deliberately withholding the granular segmented metrics that are available in the full study.
Red Cap Station Market
Why 2026 Matters: Regulatory, Clinical and Commercial Catalysts
-
Regulatory clarity and professional guidance have shifted the risk calculus. Updated positions from leading professional bodies in late 2025 and 2026 affirm planned oocyte cryopreservation as ethically permissible for reproductive planning and explicitly contextualize medical preservation for patients facing gonadotoxic therapy. These developments reduce ethical friction and support broader adoption by clinics and health systems.
Worldwide Anchor Windlass Market -
Reimbursement and coding regimes remain a complex but addressable barrier. Current procedural terminology includes codes for cryopreservation and thawing; however, donor egg acquisition and many storage costs are still predominantly out‑of‑pocket. Payer engagement strategies that target oncology mandates and employer-sponsored fertility benefits will be decisive for commercial scale.
Bioenergy with Carbon Capture and Storage Market -
Clinical evidence and real-world program outcomes are maturing. Leading clinics now report high-throughput freezing programs and growing numbers of live births from stored oocytes, translating to more predictable clinical success rates and better patient counseling — an essential commercial advantage for early movers.
-
Demand drivers are compounding: demographic trends, delayed family formation, increasing awareness of fertility preservation, and rising employer benefits are creating durable end-market expansion that rewards investment in patient experience, capacity and data-driven pricing.
How This Report Informs 2026 Decisions
Executives facing 2026 planning cycles require more than headline growth numbers — they need a roadmap that links market shape to executable moves. PW Consulting’s report provides that bridge through:
-
An accessible, auditable market model (USD million) covering historicals (2020–2025) and a detailed forecast to 2032, including high/low scenarios and sensitivity analyses that stress-test key assumptions.
-
Actionable go-to-market playbooks for clinic networks, dedicated cryobanks and integrated fertility platforms — including pricing levers, bundled service structures and differentiated service propositions (donor egg offerings vs. self-oocyte preservation).
-
A regulatory and reimbursement compass that maps coding, state-level fertility preservation mandates, and the practical implications of professional guidance for informed consent, marketing and payer contracting.
-
Commercial diligence assets: buyer/seller scorecards for M&A, an M&A heatmap identifying consolidation corridors, and a data room checklist for transaction readiness.
-
Operational toolkits: capacity planning templates for lab buildouts, quality and accreditation checklists, and a logistics/cold-chain risk register tailored to oocyte transport and cross-border distribution.
-
Patient journey diagnostics and digital engagement frameworks to increase conversion and lifetime value — from employer benefits enrollment to post-thaw clinical pathways and outcomes tracking.
Competitive Landscape — Who’s Competing and How
The market combines specialized cryobanks, national clinic networks and vertically integrated fertility groups. Key players covered in the report include specialized international banks, national leaders and clinic networks that operate both freezing programs and distribution channels. Representative companies profiled include Cryos International A/S (Denmark), California Cryobank (USA), Donor Egg Bank USA, ReproTech LLC, Cryo-Cell International Inc., CCRM Fertility, IVIRMA Global, Shady Grove Fertility, Kindbody, Genea Pty Limited, Boston IVF, Monash IVF Group, Fairfax EggBank and Extend Fertility.
Our competitive analysis shows a fragmented supplier base where specialization, service quality and geographic reach — rather than scale alone — drive premium positioning. Clinical credibility, validated outcomes and robust donor-matching technologies have emerged as differentiators. Organizations that combine laboratory excellence with superior digital patient experiences and strong clinician partnerships capture higher margins and stickier demand.
Market concentration metrics in the study underscore the fragmentation and the room for consolidation: a structure that still rewards well‑executed roll-up strategies, strategic partnerships with clinic networks, and white‑label service agreements for hospital systems.
Priority Strategic Plays for 2026
Based on our scenario modelling and interviews with payers, clinicians and operators, PW Consulting recommends the following priority actions for 2026:
-
Accelerate capacity with quality governance: invest selectively in lab capacity and quality systems that meet international accreditation standards. Build redundancy into cold‑chain logistics to prevent catastrophic losses and reputational damage.
-
Pursue targeted partnerships with oncology centres and employer benefit providers: embed oocyte preservation into clinical pathways and employer benefit packages to capture under‑served medical indications and voluntary uptake in working populations.
-
Differentiate through data and outcomes: develop registries and outcome dashboards that enable transparent counseling and support payer negotiations. Demonstrated live-birth outcomes will materially improve conversion rates and pricing power.
-
Consider roll-up and bolt-on acquisitions in fragmented regional markets: consolidation can deliver scale benefits in procurement, standardized quality and a branded donor database — but acquirers must prioritize integration of clinical protocols and regulatory compliance.
-
Design consumer-centric pricing and storage bundles: move from one-off storage fees toward subscription or outcome‑linked models where feasible, and pilot risk-sharing arrangements with high-volume clinic partners.
-
Embed ethical and compliance leadership: proactively adopt enhanced informed-consent protocols and transparent donor governance consistent with leading society guidance to reduce legal and reputational risk.
Risk Scenarios and Mitigation
Key downside scenarios we model include abrupt payer policy shifts that limit coverage for elective preservation, technological breakthroughs that accelerate obsolescence of existing storage methods, and heightened regulatory scrutiny around donor anonymity and cross-border distribution. Mitigation strategies include diversified revenue mixes that anchor medical indications, staged capex aligned to demand triggers, and active policy engagement to shape reimbursement pathways.
Practical Planning Timelines for 2026
-
0–6 months: validate demand via clinic pilots, align compliance and informed consent frameworks, and build a payer engagement plan focused on oncology mandates and employer benefits.
-
6–18 months: scale lab and cold-chain upgrades where demand is proven, roll out digital donor-matching and patient engagement platforms, and pilot innovative pricing models.
-
18–36 months: execute M&A or partnership strategies to consolidate regional strength, integrate outcomes registries for commercial differentiation, and expand cross-border distribution under robust governance.
What’s Behind the Numbers — Methodology Highlights
The report’s base year is 2025 and it leverages five years of historical data (2020–2025) to inform a forward forecast to 2032. Our model uses a bottom-up service taxonomy, triangulates utilization with demographic and oncology incidence trends, and applies scenario-based adoption curves to reflect regulatory and reimbursement uncertainty. All values are reported in USD (USD million unless otherwise noted). The study couples primary interviews with clinic operators, cryobank managers, payers and patient‑advocacy groups to test assumptions and to surface tactical barriers to scale.
Accessing the Full Intelligence
This article presents the strategic frame and actionable themes drawn from PW Consulting’s full market study, while intentionally withholding granular regional, service-type and end‑user splits that are included in the complete deliverable. The full report contains detailed segment-level models, company market shares, pricing matrices, and proprietary acquisition screening tools that senior leaders can deploy directly in 2026 planning cycles.
To obtain the full report or a tailored executive briefing for your organisation, contact PW Consulting’s Ovum Egg Banking practice. The comprehensive dataset and playbooks will enable investment committees, commercial heads and operational leaders to move from market awareness to implementation-ready programs as they plan for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Ovum Egg Banking Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com