

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Anti-Emetic Drug Market Poised to Expand at a 4.85% CAGR Through 2032
By pmarketresearch, 2026-08-18
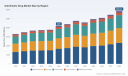
Worldwide Anti-Emetic Drug Market — 2026 Strategic Preview
PW Consulting’s newest market intelligence brief on the Worldwide Anti‑Emetic Drug Market frames the business choices that will determine winners and losers in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study places the market’s 2025 baseline at USD 4,200 Million and models a compound annual growth rate (CAGR) of 4.85% through the forecast period. Our analysis projects continued expansion, with market upside tied to therapeutic innovation, evolving standard-of-care in oncology, and the balance between branded lifecycle strategies and aggressive generic competition.
Worldwide Portable Storage Containers Market
Why 2026 is a Strategic Inflection Point
-
Convergence of clinical demand and commercial pressure: Oncology treatment volumes, evolving emetogenicity profiles of newer regimens, and a steady baseline of post‑operative care sustain demand—yet pricing dynamics and generic penetration are intensifying margin pressure for incumbent brands.
Oxidation Stability Reactor Market -
Innovation vs. commoditization: Late‑stage clinical activity and extended‑release/pediatric formulations are creating new proprietary slices of value, while mature 5‑HT3 agents face entrenched generic competition that materially compresses unit pricing.
Plumbing Fixtures Market -
Regulatory and reimbursement shifts: Targeted safety risk‑management (for example, REMS obligations associated with certain NK1 agents), changes to provider reimbursement mechanisms, and transparent ASP listings are shifting commercial negotiating power toward large purchasers and payers.
-
Supply chain resilience and cost control: The recent resolution of active ingredient shortages demonstrated how supply shocks can rapidly change competitive availability and create tactical windows for firms with flexible manufacturing or partnering strategies.
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
Beyond headline sizing and a responsible forecast, PW Consulting’s report is structured to be directly usable by strategy, commercial, and BD teams preparing decisions in 2026. Highlights include:
-
Proprietary market model — transparent methodology and sensitivity levers you can re-run for alternative assumptions (pricing, penetration, therapy mix).
-
Scenario-based forecasts — base, conservative and upside cases that stress test regulatory, reimbursement and clinical outcomes.
-
Competitive playbooks — battle-tested GTM options for branded innovation, generic defense, and regional licensing.
-
Clinical pipeline heatmaps — indication and formulation prioritization across late‑stage NK1 and 5‑HT3 innovation.
-
Regulatory & reimbursement matrix — country-by-country guidance for label strategy, REMS compliance, HTA engagement and payer negotiation tactics.
-
Commercial checklists — pricing/contracting templates, hospital formulary engagement scripts, and value‑dossier outlines for oncology care pathways.
-
Operational playbooks — supply chain risk maps, contingency manufacturing options, and cost-to-serve analyses for low‑price generic networks.
Note: This public summary intentionally omits our detailed subsegment tables and underlying numeric splits. The full report contains the complete breakdowns and downloadable datasets essential for transaction diligence and market-entry planning.
Actionable Strategic Recommendations for 2026
-
Prioritize portfolio rationalization. Reassess low-margin legacy assets and redeploy commercial resources into high-value formulations (e.g., extended‑release injectables, fixed‑dose NK1/5‑HT3 combinations, pediatric formulations) where reimbursement is accessible.
-
Defend branded value early. For companies with lead products, accelerate label expansions and health economics studies to lock in hospital formularies before further generic entry erodes price and volume.
-
Adopt segmented pricing tactics. Use tender analytics and payer‑specific value propositions (e.g., bundle pricing for oncology cycles, outcome‑linked arrangements for high‑acuity care) to protect ASP and margin.
-
Build flexible supply chains. Maintain dual-source APIs for vulnerable molecules and qualify co‑manufacturing agreements in regions with spare capacity to avoid repeat shortages.
-
Look for bolt‑on M&A and licensing. Mid‑market generics manufacturers and regional specialty players remain attractive targets to secure route-to-market and cost advantages without full greenfield investments.
-
Invest selectively in pediatric and supportive-care niches. Recent regulatory approvals demonstrate clear demand and differentiation potential for age-appropriate formulations.
-
Prepare for regulatory constraints. Incorporate REMS and other post‑market commitments into early price and access planning to avoid commercialization delays.
Competitive Landscape — What Executives Need to Know
The anti‑emetic space remains a dual ecosystem: global innovators pursuing differentiated formulations and multi‑national generics firms aggressively defending share. Market concentration is meaningful but not prohibitive — our concentration metrics indicate a moderate top‑tier presence that leaves attractive opportunity for nimble challengers and strategic alliances (CR3 ≈ 38.5%, CR5 ≈ 52.2%).
-
Innovator dynamics: Merck (Emend) continues lifecycle management via label expansions; Helsinn’s combo strategies (e.g., fixed‑dose NK1/5‑HT3) and successful Phase III programs are renewing clinical options; Roche, Pfizer and GSK maintain franchise depth across established 5‑HT3 molecules and hospital relationships.
-
Specialty innovators: Heron’s extended‑release formulations and recent pediatric approvals illustrate the commercial payback from formulation innovation even in crowded classes.
-
Generics and scale players: Teva, Viatris (Mylan), Sandoz and regional players like Dr. Reddy’s ensure rapid price competition upon patent expiry, and their manufacturing scale underpins resilience during shortages.
-
Recent, material moves: approvals and positive trial readouts in 2023–2024 expanded tactical choices for market incumbents and entrants, and generic launches have already altered competitive access in major markets.
Regulatory, Pricing and Supply Signals to Monitor
-
REMS and safety programs can materially affect launch timing and commercial reach for certain NK1 agents; compliance costs should be baked into NPV models.
-
Historic patent expirations have shown how quickly branded price power can erode; generics compression (>80% in mature cases) remains the default tail risk.
-
Payer transparency mechanisms (CMS ASP listings and related reimbursement files) create public reference prices that shorten negotiation cycles and influence hospital purchasing behavior.
-
Supply disruptions are no longer hypothetical. The 2023 ondansetron shortage highlights the need for pre‑qualified secondary sources and inventory buffers for critical hospital‑administered formulations.
Risk Scenarios — What Could Move the Market Off‑Model
-
Regulatory tightening: expanded REMS or unforeseen safety signals could reduce accessible patient populations for specific agents and delay label extensions.
-
Clinical disappointments: late‑stage failures for proprietary NK1 candidates would disproportionately affect branded growth scenarios.
-
Accelerated genericization: faster-than‑expected patent challenges or additional compulsory licensing in key markets would compress revenue and increase price-based competition.
-
Supply shocks: API shortages or manufacturing site disruptions would advantage firms with diversified contract manufacturing and penalize single‑source suppliers.
How to Use This Report in the First 90–180 Days
-
90 days — Strategic alignment: run an internal workshop using our scenario outputs to set priorities (e.g., defend, divest, invest). Use our commercial checklists to prioritize five hospital systems or payers for immediate engagement.
-
180 days — Execution and partnerships: launch targeted pilots (pricing pilots, formulary dossiers), initiate supply‑side contingency contracts, and begin diligence on 1–3 identified M&A or licensing targets using our screening template.
-
360 days — Scaling and optimization: roll out successful pilots regionally, finalize partnerships, and formalize lifecycle management plans for priority assets using our regulatory timelines and HEOR playbook.
Conclusion — Where PW Consulting Adds Value
For executives making portfolio, M&A, or commercial access decisions in 2026, the anti‑emetic market presents both stable demand and strategic complexity. PW Consulting’s report combines transparent macro sizing, scenario analytics, executable playbooks and a competitor-signal map that together shorten decision cycles and reduce execution risk. We deliberately present a high‑signal executive summary here while withholding granular subsegment tables and downloadable models to ensure clients receive the full, usable intelligence necessary for transaction-grade decisions.
To access the full dataset, model files, and the complete segmentation and regional breakdowns required for due diligence and operational planning, please visit the PW Consulting report page for the Worldwide Anti‑Emetic Drug Market.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Emetic Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Luggage Storage Locker Market Surges to USD 1,250.0 Million in 2025
By pmarketresearch, 2026-08-18
Worldwide Luggage Storage Locker Market — Strategic Preview for 2026 Decision-Makers
As travel resumes its multi-speed recovery and urban venue operators seek new ways to monetize footfall and improve customer experience, luggage storage lockers have moved from niche amenity to strategic infrastructure. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — shows a market that has grown meaningfully over the last half-decade and is poised for steady expansion. Our headline numbers: the global market climbed from roughly USD 890 million in 2020 to about USD 1,250 million in 2025, and PW’s modeling projects continuation to nearly USD 1.84 billion by 2032, reflecting a 2026–2032 compound annual growth rate (CAGR) of approximately 5.66%.
Worldwide Desktop Search Software Market
Why this matters for boards and C-suite teams in 2026
-
Capital allocation: The category’s predictable mid-single-digit CAGR and clear technology-driven migration mean capital allocation timelines can be confidently staged — initial deployments to validate use cases, followed by scale budgets for networked rollouts or partnerships.
Worldwide Bone Marrow Aspiration Device Market -
Operational design: Self-service smart lockers materially reduce recurring staffing needs while unlocking 24/7 revenue windows. For operators focused on margin improvement, lockers represent a low-touch revenue stream with multiple adjacent monetization options (advertising, ancillary services, partnerships with last-mile retail or tourism platforms).
Worldwide High Pressure Boiler Feed Pumps Market -
Risk management: Compliance exposures around personal data handling and payments are now table stakes. Decision-makers must bake CCPA, GDPR and PCI-DSS considerations into procurement and integration timelines to avoid costly retrofits.
Market dynamics and technology trends shaping 2026 strategies
-
Smartification and cloud orchestration. The category is accelerating toward IoT-first architectures: cloud-based locker management, real-time utilization analytics, remote diagnostics and API-driven integrations with booking and payment ecosystems. These capabilities drive network economics — the more integrated the locker becomes within a city’s mobility and tourism stack, the higher the yield per unit.
-
Payment and security convergence. Expect rising demand for lockers that combine secure payment stacks (PCI-DSS-ready), encrypted access logs and modular hardware that supports both electronic and mechanical fail-safes. This dual approach addresses regulatory and vandalism risk without sacrificing the convenience users expect.
-
Service-layer partnerships. Strategic tie-ups between locker OEMs and consumer-facing platforms (travel agents, luggage-on-demand services, parcel networks) are already unlocking densification opportunities in dense urban cores and transit hubs. These partnerships shift the commercial model from one-off sales to recurring service revenues for both vendors and hosts.
-
Fragmentation with opportunity. The market remains fragmented — top vendors account for a modest share of total value, leaving latitude for regional specialists, vertical-focused providers and systems integrators to capture local scale. This low consolidation level creates acquisition and partnership opportunities for players seeking faster route-to-scale.
Regulatory and operational noise that will shape vendor selection
-
Data protection regimes (GDPR in the EU, CCPA-style statutes in the U.S.) now mandate encryption, careful access-log retention policies and vendor-side contractual commitments. Tender teams must include data protection officers at procurement gates.
-
Payment security standards: lockers that accept cards or digital payments need validated PCI-DSS controls; ensuring this is in place at the outset avoids business interruption when transactional services go live.
-
Labor and operating cost dynamics: automated lockers reduce staffing needs and offer predictable remote-management savings — a compelling argument in markets where hourly labor inflation and staffing constraints raise operating costs.
Competitive landscape — who matters and how to think about partners
PW’s competitive mapping identifies a diverse field of incumbents and specialists. From multinational security groups with broad access-control portfolios to agile IoT start-ups, each vendor presents a distinct value proposition.
-
LockTec GmbH (Germany) : Strong in transportation venues, LockTec’s Locksafe offering emphasizes robust mechanical options alongside touchscreen-enabled electronic units. For operators prioritizing durability in high-abuse environments (rail hubs, major stations), LockTec’s modular and vandal-resistant hardware is a practical fit.
-
ASSA ABLOY (Sweden) : As a global access-control leader, ASSA ABLOY brings scale, enterprise-grade security and mature product lines (including package and smart-locker systems). Organizations that need proven integration with broader door and access ecosystems will consider ASSA ABLOY for enterprise consistency and support networks.
-
American Locker & Salsbury Industries (USA) : Both bring manufacturing depth and proven, customizable mechanical/electromechanical designs. Their strength is in tailoring size profiles and finishes for institutional deployments where aesthetic and build standards matter.
-
Vecos (Netherlands) : Representative of the new wave of cloud-native locker providers, Vecos emphasizes IoT-centric management, flexible API access, and SaaS billing models — a fit for operators aiming to monetize via platform partnerships rather than one-off hardware sales.
-
Godrej & Boyce (India) : Offers a mix of high-security mechanical and electronic solutions and retains strong distribution advantages in Asia. For rollouts in emerging markets where local service coverage and compliance with local standards are critical, regional champions like Godrej accelerate deployment timelines.
-
Quadient (France) : Through Parcel Pending and strategic partnerships with consumer-facing luggage services, Quadient demonstrates how parcel locker networks can be repurposed or co-branded for luggage use, delivering fast network density in urban and retail locations.
-
DeBourgh Manufacturing, Alpha Locker Systems, Locker & Lock, Vlocker : These vendors cover the mid-market with durable, customizable modules, while offering varying degrees of IoT enablement and systems-integration support — often chosen by property managers and retail operators seeking tailored deployments without full enterprise overhead.
Recent market moves confirm the strategic direction: Quadient’s multi-phase partnerships to embed parcel-locker networks into luggage services and regional entrants launching tourism-focused offerings demonstrate how platform-led distribution and local-market activation will be central to growth over the next 12–18 months. Corporate teams evaluating vendors should therefore prioritize not just hardware specs, but the partner’s channel strategy, integration API maturity and ability to operate as a service-layer collaborator.
What PW Consulting’s report delivers — practical tools and decision-ready content
Our study is built for commercial leaders, infrastructure planners and strategic investors who need executable insight rather than descriptive noise. The report includes:
-
Market-sizing and forecast models (2020–2032), with scenario-driven sensitivity analyses to stress-test volume and revenue assumptions under alternative travel recovery and adoption curves.
-
Vendor scorecards and an impartial vendor-selection framework covering security, uptime guarantees, API maturity, payment compliance, TCO and lifecycle service economics.
-
Procurement-ready RFP templates and due-diligence checklists that incorporate data protection, PCI-DSS and local regulatory requirements — formatted for immediate use in tender processes.
-
Deployment playbooks with site-selection heuristics, utilization thresholds for economic viability, modular rollout sequencing and a simple TCO calculator that models capex vs. SaaS scenarios and expected payback periods.
-
Commercial partnership playbooks that outline revenue-share models, co-branding opportunities with parcel and tourism platforms, and monetization levers to drive higher yield per unit.
-
Case studies highlighting quick wins and failure modes from recent rollouts — valuable for operations teams to accelerate time-to-stable-state post-installation.
Strategic playbook — five actions for 2026 implementation
-
Prioritize API-first vendors for greenfield network plays. When your objective extends beyond a single site to a city or region, the ability to integrate booking platforms, payment gateways and analytics is critical.
-
Design procurement around compliance. Insist on demonstrable GDPR/CCPA and PCI-DSS controls in contract language, and require vendor liability caps to reflect data-processing risk.
-
Pilot for utilization data before scaling. Run time-boxed pilots in representative venue types to gather utilization and revenue-per-unit metrics; use those inputs to calibrate rollouts and avoid over-deployment.
-
Explore partnership pathways with parcel or tourism networks. Co-locating luggage services with parcel locker networks or booking platforms accelerates user acquisition and reduces customer acquisition costs.
-
Model hybrid ownership and service models. Consider capex-lite SaaS or revenue-share models where vendors operate and maintain the network — useful when speed-to-market and operator cashflow are constraints.
Conclusion — the strategic window in 2026
With a predictable mid-single-digit growth trajectory and clear technology and partnership playbooks, luggage storage lockers represent an infrastructure category that rewards thoughtful, staged investment. The market’s fragmentation creates room for regional champions, platform players and vertically integrated operators to co-exist and prosper. Boards and investment committees should treat lockers not as an isolated amenity, but as a node in mobility, retail and tourism ecosystems — one that can deliver recurring, low-touch revenue if deployed with the right vendor, compliance posture and partnership strategy.
PW Consulting’s full Worldwide Luggage Storage Locker Market report contains the detailed segmentations, regional rollouts, vendor benchmarking matrices and downloadable models you will need to execute in 2026. For the complete data set, granular segmentation and procurement-ready materials, visit PW Consulting’s report page or contact our industry practice for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Luggage Storage Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Reinforced Polypropylene Market to Expand at a 6.28% CAGR Through 2032
By pmarketresearch, 2026-08-18
PW Consulting Releases Strategic Outlook: Worldwide Reinforced Polypropylene Material Market — A Decision-Maker’s Playbook for 2026
PW Consulting’s new market research brief on the Worldwide Reinforced Polypropylene (R-PP) material market combines forward-looking modeling with practical, executable guidance for senior executives preparing strategy, procurement, and investment plans for 2026. Built on a multi-year historical base and a 2026–2032 forecasting horizon, the study highlights a resilient market trajectory (a compound annual growth rate of 6.28% across the forecast window) and a continuing expansion in absolute market value. These headline metrics underscore the structural momentum behind reinforced polypropylene—but as this briefing explains, the 2026 planning cycle will be shaped by supply-side volatility, regulatory noise, and a competitive landscape that rewards both scale and specialty innovation.
Worldwide Account Takeover Protection Market
Market Trajectory and Competitive Density: What the Headlines Show
After steady recovery and expansion in the early 2020s, the reinforced polypropylene market reached a substantial size in the report’s base year, and our forecast points to meaningful incremental growth by the end of the forecast window. The industry sits in a middle-of-the-road concentration profile: the three largest firms hold a noticeable but not dominant share of global supply, and the five largest firms still leave ample room for regional leaders and specialized compounders to capture value. In short, the market rewards both scale-driven propositions and nimble, technology- or application-focused plays.
Telemedicine Integrated Consultation Vehicle Market
Why 2026 Is a Pivot Year for R-PP Strategy
-
Raw-material pressure is front-and-center. Resin and reinforcement inputs (notably polypropylene and glass fiber) represent the lion’s share of production cost for glass-fiber-reinforced PP systems. Recent cycles show that feedstock and fiber pricing moves transmit into compound economics quickly, compressing or expanding margins depending on pass-through dynamics and contractual structures.
Intra-Array Submarine Cable Market -
Regional supply imbalances and tariff dynamics are changing the calculus of sourcing. In several major producing markets, feedstock capacity growth has created price pressure at times, while trade measures implemented in 2025 introduced uneven tariff exposure across polymer supply chains. These factors combine to increase the value of diversified sourcing, nearshoring options, and strategic inventory policies.
-
Product innovation is bifurcating competition. Large integrated producers are leveraging compounding scale and sustainability messaging, while specialty compounders focus on long-fiber thermoplastics, modular formulations, and additive-enhanced grades tailored to demanding automotive and industrial applications. Recent product introductions across the industry indicate active R&D pipelines and faster time-to-market for differentiated reinforced grades.
Actionable Contents of the Report (Practical, Not Just Theoretical)
PW Consulting’s report is designed for executives who need actionable inputs, not just descriptive statistics. Key practical deliverables include:
-
A robust forecasting engine with scenario levers (price shocks, tariff cases, and demand adoption curves) that let teams stress-test procurement and pricing strategies under plausible 2026 conditions.
-
Raw-material cost mappings with sensitivity analysis: how variations in propylene and glass-fiber costs affect compound economics, and templates for contract clauses and hedging approaches that protect margins.
-
Supply-chain heatmaps and sourcing playbooks for footprint optimization—covering nearshoring, toll compounding partnerships, and contingency inventory models designed for manufacturers and OEMs.
-
Competitive scorecards and capability matrices evaluating compounding technologies (short glass vs. long glass, mineral and carbon reinforcements), sustainability credentials, and go-to-market strengths for leading producers and regional specialists.
-
M&A and partnership trackers identifying likely consolidation targets, capability-acquisition opportunities, and JV structures that accelerate access to application-specific reinforced PP grades.
-
Regulatory-impact dossiers that map tariff, recycling, and product-restriction risks to commercial outcomes—equipped with play-tested mitigation measures for procurement and commercial teams.
Competitive Landscape: Patterns to Watch
The supplier topology in reinforced polypropylene features several distinctive archetypes. Global integrated producers maintain advantages in scale, feedstock integration, and the ability to offer full-spectrum resin + compound solutions. Examples include multinational petrochemical majors who pair compounding capacity with global distribution. At the other end of the spectrum, regional and specialist compounders—those concentrating on engineered thermoplastic solutions, long-fiber thermoplastics (LFT), and custom formulations—compete on speed, customization, and close OEM relationships.
Key industry players profiled in the report include multinational producers with advanced compounding capabilities and sustainability programs; large regional chemical groups expanding LFT and reinforced portfolios; and nimble compounders focused on engineered grades and just-in-time supply. Notable recent product and collaboration moves—from long-fiber thermoplastic launches to additive-enhanced high-performance grades—illustrate an active innovation cycle and a marketplace receptive to differentiated performance offerings.
For decision-makers, the implication is clear: procurement and product-development strategies need to be multi-track. Leverage scale and integrated suppliers where total-cost economics favor volume and consistency; engage specialty compounders or co-development partners where technical performance or rapid customization is a priority.
Regulatory and Raw-Material Dynamics: Tactical Responses for 2026
-
Cost-pass-through and contract redesign: Given that resin and reinforcement costs drive the bulk of production expense, revise supply agreements to include clear indexation mechanics, trigger clauses, and shared-risk provisions for extreme price moves.
-
Tariff-aware sourcing: With recent trade measures selectively impacting polymer supply chains, evaluate sourcing alternatives and tariff-engineered routes. Small changes in routing or HS-code classification can materially affect landed costs.
-
Recycling and circularity as risk mitigators: Circular feedstocks and mechanically/chemically recycled resins are becoming both regulatory obligations and commercial differentiators. Investment in compatible compound formulations will increasingly protect revenue and margin in regulated markets.
Strategic Imperatives for 2026 Decision-Makers
-
Adopt scenario-based procurement: build at least three supply scenarios (base, upside on oversupply-driven price dips, and downside on feedstock tightening) and stress-test working capital and margin impacts.
-
Prioritize product partnerships: co-develop LFT and additive-enhanced R-PP grades with OEMs to capture higher-value system-level wins (lightweight structures, integrated assemblies, and electrification components).
-
Expand supplier diversification—not only geographically, but across the supply archetypes (integrators, regional compounders, specialist toll manufacturers).
-
Embed sustainability metrics into sourcing and product roadmaps to anticipate regulatory shifts and to access premium demand pockets seeking recycled or lower-carbon materials.
-
Use competitive intelligence to identify M&A or partnership targets—focus on specialty compounders with differentiated IP, or regional players that improve logistics and reduce tariff exposure.
-
Lock in flexible manufacturing and tolling arrangements to speed new-grade commercialization while limiting capital outlay in uncertain markets.
How PW Consulting Supports Implementation
PW Consulting extends the report with targeted advisory services and deliverables tailored to executive needs in 2026, including: bespoke procurement optimization workshops; supplier due-diligence playbooks and scorecards; transaction advisory for bolt-on acquisitions and joint ventures; and dynamic dashboards that convert the forecast engine into decision-ready visuals for procurement, commercial, and engineering teams. Our analysts also run war-gaming sessions to simulate tariff and supply shocks, enabling executive teams to refine escalation procedures and contingency playbooks.
Closing: Data Depth, Tactical Utility—Full Datasets Available
This briefing signals the breadth and depth of analysis included in the full Worldwide Reinforced Polypropylene Market report. The study provides detailed segmentation tables, supplier scorecards, granular application and regional demand modeling, and downloadable datasets that are intentionally retained behind the full report to preserve commercial value and analytical integrity. For procurement leaders, product strategists, M&A teams, and investors, the full report unlocks the segmented demand profiles, supplier economic models, and market-share matrices necessary to translate the strategic imperatives outlined here into operational plans for 2026.
To access the full dataset, scenario tools, and company-level intelligence, consult the official PW Consulting report page and arrange a briefing with our R-PP practice leads.
For detailed analysis of this topic, please visit the official page: Worldwide Reinforced Polypropylene Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Disposable Color Contact Lenses Market Tops USD 3,450 Million in 2025, Poised for Strong Growth
By pmarketresearch, 2026-08-18
Worldwide Disposable Color Contact Lenses Market: Strategic Preview for 2026 Decision‑Making
PW Consulting’s latest market research brief on the Worldwide Disposable Color Contact Lenses market provides a focused strategic primer for executive teams planning 2026 investments and market plays. The global market—measured at a 2025 base year value of approximately USD 3.45 billion (revenue unit: Million USD)—is positioned for accelerated expansion in the coming cycle. Our model projects a compound annual growth rate (CAGR) of 8.7% over the 2026–2032 forecast window, reaching a market size in excess of USD 6.1 billion by 2032 under the baseline scenario. This preview synthesizes the actionable implications of that trajectory for product, regulatory, commercial and M&A strategies, while preserving the detailed segment-level datapack for subscribers and report purchasers.
Variable Inductance Shunt Reactors Market
Why this market matters for 2026 strategy
- Scale and momentum: Mid‑2020s demand dynamics demonstrate both resilient core replacement demand and an expanding addressable market driven by cosmetic adoption, new toric offerings, and broader retail distribution models.
- Technology inflection: Advances in materials (silicone hydrogel blends, high‑water formulations), pigmenting techniques for natural appearance, and integrated moisture systems are reshaping product differentiation.
- Regulatory and label complexity: Although many color lenses are positioned as cosmetic, regulators treat them as medical devices; obtaining and maintaining 510(k) clearance (or equivalent) and meeting ISO biocompatibility standards are table stakes for scale players.
- Consolidation opportunity: Market concentration measures indicate meaningful consolidation among top suppliers—creating both competitive pressure and M&A pathways to quickly scale capabilities or enter adjacencies.
What the numbers tell us (high‑level)
Our top‑line market model uses historic sales and channel indicators through 2025 as the foundation for the 2026–2032 forecast. The projected 8.7% CAGR reflects a mix of continued replacement demand for daily‑disposable formats, incremental premiumization (higher ASPs for specialty or toric color lenses), and channel migration to omnichannel retailing. Measured concentration metrics also matter: the top three firms control a majority share of the market, and the top five push that concentration above two‑thirds—conditions that make competitive actions by leading incumbents (and entrants backed by capital or strong regulatory positioning) critical to market dynamics.
Medical Protective Textiles Market
Practical content inside the full report
For strategy teams preparing 2026 budgets, PW Consulting’s full study provides an executable toolkit—not simply a forecast. Highlights include:
Worldwide Sugar Candy Market
- Proprietary market model (Excel) with scenario toggles for ASP, channel mix shifts, and regulatory lag assumptions suitable for M&A diligence and capital planning.
- Go‑to‑market playbooks by channel (online retail, optical networks, clinical channels) with measured conversion and margin assumptions calibrated to 2020–2025 performance trends.
- Regulatory and clinical roadmap templates: stepwise timelines for FDA 510(k) submissions, ISO 10993 biocompatibility programs, and post‑market surveillance structures tailored to cosmetic vs. prescription positioning.
- Product development checklists covering material selection, pigment stability testing, toric stabilization engineering and sterility & shelf‑life validation protocols.
- Competitive profiles and capability heat maps for major players, including technology strengths, geographic footprints, certification status, and likely near‑term moves.
- Commercial scenarios articulating pricing levers, bundling approaches, and payor engagement where specialty clinical indications may unlock reimbursement.
- M&A playbook and valuation sensitivity tables that align technology/IP risk with revenue synergies and time‑to‑market assumptions.
Competitive landscape: positioning and implications
The competitive set spans global incumbents with diversified disposable portfolios and smaller specialists that have used product design or channel focus to gain footholds. Noteworthy strategic themes emerging from company actions and filings include:
- Product differentiation via formulation and pigment technology. Established players continue to invest in daily‑disposable platforms with embedded moisture systems and layered pigment gradations to mimic natural irises—an important defensive and offensive lever in a crowded cosmetic space.
- Expansion into toric and prescription variants. Recent product launches and regulatory clearances reflect a clear trend: color lenses are moving beyond purely plano cosmetic positioning toward functional prescription solutions. This changes addressable market economics and raises entry barriers through enhanced clinical development needs.
- Regulatory clearances as market gatekeepers. New 510(k) approvals for silicone hydrogel toric designs and novel lens materials increase the intensity of competition for the prescription‑capable segment. Strategic actors that secure robust regulatory cover earlier can convert cosmetic interest into physician‑prescribed volumes.
- Channel diversification. A two‑track approach—protecting optical channel relationships while scaling direct‑to‑consumer channels—has become a best practice. Balancing margin capture with clinician endorsement is particularly important where clinical safety messaging is a differentiator.
Representative company positioning (high level): leading multinational device manufacturers maintain broad disposable portfolios and heavy regulatory & distribution capability, while regional specialists emphasize niche aesthetics, certifications for multiple markets (FDA, CE), and price/novelty plays—each requiring a distinct competitive response.
Regulatory and reimbursement environment — what changes in 2026?
Regulatory realities are pivotal to strategy. Authorities classify colored and decorative contact lenses as medical devices; that means even “cosmetic” variants require premarket pathways and biocompatibility evidence per ISO 10993. Recent filings and clearances highlight two tactical implications:
- Time to market is strongly driven by regulatory lead time and the robustness of biocompatibility & sterility dossiers; companies should budget regulatory resources and clinical capacity accordingly in 2026 planning cycles.
- Reimbursement remains limited for elective cosmetic use; however, the availability of prescription color or specialty lenses can unlock coverage pathways for clinically indicated products—making clinical differentiation a revenue multiplier in certain segments.
2026 action plan — prioritized strategic recommendations
We recommend a three‑horizon plan for executive teams who want to convert market growth into sustainable advantage in 2026:
- Near term (0–12 months): Harden regulatory pipelines (510(k) and ISO compliance), shore up supply chain redundancies for daily disposable production, and pilot DTC campaigns alongside clinician co‑marketing in selected markets. Validate toric/prescription engineering early to avoid later rework.
- Medium term (12–24 months): Execute channel segmentation playbooks—optimize pricing and bundling for optical partners while capturing higher margins online with subscription models. Deploy targeted product versions (material, pigment, and packaging) for prioritized customer cohorts and lock distribution partnerships in high‑growth territories.
- Longer term (24+ months): Pursue capability‑driven M&A—target players with regulatory clearances, unique pigment IP, or manufacturing scale for daily disposables. Build evidence generation programs to support clinical claims and potential reimbursement where medically indicated.
Risks and mitigants
Key risks for 2026 execution include regulatory delays, pigment stability or biocompatibility failures, channel price erosion, and supply chain constraints for specialized materials. Recommended mitigants:
- Parallelize regulatory and product validation workstreams to reduce schedule risk.
- Lock multiple qualified manufacturers for critical raw materials and consider near‑shoring options if logistics volatility threatens lead times.
- Design flexible commercial models that enable price differentiation by channel and value proposition without undermining optical partnerships.
What PW Consulting will not show here — and why
This article intentionally omits detailed segment and regional breakdowns, fine‑grained channel share tables and proprietary pricing datapoints. The full report contains those detailed matrices, interactive models and state‑by‑state dashboards that senior teams use for investment memos, diligence, and board presentations. This preview is designed to surface the strategic directions and decision levers while encouraging clients to access the complete dataset to execute with precision.
Next steps for executives
If your 2026 plan involves portfolio expansion, regulatory submissions, channel reinvention, or M&A in disposable color lenses, PW Consulting can support three immediate engagements:
- Rapid regulatory readiness audit (6–8 weeks) to map current dossiers to 510(k) and ISO 10993 expectations.
- Commercial channel optimization sprint (8–12 weeks) to define pricing, subscription, and optical partner models with ROI forecasts.
- Target screening and valuation for tuck‑in or platform M&A (12–16 weeks) using our scenario‑based valuation model calibrated to market growth and concentration metrics.
To access the full report, interactive market model and company profiles that contain the granular segment and country data required for transaction diligence or commercial planning, please visit the PW Consulting report page. Our extended dataset includes the detailed market segmentation, country dashboards, and the Excel model referenced in this preview—essential tools for converting the 8.7% CAGR opportunity into measurable enterprise value in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Disposable Color Contact Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Chip Probing Market to Expand at a 9.21% CAGR Through 2032
By pmarketresearch, 2026-08-18
Worldwide Chip Probing Market: Strategic Imperatives for 2026 Decision‑Makers
Executive Preview — Why this moment demands a focused probing strategy
As global semiconductor value chains accelerate toward AI, HPC, advanced packaging, and silicon photonics, wafer probe technologies have moved from a niche capital good to a strategic choke point. Our latest PW Consulting report, "Worldwide Chip Probing Market (Base Year 2025) — Forecast 2026–2032," quantifies that transformation. The market expanded from approximately USD 2,840.5 Million in 2020 to USD 4,650 Million in 2025, and is projected to continue an upward trajectory—reaching roughly USD 8,614.09 Million by 2032 with a compound annual growth rate of 9.21% over the forecast window. For senior leaders planning capex, sourcing, qualification roadmaps, or M&A in 2026, these macro dynamics are a wake‑up call: probe cards and wafer probing systems now materially influence time‑to‑revenue for next‑generation devices.
Ball Tow Hook System Market
What’s changing: demand drivers and structural shifts
-
Technology mix and complexity: The convergence of multi‑die packages, HBM stacks, high‑parallelism SoC testing, and on‑wafer RF/mmWave characterization is forcing probe designs to become both more sophisticated and more application‑specific. This is echoing through procurement cycles: long lead times for specialized probe cards and higher per‑unit engineering intensity are becoming the norm.
Wireless HART Communicators Market -
Supply chain tightness and capacity signaling: Probe card lead times have stretched — with market participants reporting windows as long as six months amid elevated AI chip demand — prompting OEMs and foundries to rework qualification schedules and adopt buffer inventory policies across 2026.
Worldwide Distributed Sensing Cables Market -
Regulatory overlay and policy incentives: Recent export control refinements (notably controls tied to wafer‑probing equipment capable of sub‑3.5 μm positioning accuracy for advanced computing) have added a compliance dimension to sourcing decisions. Conversely, targeted grants under instruments such as the CHIPS Act are shortening qualification cycles for new fab lines, especially where domestic testing capabilities can be co‑located with production.
-
Cost and materials realities: The unit economics of fine‑pitch, high‑density probe cards now reflect material and precision assembly costs that can be substantial; this is driving increased interest in total cost of ownership (TCO) approaches that integrate durability, rework rates, and lifetime qualification effort rather than headline unit price alone.
Competitive landscape: concentrated, innovative—and increasingly transactional
The chip probing market shows clear signs of concentration. The top three suppliers hold a dominant share, and the top five approach an even higher combined threshold, defining an oligopolistic supplier structure that amplifies the strategic importance of supplier selection, alliance building, and contingency planning. Against this backdrop, incumbent technology leaders are deploying a mix of organic product development, capacity investments, partnerships, and selective acquisitions to secure positions in adjacent, higher‑value test domains.
-
FormFactor, Inc. (Livermore, CA) has been particularly active: a recent facility expansion to increase capacity for advanced packaging and high‑bandwidth memory testing complemented a strategic acquisition to deepen silicon photonics and co‑packaged optics capabilities. Its partnership ecosystem—exemplified by program expansions with RF measurement vendors—underscores an integrated systems approach that blends probe cards with characterization services.
-
Technoprobe S.p.A. (Italy) continues to iterate on proprietary MEMS and vertical probe technologies, while locking in long‑term supply agreements to secure MEMS supply and scale. These arrangements illustrate how technology licensing and supply contracts have become defensive tools for both suppliers and large buyer groups.
-
MPI Corporation (Hsinchu, Taiwan) has signaled the market’s cyclicality and demand surges—reporting stretched lead times and capacity expansion plans following record revenues. This dynamic is emblematic of how demand swings tied to AI/HPC cycles translate quickly to probe card lead times and capacity tightness across the ecosystem.
Beyond these headline players, a broad ecosystem of specialized vendors — from precision contact‑spring suppliers to regional probe‑card manufacturers — contributes to the system-level value chain. The market’s structure rewards firms that combine deep IP (MEMS, vertical probing, RF/mmWave designs), robust manufacturing scale, and a services capability for qualification and cross‑site standardization.
Strategic implications for 2026 planning cycles
-
Reframe probe procurement as strategic sourcing: Treat probe cards as multi‑year, mission‑critical assets. Procurement strategies should move from transactional purchasing to long‑term supplier partnerships with dual sources for key technologies (e.g., MEMS-based probe cards, RF/mmWave probe assemblies).
-
Accelerate concurrent qualification workflows: With policy incentives shortening fab qualification timelines in some jurisdictions, device makers and foundries must invest in parallelized probe qualification templates, cross‑site validation plans, and shared test‑vector libraries to avoid becoming gate‑kept by probe delivery schedules.
-
Integrate regulatory risk into sourcing and M&A models: Export control refinements affecting ultra‑precise positioning in probing equipment introduce both compliance costs and potential supply‑side segmentation. Companies should model sanctions scenarios and localize critical capacities where policy risk is material to product roadmaps.
-
Move beyond unit price—optimize for lifecycle economics: Given high materials and assembly intensity for fine‑pitch cards, TCO frameworks that capture durability, rework frequency, and effective test throughput deliver better procurement outcomes than lowest‑price awards.
-
Build strategic optionality through partnerships and minority investments: Recent industry activities highlight that strategic alliances, minority stakes, and tech partnerships remain efficient ways to secure preferential access to road‑mapped probe technologies and to accelerate co‑development with test‑equipment platforms.
Key risk vectors and mitigation playbook
-
Capacity squeezes and lead‑time volatility — Mitigation: maintain multi‑tier supplier lists, pre‑book capacity via long‑term supply agreements, and invest in in‑house rework/repair capability.
-
Regulatory fragmentation — Mitigation: implement a regulatory risk dashboard tied to procurement triggers and develop localized qualification plans where policy restricts cross‑border equipment flows.
-
Technology obsolescence and design complexity (sub‑5 nm and beyond) — Mitigation: adopt modular probe architectures and co‑develop probe designs with strategic suppliers; fund targeted investments in MEMS/RF probe competency.
-
Material and labor cost inflation for high‑precision assemblies — Mitigation: incorporate material hedging strategies and supplier productivity KPIs into contracts; explore design for manufacturability (DFM) for probe durability.
What PW Consulting’s report delivers — practical tools for 2026 execution
This study was written with busy executives and program managers in mind. Beyond narrative and trend analysis, the report provides a suite of actionable deliverables designed to be operational in 90–180 day planning cycles:
-
A dynamic market model (2020–2032) with configurable levers for demand scenarios, technology adoption curves, and policy shock modeling—enabling rapid "what‑if" analysis for capex and procurement decisions.
-
Supplier scorecards and a CR‑based competitive map that translate capability, capacity, and compliance posture into procurement risk grades—designed to support dual‑sourcing and strategic supplier selection.
-
Qualification playbooks and timeline templates for wafer probe integration into new fab ramps, including sample test vectors, acceptance criteria, and failure‑mode checklists that materially shorten time‑to‑qualification.
-
TCO and unit‑economics frameworks that decompose capital and service costs across life cycles—allowing procurement and engineering teams to move from unit price to lifetime throughput optimization.
-
A regulatory and policy impact matrix that maps export controls, domestic incentives, and standards activity into sourcing pathways and localization triggers.
-
Strategic M&A and partnership playbooks that identify where bolt‑on acquisitions and minority investments are most likely to accelerate access to high‑value probing segments.
Next steps for executives
For 2026, the most successful semiconductor programs will be those that treat wafer probing as an integral part of their product and operational strategy rather than as an outsourced commodity. Whether you are sizing fab ramp resources, negotiating long‑term probe card supply agreements, or evaluating acquisition targets, PW Consulting’s report equips teams with the empirical market trajectory (2020–2032), concentration analysis, supplier behavior signals, and operational playbooks needed to act quickly and confidently.
To review the full set of models, supplier scorecards, scenario tools, and prescriptive qualification templates, access the complete report and supplementary datasets on our website. The executive briefing edition summarizes implications for 2026 decisions; the complete data pack enables direct input into your procurement and capex planning systems.
About PW Consulting
PW Consulting advises semiconductor leaders, system OEMs, and investment firms on strategic sourcing, technology roadmaps, and market entry. Our Worldwide Chip Probing Market study synthesizes primary supplier interviews, transaction tracking, and proprietary demand modeling to convert market signals into executable plans.
For detailed analysis of this topic, please visit the official page: Worldwide Chip Probing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Vise Grips Market to Rise from USD 1,050.0 Million in 2025 to USD 1,405.14 Million by 2032 at a 4.25% CAGR
By pmarketresearch, 2026-08-18
Worldwide Vise Grips Market: Strategic Outlook to 2032 — PW Consulting Report Preview
PW Consulting today releases a strategic preview of our upcoming Worldwide Vise Grips Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032). Drawing on proprietary modeling and primary interviews across manufacturing, distribution, and end-use sectors, the study quantifies the market’s recovery and expansion trajectory and converts those insights into a practical playbook for executive teams planning resource allocation, pricing, and M&A through 2026 and beyond.
Worldwide Factoring Service Market
Executive snapshot: a steady recovery into a structurally supportive market
After a period of short-term volatility in the early 2020s, the global vise grips and locking pliers market reached approximately USD 1.05 billion (revenue unit: Million) in 2025. Our forecast model projects continued expansion throughout the 2026–2032 horizon, delivering a compound annual growth rate (CAGR) of 4.25% and market scale approaching USD 1.4 billion by 2032. This baseline reflects a confluence of steady end‑market demand, incremental product innovation, and modest premiumization driven by professional segments.
Arbitrary Wave Function Generator Market
For leadership teams, those headline numbers matter because they convert previously tactical categories into strategic adjacencies: predictable growth and scale create a favorable backdrop for investments in automation, coatings and materials innovation, and selective consolidation.
Worldwide Time and Expense Software Market
Why 2026 is a consequential decision point
- Margin pressure and input-cost volatility: Hot Rolled Coil (HRC) steel — the primary raw material — has shown material price movement into 2026. Our latest market intelligence recorded HRC price bands in early 2026 consistent with elevated benchmarks versus the pandemic trough, with North American pricing dynamics particularly relevant to regional cost structures. This changes the calculus for sourcing, hedging and pass-through pricing strategies.
- Regulatory and safety baseline: Locking pliers used in industrial and welding contexts must satisfy ISO/ANSI hand-tool standards covering material strength and ergonomics. Compliance impacts allowable materials, testing requirements, and go-to-market timing for new designs.
- End-market stability with pockets of growth: Demand drivers remain anchored in automotive repair, construction, and metal fabrication. Within these sectors, replacement cycles and professional-grade upgrades create persistent addressable demand even when capex cycles are muted.
- Competitive structure enabling active portfolio plays: Market concentration is moderate; the top three players do not dominate the space completely, and the top five account for less than half of global revenues. This fragmentation creates opportunities for focused scale plays and bolt-on acquisitions that can deliver step-change returns.
What the PW Consulting report delivers (practical, operator-oriented)
Our full report is designed for decision-makers who require both rigor and actionable recommendations. Highlights include:
- Proprietary market-sizing and forward-looking scenario models (2026–2032) with sensitivity to steel price shocks, exchange-rate movements and channel shifts.
- Segment dynamics by product family and application class, including adoption curves for premium features (e.g., fast‑release mechanisms, specialty jaws, corrosion-resistant coatings) and effective GTM approaches by channel.
- Cost-to-serve and margin decomposition at the product-line level, enabling SKU rationalization and prioritization of high-return SKUs without disclosing granular commercial tables in this preview.
- Supply-chain mapping, including critical tier‑1 and regional sourcing options, freight exposure analysis, and recommendations for inventory localization versus centralization.
- Competitive benchmarking across product, price, distribution and aftermarket support metrics — accompanied by an M&A target scoring matrix and valuation range methodology.
- Tactical playbooks for OEMs, distributors and private-equity owners: three 12–18 month roadmaps for cost recovery, premiumization, and roll-up strategies.
Competitive landscape: players, strategies and recent moves
The competitive map blends global household names with specialized regional manufacturers. PW Consulting’s competitive synthesis emphasizes how incumbents are leveraging brand, product development and channel control to protect margins and open adjacent opportunities.
- IRWIN Tools (Stanley Black & Decker) — Originator and continued market reference for VISE‑GRIP branded locking pliers. Their breadth across curved, straight and long‑nose formats, plus variants with integrated wire cutters, keeps them central to professional channel conversations. Expect continued emphasis on brand licensing, packaging, and channel economics.
- Snap‑on Incorporated — A classic premium strategy: high‑end tool construction, aggressive tooth geometries and extended‑reach noses targeted at professional automotive and industrial customers. Snap‑on’s product introductions in recent years illustrate the premiumization vector and the value of tool ergonomics and accessibility in tight workspaces.
- Grip‑on Tools — A specialist innovator focused on corrosion resistance and application‑specific clamps. Their recent catalog release and introduction of new welding table clamps signals a product expansion strategy built on material and finish differentiation.
- Knipex — German engineering and precise sizing bring a reputation advantage in trades and industrial segments. Recent product updates increasing size breadth underscore a platform approach to capturing incremental share within professional toolkits.
- Klein Tools, Bahco, Toptul — These players execute regional and channel‑specific plays: Klein targets electrical and maintenance professionals with tailored sets; Bahco focuses on straight‑jaw and maintenance segments; Toptul leverages manufacturing and industrial channels from its regional base.
Recent product activity and catalog refreshes across suppliers demonstrates a common strategic theme: product refinement and surface/material upgrades, rather than radical reinvention. For market entrants and incumbents alike, the strategic question is whether to compete on price, product differentiation, or an integrated channel-plus‑service model.
Segment and pricing dynamics (what matters without giving away the splits)
The market is organized by product architecture (curved jaw, straight jaw, long nose and specialty welding clamps) and by application (professional repair, construction/renovation, industrial manufacturing, and DIY). While our full report contains the granular demand tables by product and application, the headline strategic implications are:
- Curved‑jaw and general‑purpose locking pliers remain foundational SKUs; differentiation comes from material treatment, finish and ergonomics rather than core geometry alone.
- Specialty welding clamps and coated variants are higher-margin, lower-volume niches that can be leveraged for selective premiuming and channel differentiation.
- Short-term steel-price volatility directly pressures gross margins; the industry is increasingly using a mix of contract hedges, premiuming on innovation (coatings, finish), and localized sourcing to preserve margins.
- Regulatory compliance (ISO/ANSI) raises the bar for new entrants and lengthens time‑to‑market for performance‑critical variants; incumbents can use certification as a moat in institutional channels.
Strategic playbook for 2026: three high‑impact moves
- Price & procurement discipline: Implement dynamic cost models tied to HRC benchmarks and regional freight indices. Negotiate multi-year contracts with tier‑1 steel suppliers and consider extended payment terms to smooth P&L timing.
- Product laddering and channel segmentation: Rationalize low-margin SKUs; invest in two vectors — a premium professional line (durable finishes, ergonomic features) and a value stream optimized for distribution efficiency and lower cost‑to‑serve.
- Accelerate aftermarket and service differentiation: Introduce repair parts, warranty packages and educational content for trade professionals to build recurring revenue and reduce price elasticity in B2B channels.
For PE sponsors and corporate development leaders, the moderate market concentration presents a realistic consolidation runway — tuck‑ins that can yield procurement synergies and broaden regional distribution without game‑changing capex.
How to use PW Consulting’s full report
This preview is intentionally high‑level. The full PW Consulting Worldwide Vise Grips Market report contains the granular regional, product and application splits, downloadable forecast tables, supplier scorecards, and financial models that enable implementation: Excel‑based demand models, SKU profit waterfalls, scenario simulators for steel-price stress tests, and a prioritized M&A target list with transaction rationales.
Executives seeking to convert forecast clarity into action in 2026 will find three immediate deliverables inside the report useful: (1) a near‑term cost‑pass‑through and pricing trigger framework for commercial teams; (2) an SKU prioritization matrix that balances margin, channel fit and manufacturing complexity; and (3) an M&A playbook with quantified synergy estimates and integration checkpoints tailored to the tools sector.
Next steps and contact
For sourcing the full report, licensing the forecast model, or commissioning a tailored workshop that maps these findings into your operational plan for 2026, please visit PW Consulting’s Worldwide Vise Grips Market page or contact our strategic advisory desk. Our analysts can deliver a condensed executive workshop that translates market scenarios into a prioritized implementation plan within 30 days.
PW Consulting’s analysis is built from primary interviews, trade-channel sampling and modeled cost inputs — including live HRC pricing and compliance requirements — to ensure recommendations are both defensible and implementable. This preview is designed to inform initial strategy while motivating a deeper review of the full analytical work product for tactical decisions in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Vise Grips Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 6.12% CAGR for Global Aluminum Dimethyl Isopropoxide Market Through 2032
By pmarketresearch, 2026-08-18
Worldwide Aluminum Dimethyl Isopropoxide Market: Strategic Imperatives for 2026 — PW Consulting Insight
As semiconductor device architectures march toward ever-thinner films and more complex stacks, the precursors that enable atomic-layer and metal-organic chemical vapor deposition (ALD / MOCVD) are becoming strategic procurement and R&D levers. PW Consulting’s new market study on Aluminum Dimethyl Isopropoxide (ADMI) — anchored on 2025 as the base year and projecting through 2032 — quantifies a disciplined recovery and acceleration in global demand and frames a decision toolkit for companies that must act in 2026. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 6.12% over the forecast horizon, with total market value rising from USD 92.45 Million in 2025 to an estimated USD 140.11 Million by 2032. These headline dynamics set the stage for a pragmatic, risk-aware playbook for suppliers, semiconductor OEMs, materials intermediaries and strategic investors.
Worldwide Building Design and Building Information Modeling (BIM) Software Market
Why 2026 is a Pivotal Year
-
Process inflection in thin-film deposition: Continued adoption of advanced ALD and MOCVD chemistries, combined with new application designs in logic, memory and power electronics, increases the technical premium placed on precursor purity, consistency and handling characteristics. Peer-reviewed process studies in 2025 also highlight the rising use of ADMI as a non-pyrophoric alternative to trimethylaluminum (TMA) in plasma-enhanced ALD routes for Al2O3 films, a structural shift with procurement and safety implications.
12V LiFePO4 Battery Market -
Supply-chain and regulatory tightening: ADMI’s hazard profile — including classification as highly flammable and water-reactive (per supplier safety data) — means transport and warehousing must comply with ADR/RID and equivalent national regimes. These constraints materially affect landed cost, qualification lead times and contingency planning for companies that have historically relied on single-source relationships.
Worldwide Automotive Elastomer Bumper Market -
Market consolidation and bargaining dynamics: Our concentration metrics indicate that the top three suppliers account for a meaningful share of global supply, with the top five suppliers controlling roughly three-quarters of the market. That structure creates both opportunity and vulnerability: buyers face concentration risk, while suppliers can extract premium pricing for high-reliability, high-purity streams.
What PW Consulting’s Report Delivers (Practical, Actionable)
-
Integrated demand-supply model — granular, supplier-level demand forecasts and a probabilistic capacity build-out model calibrated to 2020–2025 history and 2026–2032 scenarios. (Note: detailed regional and application splits are reserved for the full report.)
-
Purity and qualification playbook — operational checklists for procurement, analytical acceptance criteria, qualification timelines and on-site audit templates tailored to high-purity (electronic-grade) and industrial-grade use cases.
-
Cost-to-serve and landed-cost deskbook — modular cost models that let procurement teams evaluate offer-to-offer tradeoffs (price vs. logistics complexity, inventory buffers, regulatory compliance expenses).
-
Regulatory and logistics heatmaps — mapping of transport corridors, ADR-class handling bottlenecks and country-level regulatory triggers that influence lead time volatility.
-
Supplier scorecards and M&A target shortlists — independent benchmarking across technical capability, capacity flexibility, quality systems and commercial terms, coupled with strategic acquisition and JV templates.
-
Scenario-driven investment cases — build vs. buy analyses for captive production, contract-manufacturing arrangements and scale-up sequencing for new manufacturing lanes.
Competitive Landscape: Key Players and Strategic Implications
-
Ereztech LLC (US) — A specialty manufacturer that focuses on high-purity ADMI for ALD and MOCVD. Ereztech’s emphasis on research and commercial quantity supply positions it as a rapid-response technical partner for device developers. Strategic implication: qualification of a specialist like Ereztech should be a near-term priority for OEMs needing small-batch, high-purity consistency during materials ramp phases.
-
Strem Chemicals, Inc. (US) — Markets PURATREM-grade dimethylaluminum isopropoxide variants at elevated purity. Their product framing and certifications make them a natural choice for companies with stringent analytical specifications. Strategic implication: Strem can be a preferred co-supplier for dual-sourcing strategies that require tightly specified product monographs.
-
American Elements (US) — A global manufacturer and distributor of aluminum precursors in both research and production quantities. Their broader global footprint benefits buyers with multi-site manufacturing footprints. Strategic implication: use American Elements when scale and geographic redundancy are priority procurement criteria.
-
Dock Chemicals (South Korea) — A regional producer focused on ADMI for MOCVD and ALD applications; proximity to East Asian IDM and foundry ecosystems is a competitive advantage. Strategic implication: Asian fabs and OSATs should prioritize engagement with Dock for localized supply agreements and shorter qualification cycles.
-
Wonik Materials North America (US) — Supplies dimer forms for semiconductor deposition processes and is oriented toward thin-film and process integration customers. Strategic implication: technical compatibility (monomer vs. dimer handling, delivery systems) must be validated early if choosing such suppliers.
-
Parchem Fine & Specialty Chemicals (US) — A global distributor that provides access to multiple manufacturer brands, useful for buyers that need flexibility without investment in long-term contracts. Strategic implication: distributors can be a tactical bridge during qualification or when volume commitments are uncertain, but typically at the expense of longer-term price optimization.
Across the supplier set, our assessment points to mid-to-high market concentration — the top three and top five suppliers collectively control a sizable portion of available capacity. For buyers, that translates into meaningful negotiation dynamics: suppliers with credible high-purity capacity can command longer lead times and premium pricing, but they are also prime candidates for strategic partnerships, co-development and capacity reservation agreements.
Raw Material and Regulatory Dynamics that Matter
-
Upstream feedstock linkages: Trimethylaluminum (TMA) remains an important upstream organoaluminum feedstock in many synthetic routes used to make ADMI. Fluctuations in TMA availability or pricing propagate through to precursor economics and can change the relative attractiveness of in-house synthesis vs. contract manufacture.
-
Hazard, handling and transport: ADMI’s classification as a highly flammable, water-reactive compound imposes specific ADR/RID and equivalent transport requirements. Companies must budget for specialized packaging, certified carriers and emergency-response training — cost items that are frequently underestimated in early supplier negotiations.
-
Process substitution opportunities: Recent ALD research highlights ADMI as a non-pyrophoric alternative to TMA for certain plasma-enhanced processes. This opens pathways to lower fire-risk operations but can require reformulation work and fresh qualification cycles — a tradeoff that process owners must evaluate with their quality and EHS teams.
A 2026 Decision Playbook — Prioritized Actions
-
Immediate (0–6 months) : Conduct dual-path qualification—identify a primary high-purity supplier and a secondary regional supplier or distributor to mitigate single-source disruption. Initiate audit or desk-based technical due diligence focused on purity analytics and handling procedures.
-
Near-term (6–12 months) : Negotiate supply agreements with explicit performance SLAs (purity, water content, delivery windows) and contingency clauses for force majeure tied to transport restrictions. Establish inventory buffers and evaluate dedicated storage investments at critical fabs.
-
Medium-term (12–24 months) : Invest in co-development partnerships to tailor precursor formulations for specific ALD chemistries; consider off-take or capacity reservation agreements with tier-1 suppliers to lock in supply as demand ramps.
-
Strategic (24+ months) : Evaluate vertical integration or joint-venture production if scale economics and long-term demand justify capital exposure; maintain a rolling scenario plan tied to device-node roadmaps and alternative precursor technologies.
How to Use This Report in Your 2026 Planning Cycle
-
Procurement teams: Use our cost-to-serve and supplier scorecards to reprice contracts and rework IPN/part-number strategies before Q3 renegotiation windows.
-
R&D and process engineering: Leverage the qualification checklists and purity acceptance criteria to shorten time-to-qualify for new precursor streams.
-
Corporate development: Apply the M&A shortlist and scenario models to identify bolt-on targets or JV partners that fill geographic or technical gaps.
-
Risk managers and EHS: Operationalize the regulatory heatmaps and logistics recommendations into playbooks that reduce exposure to transport and storage incidents.
PW Consulting’s study is intentionally tactical in orientation: it combines a probabilistic market model (2026–2032), supplier-level intelligence, and operational guidance required to convert market insight into executable plans. To preserve the strategic value of our proprietary segmentation and supplier benchmarks — the very inputs that enable negotiation leverage and investment discipline — this executive summary omits the detailed regional and application splits. If your 2026 plan depends on knowing demand by region, purity-grade trajectories, or supplier share at the country level, the full report provides the granular datasets, downloadable model, and supplier scorecards necessary to implement the playbook described here.
For a guided walkthrough of the report’s models, or to commission a custom annex (e.g., captive production feasibility, logistics-costing for specific corridors, or bespoke supplier due diligence), PW Consulting’s industry team is available to support tailored engagements that convert insight into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Aluminum Dimethyl Isopropoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HNB Heater Market Poised for Robust Growth — 8% CAGR Forecast Through 2032
By pmarketresearch, 2026-08-18
HNB Heater Market 2026 Strategic Brief: Navigating Growth, Supply-Chain Friction, and Competitive Consolidation
As PW Consulting’s lead industry analyst, I present a concise yet strategically rich preview of our HNB (heat-not-burn) heater market study — produced with the intent to inform C-suite decisions for 2026. The global HNB heater market has moved from an early-stage innovation curve into a scale-up phase: total market value rose meaningfully between 2020 and 2025 and, under our core forecast, is projected to continue expanding at roughly an 8.0% compound annual growth rate through the 2026–2032 horizon. This trajectory positions the sector as a high-priority growth vector for tobacco manufacturers, EMS suppliers, and precision-component vendors that can execute rapid industrialization while managing regulatory and supply-chain complexity.
Shoe Wrap Machine Market
Why this matters for 2026 strategic planning
-
Macro momentum provides optionality: With multi-year expansion built into the market base case, executives can justify near-term investments in product refinement, scale manufacturing, and commercialization pilots — but only if those investments are aligned to resilient supply-chain strategies and regulatory scenarios.
Nuclear Decommissioning Services Market -
Consolidation and concentration are shaping power dynamics: The sector exhibits a materially concentrated competitive structure at the top, with the leading groups controlling a clear majority of market activity. For incumbents and challengers alike, this consolidation creates both barriers and partnership opportunities that should inform M&A, JV, and contract-manufacturing choices in 2026.
Drum Turner Market -
Operational resilience is now a competitive differentiator: Elevated component and material pressure, trade-policy friction, and evolving compliance regimes mean that the winners will be those with diversified sourcing, localized manufacturing flex, and proactive regulatory engagement.
What PW Consulting’s HNB Heater report delivers (practical contents)
Our full study is engineered to be operationally actionable for management teams. It combines quantitative modeling, primary vendor benchmarking, and scenario-based playbooks so that clients can move from insight to execution within quarters rather than years. Key deliverables include:
-
Market sizing and demand model — base year anchored to 2025 with historical trend analysis (2020–2025) and scenario-driven forecasts (2026–2032) that reconcile top-down market drivers with bottom-up unit economics.
-
Competitive landscape heatmap — an evidence-based assessment of product portfolios, technology roadmaps, go-to-market strategies, and manufacturing footprints for leading tobacco groups and EMS suppliers.
-
Supplier and component scorecards — qualitative and quantitative ratings for heating element producers, precision component manufacturers, and contract assemblers, including risk indices for tariffs, single-source exposures, and inventory velocity.
-
Commercial playbooks — tested approaches for field trials, retail conversion (including demo and trial mechanics), pricing strategies under different regulatory tax regimes, and aftermarket/replacement channel optimization.
-
Regulatory tracker and scenario suite — line-by-line interpretive guidance on how major jurisdictions’ tobacco product frameworks could influence product configuration, labeling, and permissible marketing tactics through 2026 and beyond.
-
Transaction advisory annex — valuation sensitives and negotiation levers for M&A or strategic supply agreements, informed by our market-concentration analysis and forecasted margin trajectories.
Competitive dynamics: who matters and why
Assessing competitive intent requires reading beyond devices to the capabilities behind them. The market’s top commercial players — leading multinational tobacco groups and specialized EMS partners — pursue complementary but distinct strategies.
-
Global tobacco leaders are focusing on ecosystem control. Major groups have moved from single-device concepts to platform plays that combine proprietary heating technologies, tailored consumables, and branded retail experiences. Recent product rollouts and targeted market expansions demonstrate an emphasis on rapid consumer adoption through trial mechanics and hybrid channel strategies.
-
Electronics manufacturers and contract assemblers are the structural enablers. Tier-1 EMS firms and regional precision manufacturers provide the scale, quality control, and cost engineering necessary to move from boutique production to mass supply. Their willingness to co-invest in tooling, IP-protected subsystems, and localized assembly is a primary determinant of who can price, iterate, and deliver at scale.
-
Specialized component suppliers and niche entrants remain critical for differentiation. Firms that control advanced heating element materials, induction modules, or high-reliability connectors can create effective switching costs — which is why manufacturing partnerships and long-term purchase agreements are now central bargaining chips.
Recent market moves and strategic implications
Notable 2024–2025 developments — including flagship product launches and geographic rollouts — confirm the top players’ intent to treat HNB as a core business line. These tactical initiatives have three strategic consequences for 2026 planning:
-
Speed-to-market is a competitive lever. Publicized product launches and trial campaigns show that consumer adoption can be accelerated through concentrated local activations; consequently, companies that can align channel readiness with localized manufacturing will convert trials into sustainable share faster.
-
Market entry is costly but defensible. Launches in developed markets signal both opportunity and constraint: the latter driven by regulatory scrutiny and tariff exposure. Cost-plus models without supply-chain hedging will compress margins where import duties apply.
-
Brand and device ecosystems are becoming the battleground. Device hardware alone is not the moat — integrated consumable availability, retail experience, and post-sale service are the elements that determine retention and lifetime value.
Regulation, tariffs, and materials: operational risks to prioritize
Three cross-cutting pressures will materially influence decisions in 2026:
-
Regulatory frameworks: Jurisdictions that have codified pathways for HNB products create commercialization opportunity, but compliance obligations (product disclosures, testing regimes, and marketing limits) materially affect time-to-revenue and go-to-market design. Companies should plan regulatory submission timelines as critical path milestones.
-
Trade and tariff exposure: Import levies on electronic components can materially shift landed costs. Our clients should evaluate manufacturing localization or near-shore assembly to mitigate tariff impact and shorten replenishment cycles.
-
Raw material availability: Although general stabilization has occurred versus the acute shortages of prior years, procurement complexity remains elevated. Component lead times and material premiums should be stress-tested in any supply agreement or capacity expansion plan.
Actionable recommendations for 2026
Based on our integrated modeling and vendor assessments, PW Consulting recommends a prioritized set of actions for executives formulating their 2026 agendas:
-
Adopt a dual-sourcing manufacturing posture. Maintain a fast-follow capacity capability in low-capex facilities while securing long-term partnerships with tiered EMS partners for volume scale and cost optimization.
-
Invest in modular device architectures. Designing platforms that decouple heating modules from control electronics reduces obsolescence risk and shortens new-format commercialization cycles.
-
Implement conditional go-to-market pilots. Run geographically bounded trials that mirror the regulatory complexity and supply constraints of target rollouts — and use those pilots to refine channel economics and post-sale service models.
-
Prioritize regulatory and trade scenario planning. Integrate legal and policy milestones into the commercial roadmap and model tariff-driven cost offsets so pricing and margin targets remain robust under adverse scenarios.
-
Explore strategic partnerships over outright vertical integration when speed-to-market and capital efficiency are paramount. Joint development agreements with specialty component suppliers and EMS firms can secure priority capacity without the full burden of asset ownership.
What we conceal here — and why you should read the full report
In keeping with our “trailer” approach, this briefing intentionally surfaces strategic conclusions and high-level data points to build confidence and stimulate action — but it does not disclose the granular subsegment splits, regional share tropes, or proprietary unit-cost tables that underlie our valuation. Those detailed breakouts — including detailed technology mixes, channel economics, supplier-level pricing, and scenario-sensitive financial models — are proprietary to the full PW Consulting HNB Heater Market report and are indispensable for transaction-level decisions, tender bids, and market-entry timing.
If your 2026 strategy requires precise inputs — whether for capital allocation, M&A diligence, or operational playbooks — the full dataset and model will materially reduce execution risk and improve deal outcomes.
Conclusion: positioning for the next wave
As the HNB heater market transitions from demonstration to durable commercialization, the strategic imperative for 2026 is clear: act where you can secure supply, design platforms for iteration, and engage regulators proactively. The sector’s growth profile, underpinned by a sustained mid-single-digit-plus CAGR through the 2026–2032 forecast window, rewards disciplined deployment of capital and a bias toward operational resilience. Companies that move first to lock priority supply, optimize manufacturing footprints, and orchestrate retail-to-aftermarket ecosystems will convert market growth into durable economic returns.
PW Consulting’s comprehensive report — anchoring its base year in 2025 and spanning historical trends (2020–2025) and forward-looking scenarios (2026–2032) — is built to be the playbook for executives who must translate market potential into realized advantage. For access to the full modeling, competitive scorecards, and executable annexes, please consult the official report page.
For detailed analysis of this topic, please visit the official page: HNB Heater Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com