

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide Reinforced Polypropylene Market to Expand at a 6.28% CAGR Through 2032

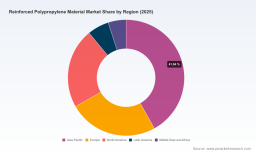
PW Consulting Releases Strategic Outlook: Worldwide Reinforced Polypropylene Material Market — A Decision-Maker’s Playbook for 2026
PW Consulting’s new market research brief on the Worldwide Reinforced Polypropylene (R-PP) material market combines forward-looking modeling with practical, executable guidance for senior executives preparing strategy, procurement, and investment plans for 2026. Built on a multi-year historical base and a 2026–2032 forecasting horizon, the study highlights a resilient market trajectory (a compound annual growth rate of 6.28% across the forecast window) and a continuing expansion in absolute market value. These headline metrics underscore the structural momentum behind reinforced polypropylene—but as this briefing explains, the 2026 planning cycle will be shaped by supply-side volatility, regulatory noise, and a competitive landscape that rewards both scale and specialty innovation.
Worldwide Account Takeover Protection Market
Market Trajectory and Competitive Density: What the Headlines Show
After steady recovery and expansion in the early 2020s, the reinforced polypropylene market reached a substantial size in the report’s base year, and our forecast points to meaningful incremental growth by the end of the forecast window. The industry sits in a middle-of-the-road concentration profile: the three largest firms hold a noticeable but not dominant share of global supply, and the five largest firms still leave ample room for regional leaders and specialized compounders to capture value. In short, the market rewards both scale-driven propositions and nimble, technology- or application-focused plays.
Telemedicine Integrated Consultation Vehicle Market
Why 2026 Is a Pivot Year for R-PP Strategy
-
Raw-material pressure is front-and-center. Resin and reinforcement inputs (notably polypropylene and glass fiber) represent the lion’s share of production cost for glass-fiber-reinforced PP systems. Recent cycles show that feedstock and fiber pricing moves transmit into compound economics quickly, compressing or expanding margins depending on pass-through dynamics and contractual structures.
Intra-Array Submarine Cable Market -
Regional supply imbalances and tariff dynamics are changing the calculus of sourcing. In several major producing markets, feedstock capacity growth has created price pressure at times, while trade measures implemented in 2025 introduced uneven tariff exposure across polymer supply chains. These factors combine to increase the value of diversified sourcing, nearshoring options, and strategic inventory policies.
-
Product innovation is bifurcating competition. Large integrated producers are leveraging compounding scale and sustainability messaging, while specialty compounders focus on long-fiber thermoplastics, modular formulations, and additive-enhanced grades tailored to demanding automotive and industrial applications. Recent product introductions across the industry indicate active R&D pipelines and faster time-to-market for differentiated reinforced grades.
Actionable Contents of the Report (Practical, Not Just Theoretical)
PW Consulting’s report is designed for executives who need actionable inputs, not just descriptive statistics. Key practical deliverables include:
-
A robust forecasting engine with scenario levers (price shocks, tariff cases, and demand adoption curves) that let teams stress-test procurement and pricing strategies under plausible 2026 conditions.
-
Raw-material cost mappings with sensitivity analysis: how variations in propylene and glass-fiber costs affect compound economics, and templates for contract clauses and hedging approaches that protect margins.
-
Supply-chain heatmaps and sourcing playbooks for footprint optimization—covering nearshoring, toll compounding partnerships, and contingency inventory models designed for manufacturers and OEMs.
-
Competitive scorecards and capability matrices evaluating compounding technologies (short glass vs. long glass, mineral and carbon reinforcements), sustainability credentials, and go-to-market strengths for leading producers and regional specialists.
-
M&A and partnership trackers identifying likely consolidation targets, capability-acquisition opportunities, and JV structures that accelerate access to application-specific reinforced PP grades.
-
Regulatory-impact dossiers that map tariff, recycling, and product-restriction risks to commercial outcomes—equipped with play-tested mitigation measures for procurement and commercial teams.
Competitive Landscape: Patterns to Watch
The supplier topology in reinforced polypropylene features several distinctive archetypes. Global integrated producers maintain advantages in scale, feedstock integration, and the ability to offer full-spectrum resin + compound solutions. Examples include multinational petrochemical majors who pair compounding capacity with global distribution. At the other end of the spectrum, regional and specialist compounders—those concentrating on engineered thermoplastic solutions, long-fiber thermoplastics (LFT), and custom formulations—compete on speed, customization, and close OEM relationships.
Key industry players profiled in the report include multinational producers with advanced compounding capabilities and sustainability programs; large regional chemical groups expanding LFT and reinforced portfolios; and nimble compounders focused on engineered grades and just-in-time supply. Notable recent product and collaboration moves—from long-fiber thermoplastic launches to additive-enhanced high-performance grades—illustrate an active innovation cycle and a marketplace receptive to differentiated performance offerings.
For decision-makers, the implication is clear: procurement and product-development strategies need to be multi-track. Leverage scale and integrated suppliers where total-cost economics favor volume and consistency; engage specialty compounders or co-development partners where technical performance or rapid customization is a priority.
Regulatory and Raw-Material Dynamics: Tactical Responses for 2026
-
Cost-pass-through and contract redesign: Given that resin and reinforcement costs drive the bulk of production expense, revise supply agreements to include clear indexation mechanics, trigger clauses, and shared-risk provisions for extreme price moves.
-
Tariff-aware sourcing: With recent trade measures selectively impacting polymer supply chains, evaluate sourcing alternatives and tariff-engineered routes. Small changes in routing or HS-code classification can materially affect landed costs.
-
Recycling and circularity as risk mitigators: Circular feedstocks and mechanically/chemically recycled resins are becoming both regulatory obligations and commercial differentiators. Investment in compatible compound formulations will increasingly protect revenue and margin in regulated markets.
Strategic Imperatives for 2026 Decision-Makers
-
Adopt scenario-based procurement: build at least three supply scenarios (base, upside on oversupply-driven price dips, and downside on feedstock tightening) and stress-test working capital and margin impacts.
-
Prioritize product partnerships: co-develop LFT and additive-enhanced R-PP grades with OEMs to capture higher-value system-level wins (lightweight structures, integrated assemblies, and electrification components).
-
Expand supplier diversification—not only geographically, but across the supply archetypes (integrators, regional compounders, specialist toll manufacturers).
-
Embed sustainability metrics into sourcing and product roadmaps to anticipate regulatory shifts and to access premium demand pockets seeking recycled or lower-carbon materials.
-
Use competitive intelligence to identify M&A or partnership targets—focus on specialty compounders with differentiated IP, or regional players that improve logistics and reduce tariff exposure.
-
Lock in flexible manufacturing and tolling arrangements to speed new-grade commercialization while limiting capital outlay in uncertain markets.
How PW Consulting Supports Implementation
PW Consulting extends the report with targeted advisory services and deliverables tailored to executive needs in 2026, including: bespoke procurement optimization workshops; supplier due-diligence playbooks and scorecards; transaction advisory for bolt-on acquisitions and joint ventures; and dynamic dashboards that convert the forecast engine into decision-ready visuals for procurement, commercial, and engineering teams. Our analysts also run war-gaming sessions to simulate tariff and supply shocks, enabling executive teams to refine escalation procedures and contingency playbooks.
Closing: Data Depth, Tactical Utility—Full Datasets Available
This briefing signals the breadth and depth of analysis included in the full Worldwide Reinforced Polypropylene Market report. The study provides detailed segmentation tables, supplier scorecards, granular application and regional demand modeling, and downloadable datasets that are intentionally retained behind the full report to preserve commercial value and analytical integrity. For procurement leaders, product strategists, M&A teams, and investors, the full report unlocks the segmented demand profiles, supplier economic models, and market-share matrices necessary to translate the strategic imperatives outlined here into operational plans for 2026.
To access the full dataset, scenario tools, and company-level intelligence, consult the official PW Consulting report page and arrange a briefing with our R-PP practice leads.
For detailed analysis of this topic, please visit the official page: Worldwide Reinforced Polypropylene Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com