

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 6.12% CAGR for Global Aluminum Dimethyl Isopropoxide Market Through 2032

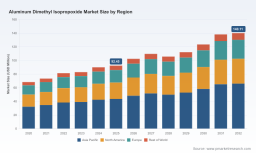
Worldwide Aluminum Dimethyl Isopropoxide Market: Strategic Imperatives for 2026 — PW Consulting Insight
As semiconductor device architectures march toward ever-thinner films and more complex stacks, the precursors that enable atomic-layer and metal-organic chemical vapor deposition (ALD / MOCVD) are becoming strategic procurement and R&D levers. PW Consulting’s new market study on Aluminum Dimethyl Isopropoxide (ADMI) — anchored on 2025 as the base year and projecting through 2032 — quantifies a disciplined recovery and acceleration in global demand and frames a decision toolkit for companies that must act in 2026. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 6.12% over the forecast horizon, with total market value rising from USD 92.45 Million in 2025 to an estimated USD 140.11 Million by 2032. These headline dynamics set the stage for a pragmatic, risk-aware playbook for suppliers, semiconductor OEMs, materials intermediaries and strategic investors.
Worldwide Building Design and Building Information Modeling (BIM) Software Market
Why 2026 is a Pivotal Year
-
Process inflection in thin-film deposition: Continued adoption of advanced ALD and MOCVD chemistries, combined with new application designs in logic, memory and power electronics, increases the technical premium placed on precursor purity, consistency and handling characteristics. Peer-reviewed process studies in 2025 also highlight the rising use of ADMI as a non-pyrophoric alternative to trimethylaluminum (TMA) in plasma-enhanced ALD routes for Al2O3 films, a structural shift with procurement and safety implications.
12V LiFePO4 Battery Market -
Supply-chain and regulatory tightening: ADMI’s hazard profile — including classification as highly flammable and water-reactive (per supplier safety data) — means transport and warehousing must comply with ADR/RID and equivalent national regimes. These constraints materially affect landed cost, qualification lead times and contingency planning for companies that have historically relied on single-source relationships.
Worldwide Automotive Elastomer Bumper Market -
Market consolidation and bargaining dynamics: Our concentration metrics indicate that the top three suppliers account for a meaningful share of global supply, with the top five suppliers controlling roughly three-quarters of the market. That structure creates both opportunity and vulnerability: buyers face concentration risk, while suppliers can extract premium pricing for high-reliability, high-purity streams.
What PW Consulting’s Report Delivers (Practical, Actionable)
-
Integrated demand-supply model — granular, supplier-level demand forecasts and a probabilistic capacity build-out model calibrated to 2020–2025 history and 2026–2032 scenarios. (Note: detailed regional and application splits are reserved for the full report.)
-
Purity and qualification playbook — operational checklists for procurement, analytical acceptance criteria, qualification timelines and on-site audit templates tailored to high-purity (electronic-grade) and industrial-grade use cases.
-
Cost-to-serve and landed-cost deskbook — modular cost models that let procurement teams evaluate offer-to-offer tradeoffs (price vs. logistics complexity, inventory buffers, regulatory compliance expenses).
-
Regulatory and logistics heatmaps — mapping of transport corridors, ADR-class handling bottlenecks and country-level regulatory triggers that influence lead time volatility.
-
Supplier scorecards and M&A target shortlists — independent benchmarking across technical capability, capacity flexibility, quality systems and commercial terms, coupled with strategic acquisition and JV templates.
-
Scenario-driven investment cases — build vs. buy analyses for captive production, contract-manufacturing arrangements and scale-up sequencing for new manufacturing lanes.
Competitive Landscape: Key Players and Strategic Implications
-
Ereztech LLC (US) — A specialty manufacturer that focuses on high-purity ADMI for ALD and MOCVD. Ereztech’s emphasis on research and commercial quantity supply positions it as a rapid-response technical partner for device developers. Strategic implication: qualification of a specialist like Ereztech should be a near-term priority for OEMs needing small-batch, high-purity consistency during materials ramp phases.
-
Strem Chemicals, Inc. (US) — Markets PURATREM-grade dimethylaluminum isopropoxide variants at elevated purity. Their product framing and certifications make them a natural choice for companies with stringent analytical specifications. Strategic implication: Strem can be a preferred co-supplier for dual-sourcing strategies that require tightly specified product monographs.
-
American Elements (US) — A global manufacturer and distributor of aluminum precursors in both research and production quantities. Their broader global footprint benefits buyers with multi-site manufacturing footprints. Strategic implication: use American Elements when scale and geographic redundancy are priority procurement criteria.
-
Dock Chemicals (South Korea) — A regional producer focused on ADMI for MOCVD and ALD applications; proximity to East Asian IDM and foundry ecosystems is a competitive advantage. Strategic implication: Asian fabs and OSATs should prioritize engagement with Dock for localized supply agreements and shorter qualification cycles.
-
Wonik Materials North America (US) — Supplies dimer forms for semiconductor deposition processes and is oriented toward thin-film and process integration customers. Strategic implication: technical compatibility (monomer vs. dimer handling, delivery systems) must be validated early if choosing such suppliers.
-
Parchem Fine & Specialty Chemicals (US) — A global distributor that provides access to multiple manufacturer brands, useful for buyers that need flexibility without investment in long-term contracts. Strategic implication: distributors can be a tactical bridge during qualification or when volume commitments are uncertain, but typically at the expense of longer-term price optimization.
Across the supplier set, our assessment points to mid-to-high market concentration — the top three and top five suppliers collectively control a sizable portion of available capacity. For buyers, that translates into meaningful negotiation dynamics: suppliers with credible high-purity capacity can command longer lead times and premium pricing, but they are also prime candidates for strategic partnerships, co-development and capacity reservation agreements.
Raw Material and Regulatory Dynamics that Matter
-
Upstream feedstock linkages: Trimethylaluminum (TMA) remains an important upstream organoaluminum feedstock in many synthetic routes used to make ADMI. Fluctuations in TMA availability or pricing propagate through to precursor economics and can change the relative attractiveness of in-house synthesis vs. contract manufacture.
-
Hazard, handling and transport: ADMI’s classification as a highly flammable, water-reactive compound imposes specific ADR/RID and equivalent transport requirements. Companies must budget for specialized packaging, certified carriers and emergency-response training — cost items that are frequently underestimated in early supplier negotiations.
-
Process substitution opportunities: Recent ALD research highlights ADMI as a non-pyrophoric alternative to TMA for certain plasma-enhanced processes. This opens pathways to lower fire-risk operations but can require reformulation work and fresh qualification cycles — a tradeoff that process owners must evaluate with their quality and EHS teams.
A 2026 Decision Playbook — Prioritized Actions
-
Immediate (0–6 months) : Conduct dual-path qualification—identify a primary high-purity supplier and a secondary regional supplier or distributor to mitigate single-source disruption. Initiate audit or desk-based technical due diligence focused on purity analytics and handling procedures.
-
Near-term (6–12 months) : Negotiate supply agreements with explicit performance SLAs (purity, water content, delivery windows) and contingency clauses for force majeure tied to transport restrictions. Establish inventory buffers and evaluate dedicated storage investments at critical fabs.
-
Medium-term (12–24 months) : Invest in co-development partnerships to tailor precursor formulations for specific ALD chemistries; consider off-take or capacity reservation agreements with tier-1 suppliers to lock in supply as demand ramps.
-
Strategic (24+ months) : Evaluate vertical integration or joint-venture production if scale economics and long-term demand justify capital exposure; maintain a rolling scenario plan tied to device-node roadmaps and alternative precursor technologies.
How to Use This Report in Your 2026 Planning Cycle
-
Procurement teams: Use our cost-to-serve and supplier scorecards to reprice contracts and rework IPN/part-number strategies before Q3 renegotiation windows.
-
R&D and process engineering: Leverage the qualification checklists and purity acceptance criteria to shorten time-to-qualify for new precursor streams.
-
Corporate development: Apply the M&A shortlist and scenario models to identify bolt-on targets or JV partners that fill geographic or technical gaps.
-
Risk managers and EHS: Operationalize the regulatory heatmaps and logistics recommendations into playbooks that reduce exposure to transport and storage incidents.
PW Consulting’s study is intentionally tactical in orientation: it combines a probabilistic market model (2026–2032), supplier-level intelligence, and operational guidance required to convert market insight into executable plans. To preserve the strategic value of our proprietary segmentation and supplier benchmarks — the very inputs that enable negotiation leverage and investment discipline — this executive summary omits the detailed regional and application splits. If your 2026 plan depends on knowing demand by region, purity-grade trajectories, or supplier share at the country level, the full report provides the granular datasets, downloadable model, and supplier scorecards necessary to implement the playbook described here.
For a guided walkthrough of the report’s models, or to commission a custom annex (e.g., captive production feasibility, logistics-costing for specific corridors, or bespoke supplier due diligence), PW Consulting’s industry team is available to support tailored engagements that convert insight into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Aluminum Dimethyl Isopropoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com